

Earnings results often indicate what direction a company will take in the months ahead. With Q2 behind us, let’s have a look at Provident Financial Services (NYSE: PFS) and its peers.
Regional banks, financial institutions operating within specific geographic areas, serve as intermediaries between local depositors and borrowers. They benefit from rising interest rates that improve net interest margins (the difference between loan yields and deposit costs), digital transformation reducing operational expenses, and local economic growth driving loan demand. However, these banks face headwinds from fintech competition, deposit outflows to higher-yielding alternatives, credit deterioration (increasing loan defaults) during economic slowdowns, and regulatory compliance costs. Recent concerns about regional bank stability following high-profile failures and significant commercial real estate exposure present additional challenges.
The 94 regional banks stocks we track reported a mixed Q2. As a group, revenues beat analysts’ consensus estimates by 0.6%.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 6.7% since the latest earnings results.
Provident Financial Services (NYSE: PFS)
Founded in 1839 and serving communities across New Jersey, Pennsylvania, and New York, Provident Financial Services (NYSE: PFS) operates a regional bank providing commercial, residential, and consumer lending alongside wealth management and insurance services.
Provident Financial Services reported revenues of $235 million, up 9.7% year on year. This print exceeded analysts’ expectations by 2.6%. Overall, it was a strong quarter for the company with a narrow beat of analysts’ net interest income estimates and a beat of analysts’ EPS estimates.
Anthony J. Labozzetta, President and Chief Executive Officer commented, “Through the first half of 2026, Provident has grown earnings per share 17% year-over-year while also significantly improving our profitability and building capital. We achieved record pre-provision net revenue during the second quarter, driven by strong commercial loan production, expanding core margin and increasing contribution from non-interest income, which represented nearly 14% of total revenues. We are proud of the noticeable momentum of our organization, and I’m optimistic that we will continue to drive organic growth with an unchanged commitment to achieving top quartile risk-adjusted returns."
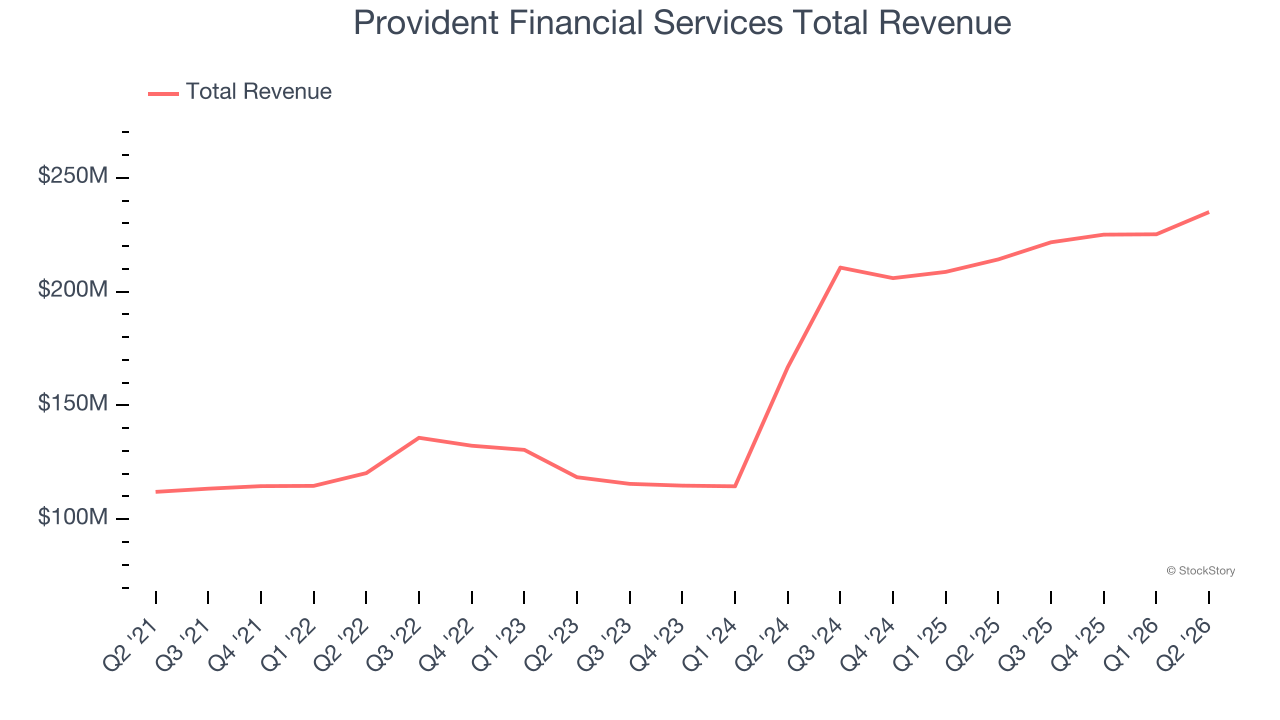
Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 7.7% since reporting and currently trades at $22.23.
Is now the time to buy Provident Financial Services? Access our full analysis of the earnings results here, it’s free.
Best Q2: OFG Bancorp (NYSE: OFG)
Originally founded in 1964 as a federal savings and loan institution, OFG Bancorp (NYSE: OFG) provides banking and financial services including commercial and consumer lending, wealth management, insurance, and trust services primarily in Puerto Rico and the U.S. Virgin Islands.
OFG Bancorp reported revenues of $190.3 million, up 4.4% year on year, outperforming analysts’ expectations by 3.9%. The business had an exceptional quarter with a beat of analysts’ EPS estimates and a solid beat of analysts’ net interest income estimates.
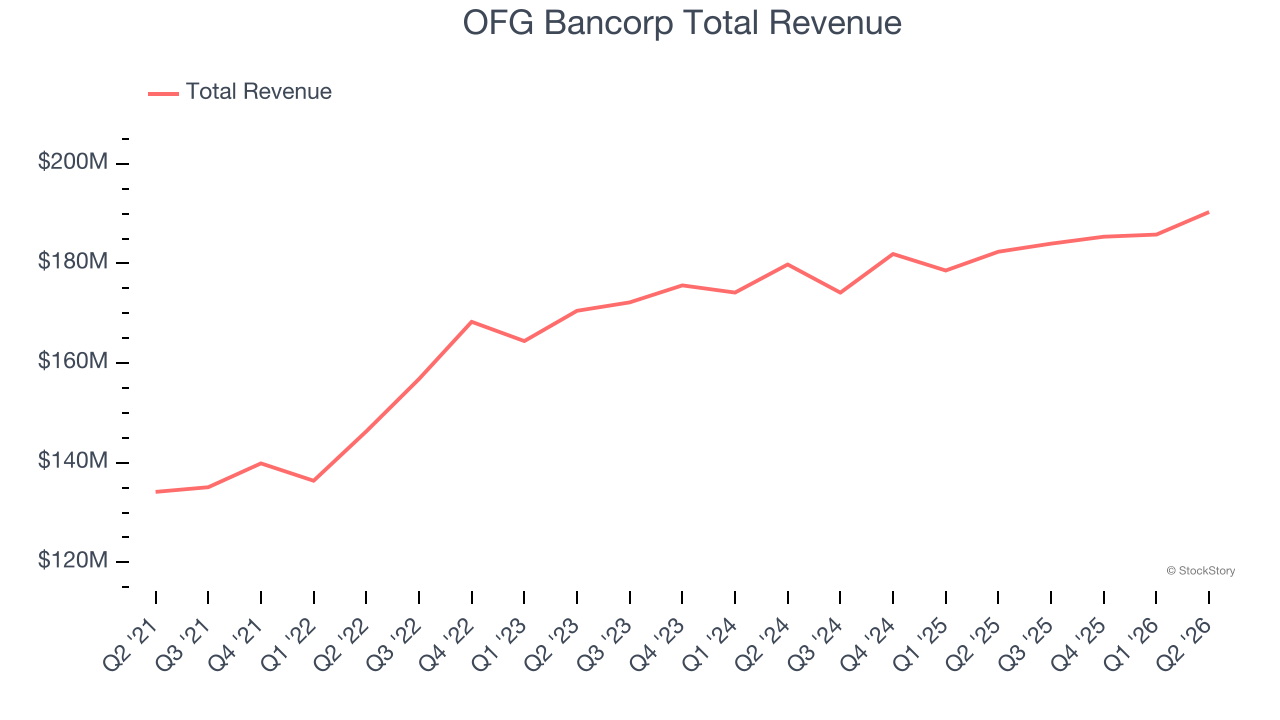
The market seems content with the results as the stock is up 1% since reporting. It currently trades at $50.50.
Is now the time to buy OFG Bancorp? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Banc of California (NYSE: BANC)
Originally established in 1941 and now operating with a tech-forward approach that includes its SmartStreet platform for homeowner associations, Banc of California (NYSE: BANC) is a California-based bank holding company that provides banking services to small and middle-market businesses, entrepreneurs, and individuals.
Banc of California reported revenues of $285.7 million, up 4.7% year on year, falling short of analysts’ expectations by 3.1%. It was a disappointing quarter as it posted a significant miss of analysts’ tangible book value per share estimates and a significant miss of analysts’ net interest income estimates.
As expected, the stock is down 18.3% since the results and currently trades at $17.31.
Read our full analysis of Banc of California’s results here.
Byline Bancorp (NYSE: BY)
Ranking as the fifth most active Small Business Administration lender in the country, Byline Bancorp (NYSE: BY) is a Chicago-based bank that provides banking services to small and medium-sized businesses, commercial real estate developers, and consumers.
Byline Bancorp reported revenues of $117.7 million, up 6.6% year on year. This result beat analysts’ expectations by 1.8%. It was a strong quarter as it also put up a beat of analysts’ EPS estimates and net interest income in line with analysts’ estimates.
The stock is down 1.9% since reporting and currently trades at $36.91.
Read our full, actionable report on Byline Bancorp here, it’s free.
KeyCorp (NYSE: KEY)
Tracing its roots back to 1849 during the California Gold Rush era, KeyCorp (NYSE: KEY) operates KeyBank, a full-service regional bank providing retail and commercial banking, wealth management, and investment services across 15 states.
KeyCorp reported revenues of $1.96 billion, up 6.7% year on year. This print was in line with analysts’ expectations. More broadly, it was a slower quarter as it logged a slight miss of analysts’ net interest income estimates and a miss of analysts’ tangible book value per share estimates.
The stock is down 13.6% since reporting and currently trades at $20.16.
Read our full, actionable report on KeyCorp here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.