Regional banking company FirstSun Capital Bancorp (NASDAQ: FSUN) fell short of the market’s revenue expectations in Q3 2026, but revenue rose 84.9% year on year to $179.7 million. Its non-GAAP profit of $1.03 per share was 6.2% above analysts’ consensus estimates.
For more on FirstSun Capital Bancorp, read our free full research report.
FirstSun Capital Bancorp (FSUN) Q3 2026 highlights:
- Net interest income $140.3 million vs analyst estimates of $140.8 million (73.3% year-on-year growth, mostly attributable to First Foundation acquisition, in line)
- Net interest margin 3.8% vs analyst estimates of 3.8% (4 basis point beat)
- Revenue $179.7 million vs S&P analysts’ estimates of $181 million (84.9% year-on-year growth, mostly attributable to First Foundation acquisition, 0.7% miss)
- Adjusted EPS $1.03 vs S&P analysts’ estimates of $0.97 (6.2% beat)
- Tangible book value per share $35.60 vs analyst estimates of $35.92 (3.6% year-on-year decline, 0.9% miss)
- Market capitalization $1.85 billion
“Additionally, in late September, we successfully completed the core system conversion of First Foundation, representing another important milestone in our overall integration plan. I'm extremely proud of our teammates for all the hard work, planning and collaboration in completing the conversion while continuing to serve our great clients throughout the process. We remain focused on continuing to grow our franchise and delivering strong financial results and sustainable long-term value for our stockholders.”
Revenue growth
In general, banks make money from two primary sources. The first is net interest income, which is interest earned on loans, mortgages and investments in securities minus interest paid out on deposits. The second source is non-interest income, which can come from bank account, credit card, wealth management, investment banking and trading fees. Over the last five years, FirstSun Capital Bancorp grew its revenue at a solid 13.9% compounded annual growth rate, outpacing the average banking company. However, much of its recent growth was attributable to the First Foundation acquisition rather than organic expansion, an important distinction when evaluating its underlying performance.
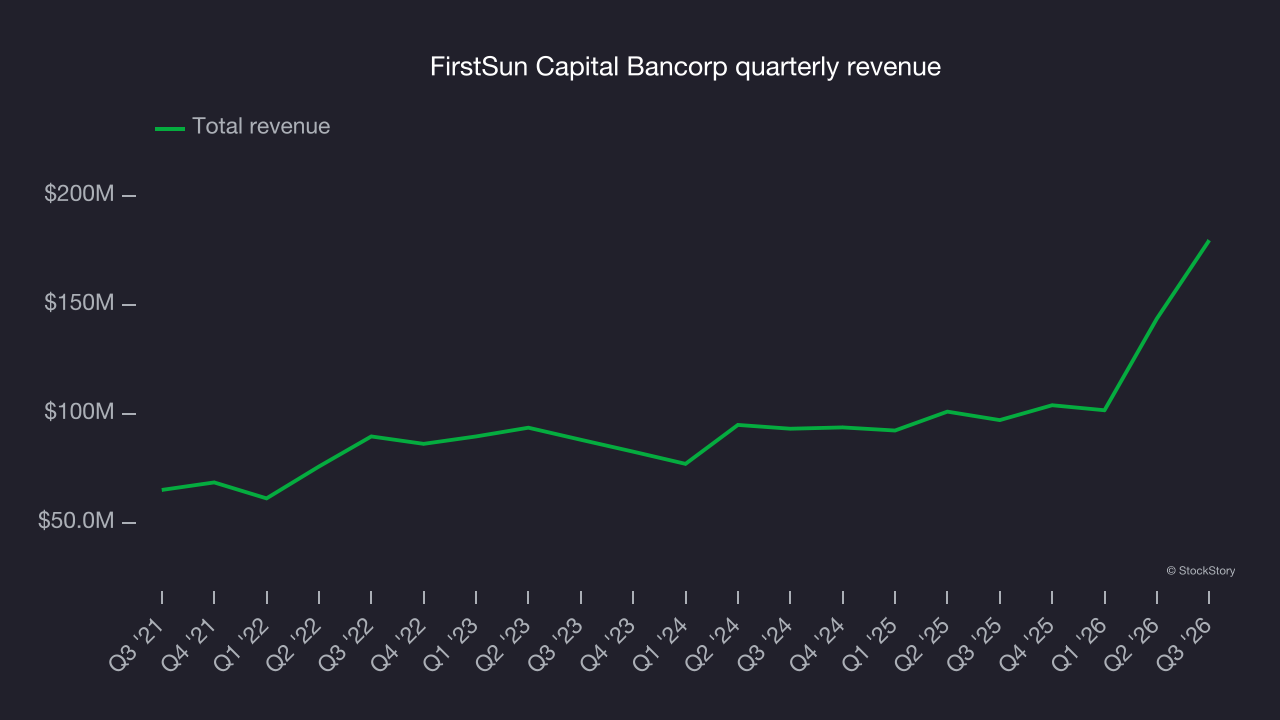
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. FirstSun Capital Bancorp’s annualized revenue growth of 23.3% over the last two years is above its five-year trend, largely attributable to the First Foundation acquisition.
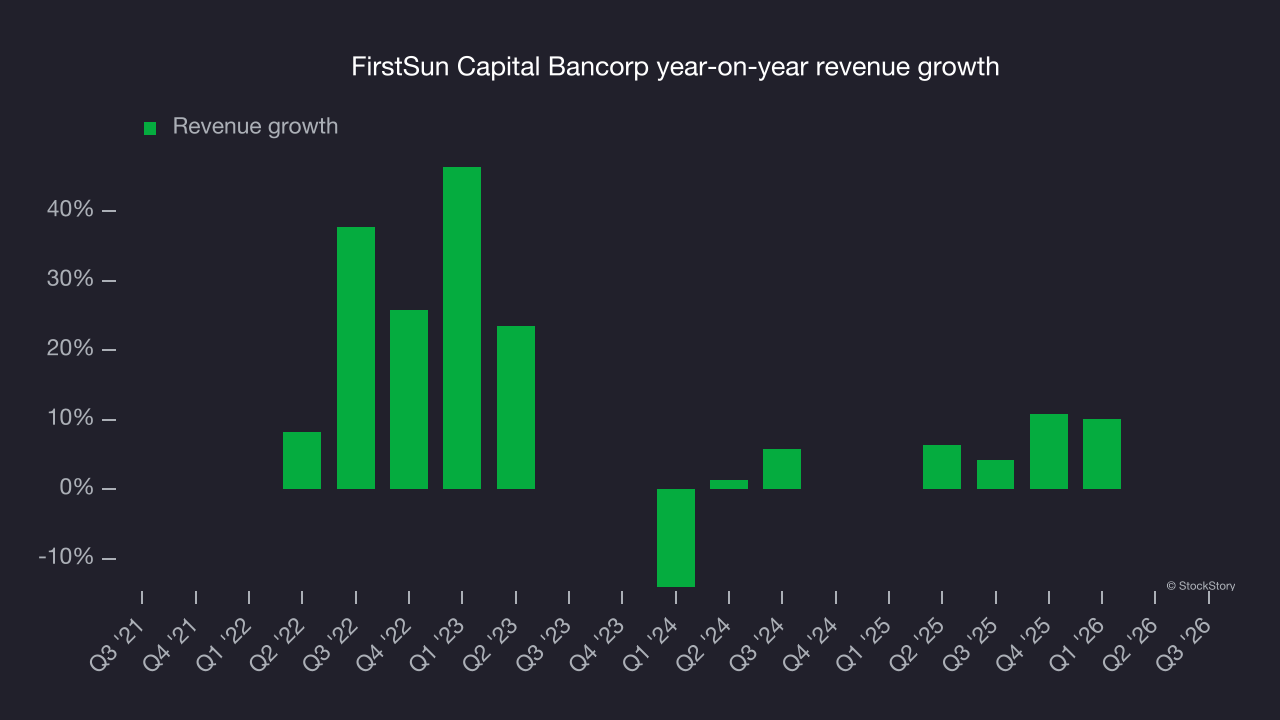
Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, FirstSun Capital Bancorp achieved a magnificent 84.9% year-on-year revenue growth rate, mostly attributable to the First Foundation acquisition, but its $179.7 million of revenue fell short of Wall Street’s lofty estimates.
Net interest income made up 80.5% of the company’s total revenue during the last five years, meaning FirstSun Capital Bancorp relies relatively little on non-interest income to drive its overall growth.
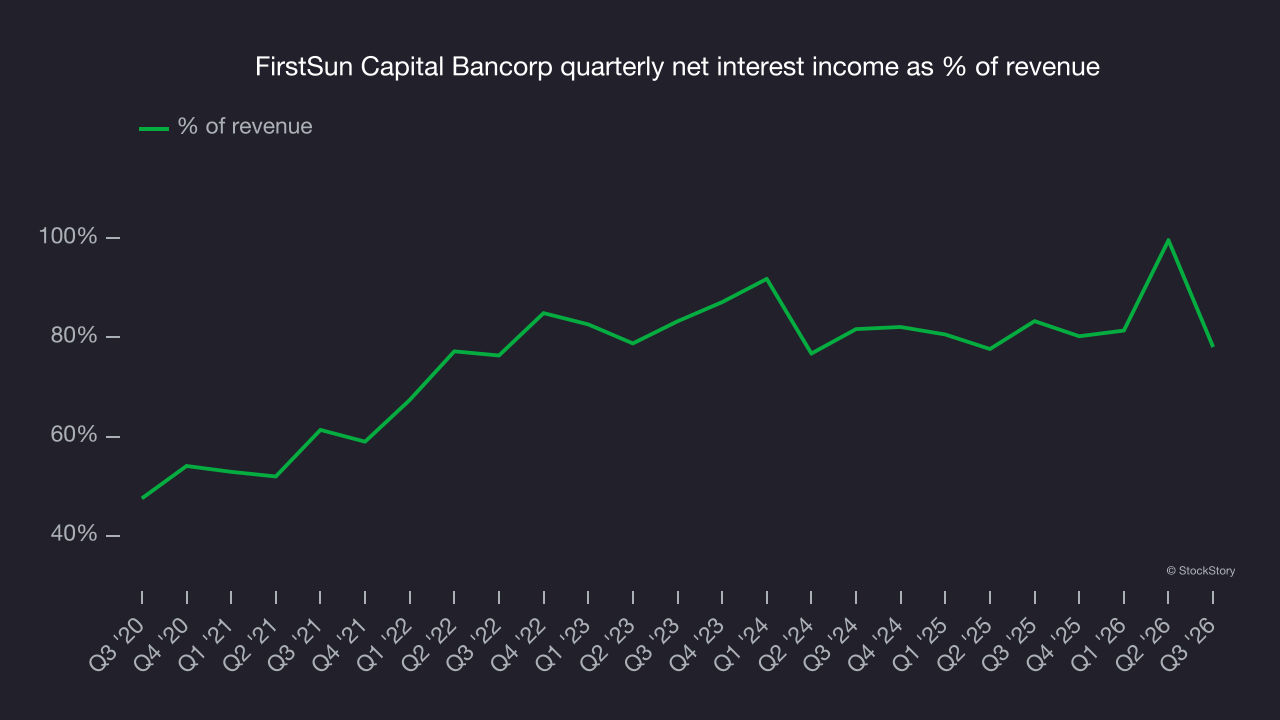
While banks generate revenue from multiple sources, investors view net interest income as the cornerstone – its predictable, recurring characteristics stand in sharp contrast to the volatility of non-interest income.
Tangible book value per share (TBVPS)
The balance sheet drives banking profitability since earnings flow from the spread between borrowing and lending rates. As such, valuations for these companies concentrate on capital strength and sustainable equity accumulation potential.
This explains why tangible book value per share (TBVPS) is a leading banking metric. TBVPS strips away questionable intangible assets, providing a more reliable view of per-share net worth. On the other hand, EPS is often distorted by mergers and flexible loan loss accounting. TBVPS provides clearer performance insights.
FirstSun Capital Bancorp’s TBVPS grew at a solid 6.4% annual rate over the last five years. However, growth has recently slowed to 2.8% annually over the last two years (from $33.68 to $35.60 per share).
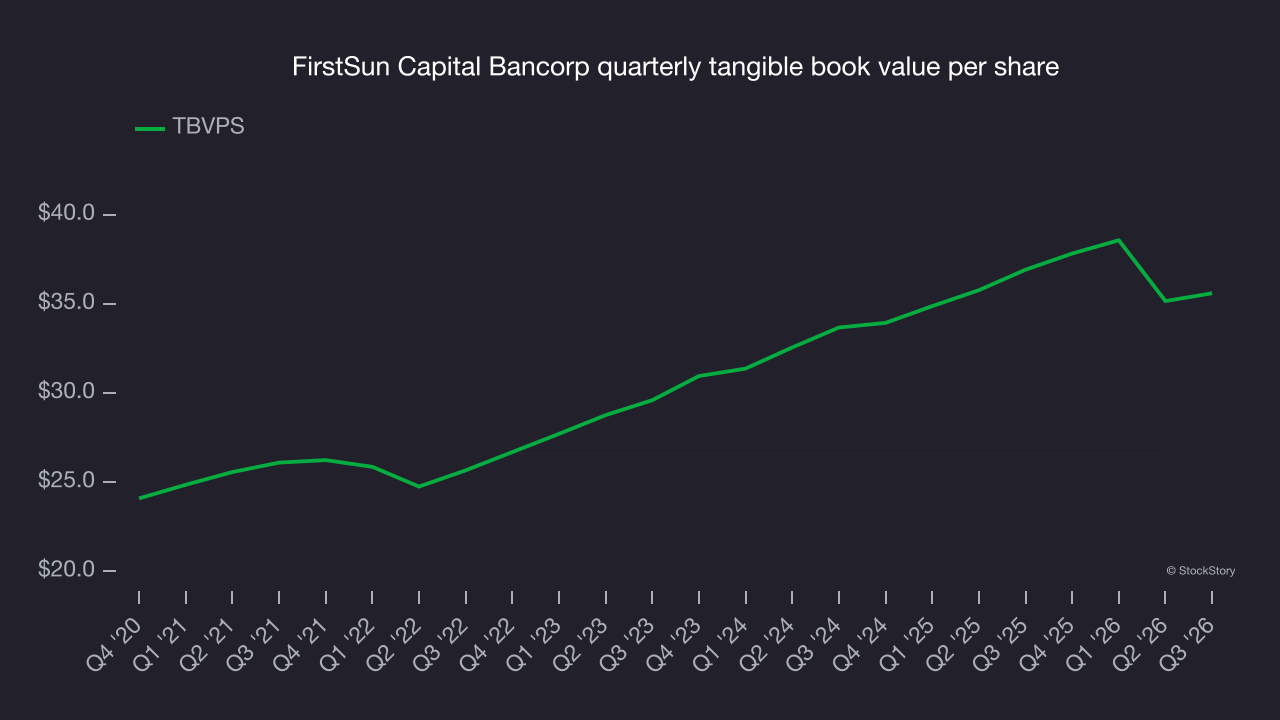
Over the next 12 months, consensus estimates call for FirstSun Capital Bancorp’s TBVPS to grow by 14.3% to $40.69, a decent growth rate.
Key takeaways from FirstSun Capital Bancorp’s Q3 results
FirstSun Capital Bancorp’s quarter offered few positives: Revenue and tangible book value per share both came in slightly below Wall Street’s consensus estimates, making this a softer quarter. Shares remained flat at $39.81 immediately after the results.
For investors considering FirstSun Capital Bancorp at its current price, the latest quarter is only one piece of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. For more on FirstSun Capital Bancorp, read the full research report here (it’s free).