
Over the past six months, 8x8 has been a great trade, beating the S&P 500 by 13.1%. Its stock price has climbed to $2.19, representing a healthy 34.3% increase. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy 8x8, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think 8x8 Will Underperform?
We’re glad investors have benefited from the price increase, but we’re cautious about 8x8. Here are three reasons why there are better opportunities than EGHT, plus one stock we’d rather own.
1. Weak Billings Point to Soft Demand
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
8x8’s billings came in at $188.8 million in Q2, and over the last four quarters, its year-on-year growth averaged 1.3%. This performance was underwhelming and suggests that increasing competition is causing challenges in acquiring/retaining customers. 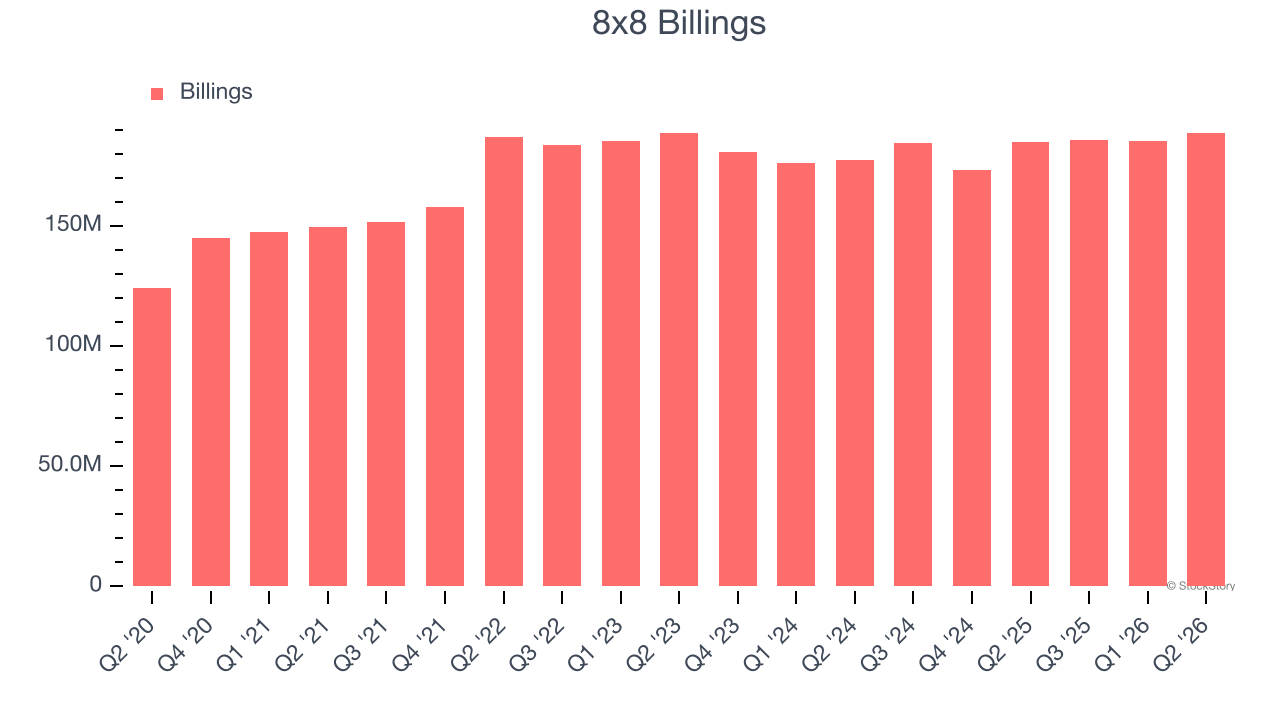
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect 8x8’s revenue to rise by 2.6%, close to its 5.9% annualized growth for the past five years. This projection is underwhelming and suggests its newer products and services will not accelerate its top-line performance yet.
3. Operating Margin in Limbo
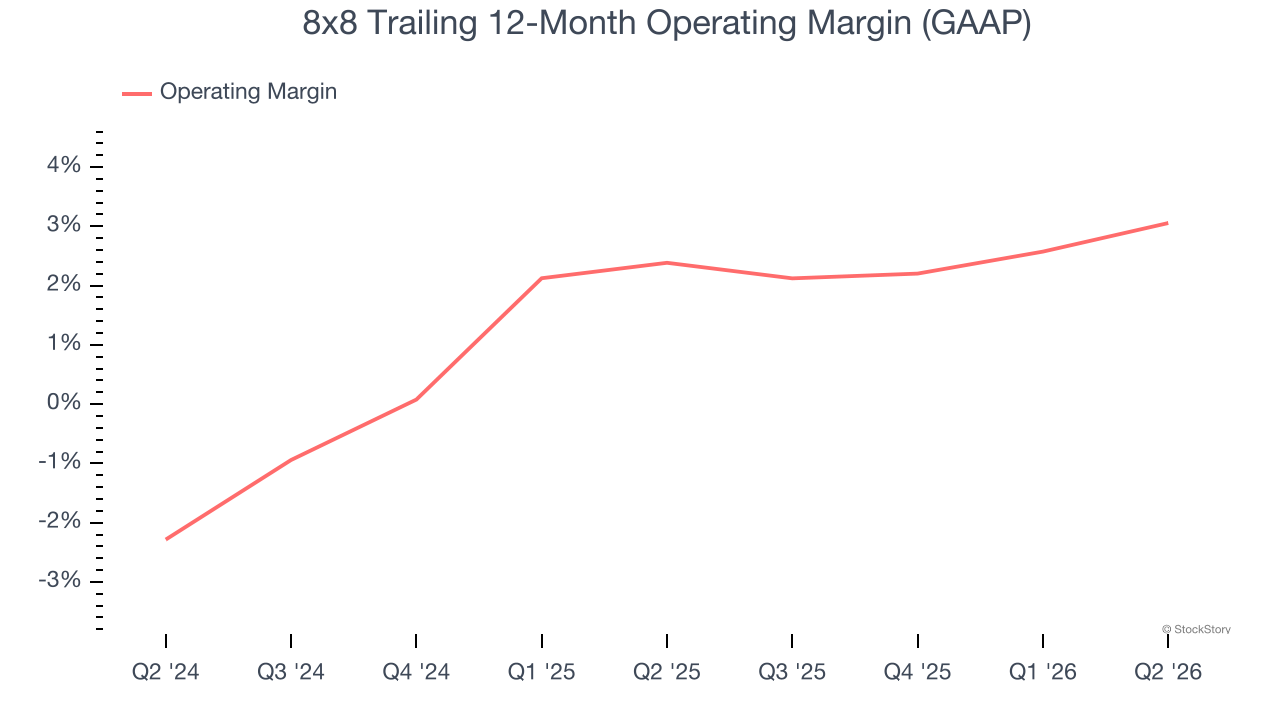
Many software businesses adjust their profits for stock-based compensation (SBC), but we prioritize GAAP operating margin because SBC is a real expense used to attract and retain engineering and sales talent. This is one of the best measures of profitability because it shows how much money a company takes home after developing, marketing, and selling its products.
Analyzing the trend in its profitability, 8x8’s operating margin might have fluctuated slightly but has generally stayed the same over the last two years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its operating margin for the trailing 12 months was 3.1%.
Final Judgment
8x8 doesn’t pass our quality test. With its shares topping the market in recent months, the stock trades at 0.4× forward price-to-sales (or $2.19 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better investments elsewhere. We’d suggest looking at one of Charlie Munger’s all-time favorite businesses.
Stocks We Would Buy Instead of 8x8
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.