

Over the last six months, Carter’s shares have sunk to $31.33, producing a disappointing 9.7% loss - a stark contrast to the S&P 500’s 21.1% gain. This might have investors contemplating their next move.
Is now the time to buy Carter's, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Carter's Will Underperform?
Even though the stock has become cheaper, we’re sitting this one out for now. Here are three reasons you should be careful with CRI, plus one stock we’d rather own.
1. Same-Store Sales Falling Behind Peers
Investors interested in Consumer Discretionary - Apparel and Accessories companies should track same-store sales in addition to reported revenue. This metric measures the change in sales at brick-and-mortar locations that have existed for at least a year, giving visibility into Carter’s underlying demand characteristics.
Over the last two years, Carter’s same-store sales averaged 1.1% year-on-year growth. This performance was underwhelming and suggests it might have to change its strategy or pricing, which can disrupt operations. 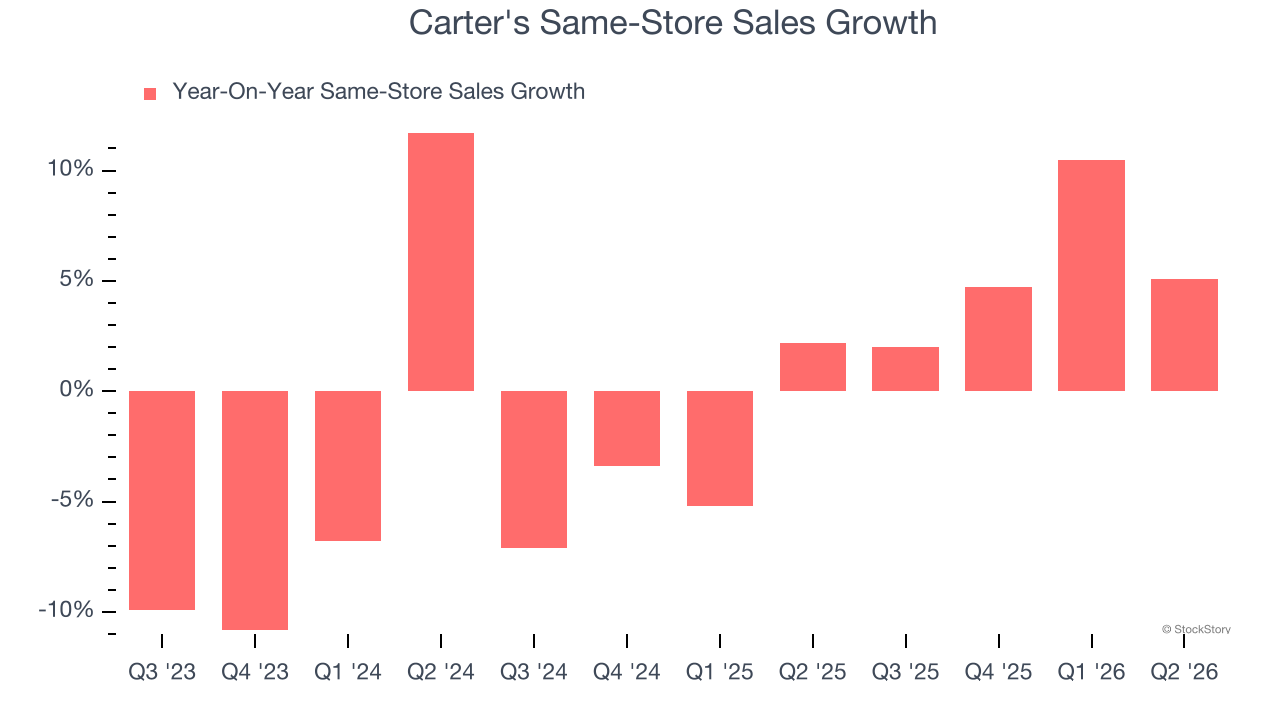
2. Cash Flow Margin Set to Decline
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Over the next year, analysts predict Carter’s cash conversion will slightly fall. Their consensus estimates imply its free cash flow margin of 9.8% for the last 12 months will decrease to 4.1%.
3. New Investments Fail to Bear Fruit as ROIC Declines
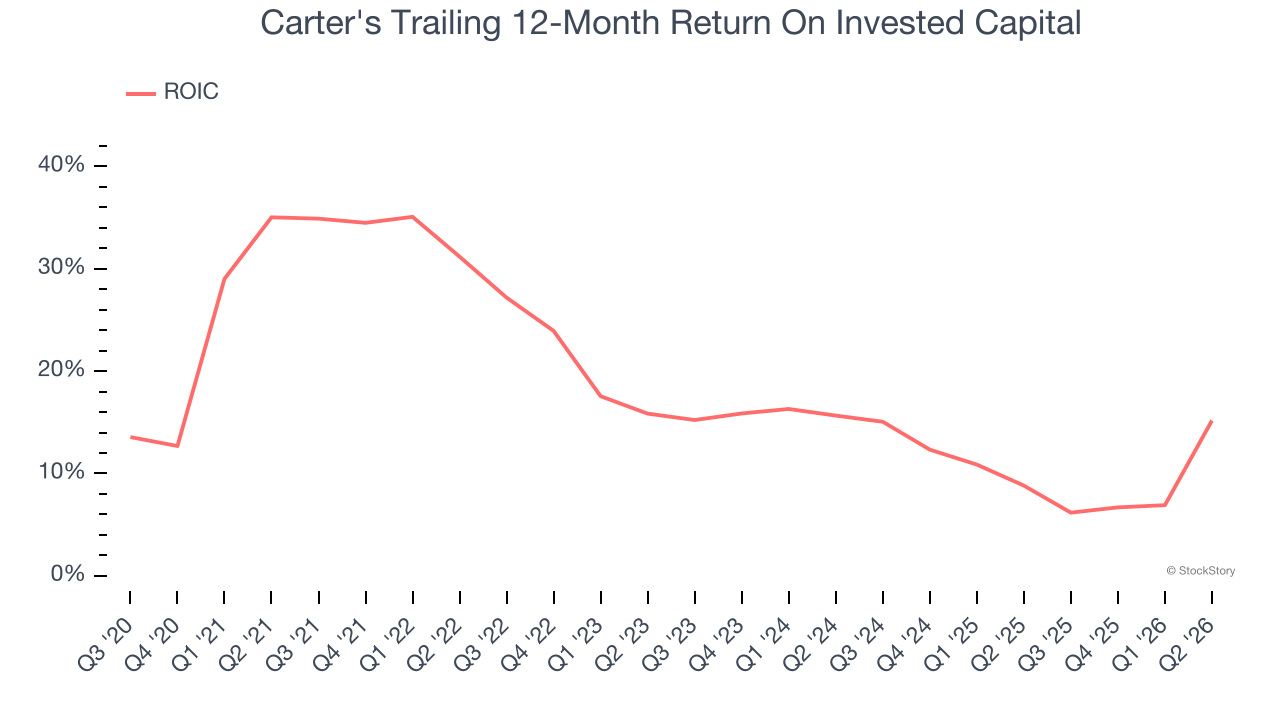
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Over the last few years, Carter’s ROIC has unfortunately decreased significantly. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
Final Judgment
We see the value of companies helping consumers, but in the case of Carter's, we’re out. After the recent drawdown, the stock trades at 8.8× forward P/E (or $31.33 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better stocks to buy right now. We’d suggest looking at a safe-and-steady industrials business benefiting from an upgrade cycle.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.