
Since March 2026, KeyCorp has been in a holding pattern, posting a small return of 3.9% while floating around $20.16. The stock also fell short of the S&P 500’s 21.1% gain during that period.
Is there a buying opportunity in KeyCorp, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is KeyCorp Not Exciting?
We’re sitting this one out for now. Here are three reasons you should be careful with KEY, plus one stock we’d rather own.
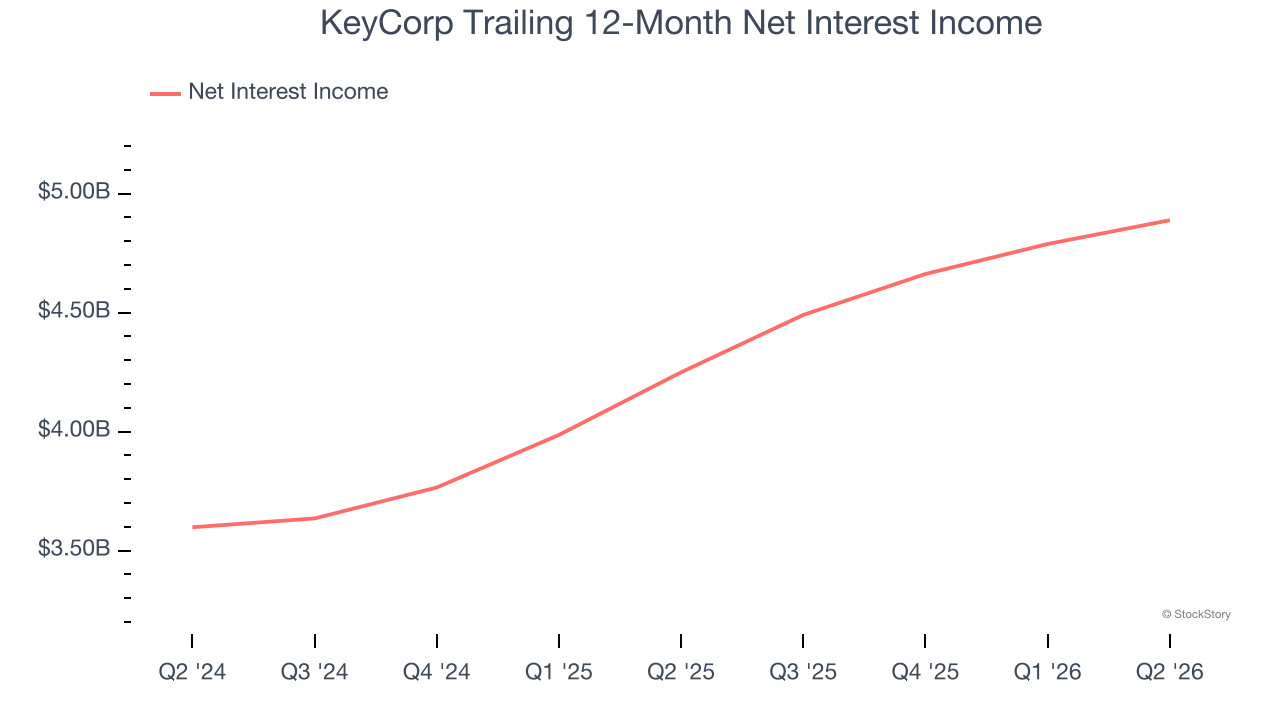
1. Net Interest Income Points to Soft Demand
Net interest income commands greater market attention due to its reliability and consistency, whereas one-time fees are often seen as lower-quality revenue that lacks the same dependable characteristics.
KeyCorp’s net interest income has grown at a 3.8% annualized rate over the last five years, much worse than the broader banking industry. Its growth was driven by both an increase in its outstanding loans and net interest margin, which represents how much a bank earns in relation to its outstanding loan book.
2. EPS Trending Down
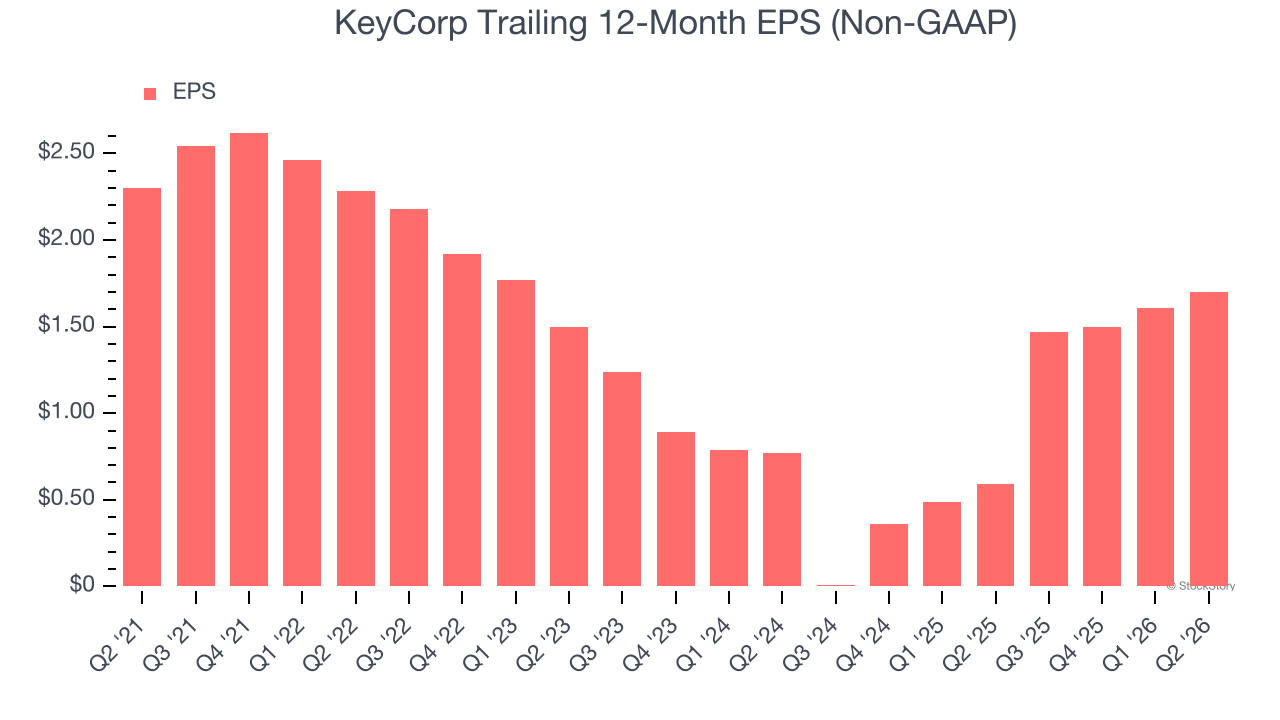
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for KeyCorp, its EPS declined by 5.9% annually over the last five years while its revenue grew by 2.1%. This tells us the company became less profitable on a per-share basis as it expanded.
3. Growing TBVPS Reflects Strong Asset Base
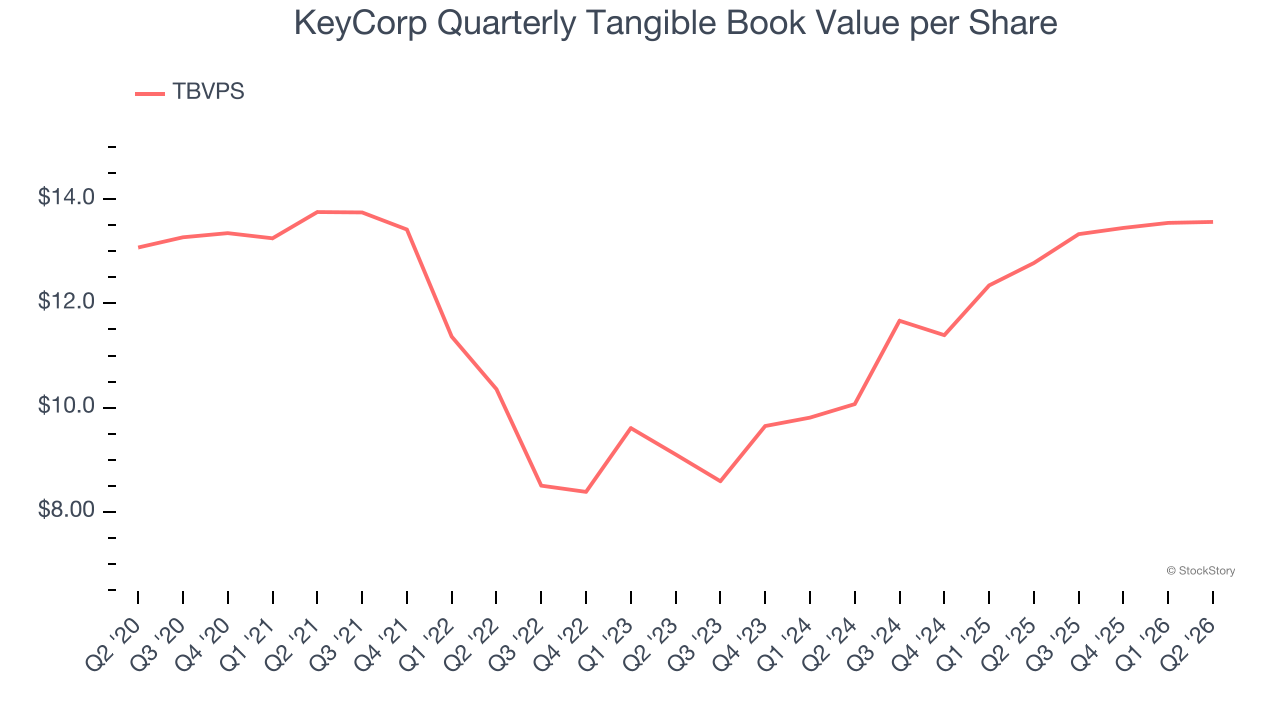
We consider tangible book value per share (TBVPS) the most important metric to track for banks. TBVPS represents the real, liquid net worth per share of a bank, excluding intangible assets that have debatable value upon liquidation.
Although KeyCorp’s TBVPS was flat over the last five years, the good news is that its growth has recently accelerated as TBVPS grew at an excellent 16.1% annual clip over the past two years (from $10.07 to $13.57 per share).
Final Judgment
KeyCorp isn’t a terrible business, but it isn’t one of our picks. With its shares lagging the market recently, the stock trades at 1.2× forward P/B (or $20.16 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re pretty confident there are more exciting stocks to buy at the moment. Let us point you toward a safe-and-steady industrials business benefiting from an upgrade cycle.
Stocks We Like More Than KeyCorp
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.