Money transfer company Western Union (NYSE: WU) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 2.3% year on year to $1.01 billion. Its non-GAAP profit of $0.42 per share was 24.1% above analysts’ consensus estimates.
For more on Western Union, read our free full research report.
Western Union (WU) Q3 2026 highlights:
- Revenue $1.01 billion vs S&P analysts’ consensus estimates of $1.02 billion (2.3% year-on-year decline, 1.2% miss)
- Pre-tax profit $96.1 million (9.5% margin)
- Adjusted EPS $0.42 vs S&P analysts’ consensus estimates of $0.34 (24.1% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $1.33 at the midpoint, a 2.3% increase
- Market capitalization $1.95 billion
“As we move through the second half of the year, we continue to make progress against our Beyond strategy,” said Devin McGranahan, President and Chief Executive Officer. “Importantly, the initiatives we launched in the second quarter are streamlining our cost structure and have begun to materialize in our financial results. At the same time, we continue to invest in growth, including expanding our digital capabilities, embedding AI across key operational processes, and advancing our stablecoin and next-generation money movement initiatives. We are beginning to see the impact of all of these efforts and remain confident in our ability to improve performance and create long-term shareholder value.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. Western Union’s demand was weak over the last five years as its revenue fell at a 4.5% annual rate. This fell short of our standards and suggests poor business quality.
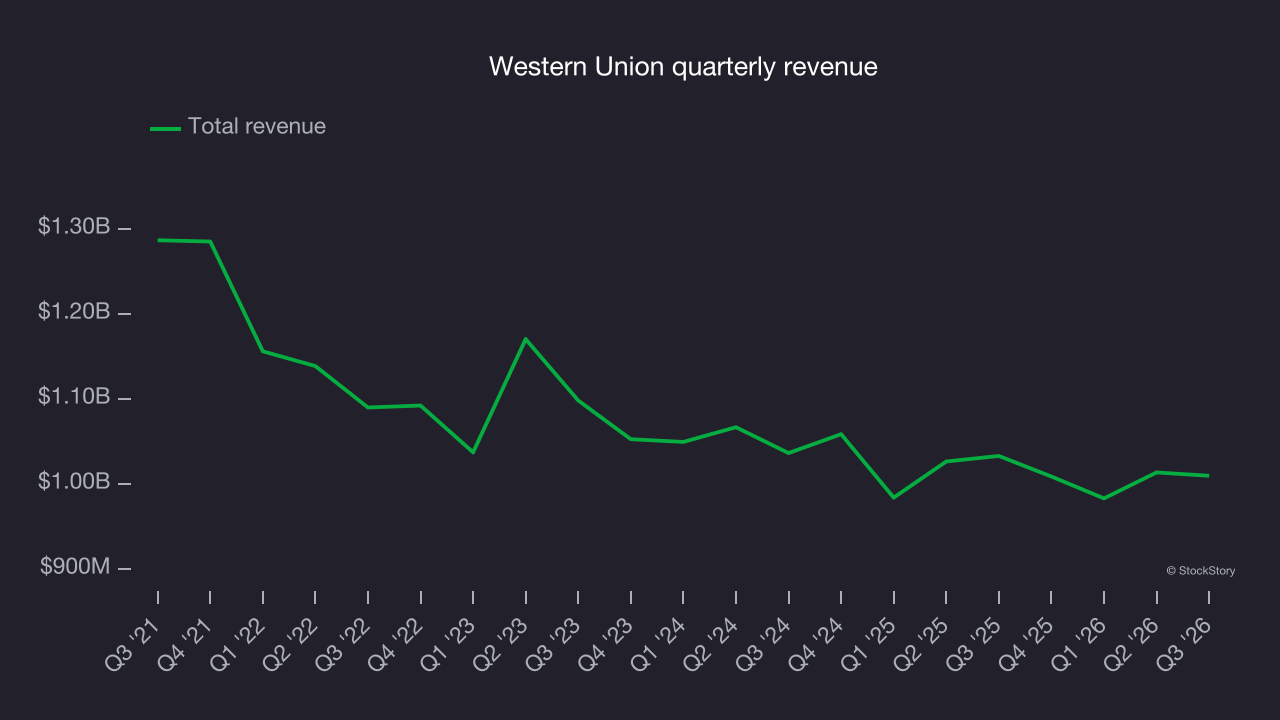
Long-term growth matters most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. Western Union’s annualized revenue declines of 2.3% over the last two years suggest its demand continued shrinking. 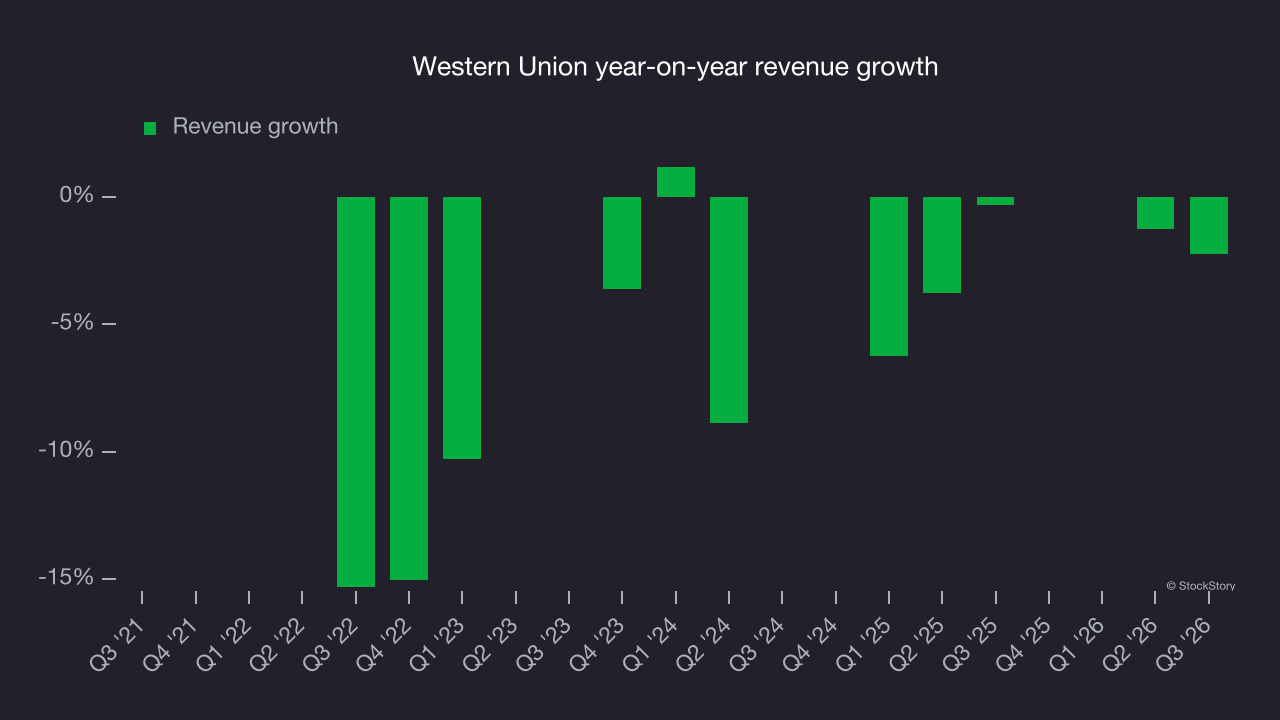 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Western Union missed Wall Street’s consensus estimates and reported an uninspiring 2.3% year-on-year revenue decline, generating $1.01 billion in revenue.
Key takeaways from Western Union’s Q3 results
Western Union’s EPS beat and full-year EPS guidance above Wall Street’s consensus estimates made for a solid quarter, despite a slight revenue miss. Shares rose 3.1% to $6.80 immediately after the results.
Western Union had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. The latest quarter is only one piece of the longer-term business quality puzzle. Quality, combined with valuation, can help determine whether the stock is a buy. For more on those factors, read our full research report here (it’s free).