Fast-food company Restaurant Brands (NYSE: QSR) fell short of the market’s revenue expectations in Q3 2026 as revenue rose 3.1% year on year to $2.53 billion. Its non-GAAP profit of $1.10 per share was 1.4% above analysts’ consensus estimates.
For more on Restaurant Brands, read our free full research report.
Restaurant Brands (QSR) Q3 2026 highlights:
- Revenue $2.53 billion vs S&P analysts’ consensus estimates of $2.55 billion (3.1% year-on-year growth, 1% miss)
- Adjusted EPS $1.10 vs S&P analysts’ consensus estimates of $1.08 (1.4% beat)
- Adjusted EBITDA $829 million vs analysts’ consensus estimates of $839.2 million (32.8% margin, 1.2% miss)
- Operating margin 27.6%, in line with the same quarter last year
- Free cash flow margin 19%, down from 21.7% in the same quarter last year
- Locations 33,401 at quarter end, up from 32,423 in the same quarter last year
- Same-store sales rose 3.8% year on year, in line with the same quarter last year
- Market capitalization $25.99 billion
MIAMI, Oct. 29, 2026 /PRNewswire/ -- Restaurant Brands International Inc. ("RBI") (NYSE: QSR) (TSX: QSR) (TSX: QSP) today reported financial results for the third quarter ended September 30, 2026. Josh Kobza, Chief Executive Officer of RBI commented, "At our Investor Day earlier this year, we highlighted what makes RBI a strong business – four iconic global brands, the ability to invest for long-term growth, and talented teams and franchisees around the world. Those strengths are on display again this quarter, with over 3% global comparable sales led by outperformance at Burger King and steady growth at International and Tim Hortons. I'm proud of what we're accomplishing together. Across our brands, we're continuing to listen to our guests and act on their feedback to deliver the quality, service, and convenience they expect every day."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can post a good quarter or two, but the best consistently grow over the long haul.
With $9.78 billion in revenue over the past 12 months, Restaurant Brands is one of the most widely recognized restaurant chains and benefits from customer loyalty, an advantage many don’t have. Its scale also gives it negotiating leverage with suppliers, enabling it to source its ingredients at a lower cost.
Restaurant Brands grew its revenue at a decent 8.5% compounded annual growth rate over the last seven years as it opened new restaurants and increased revenue at existing, established dining locations.
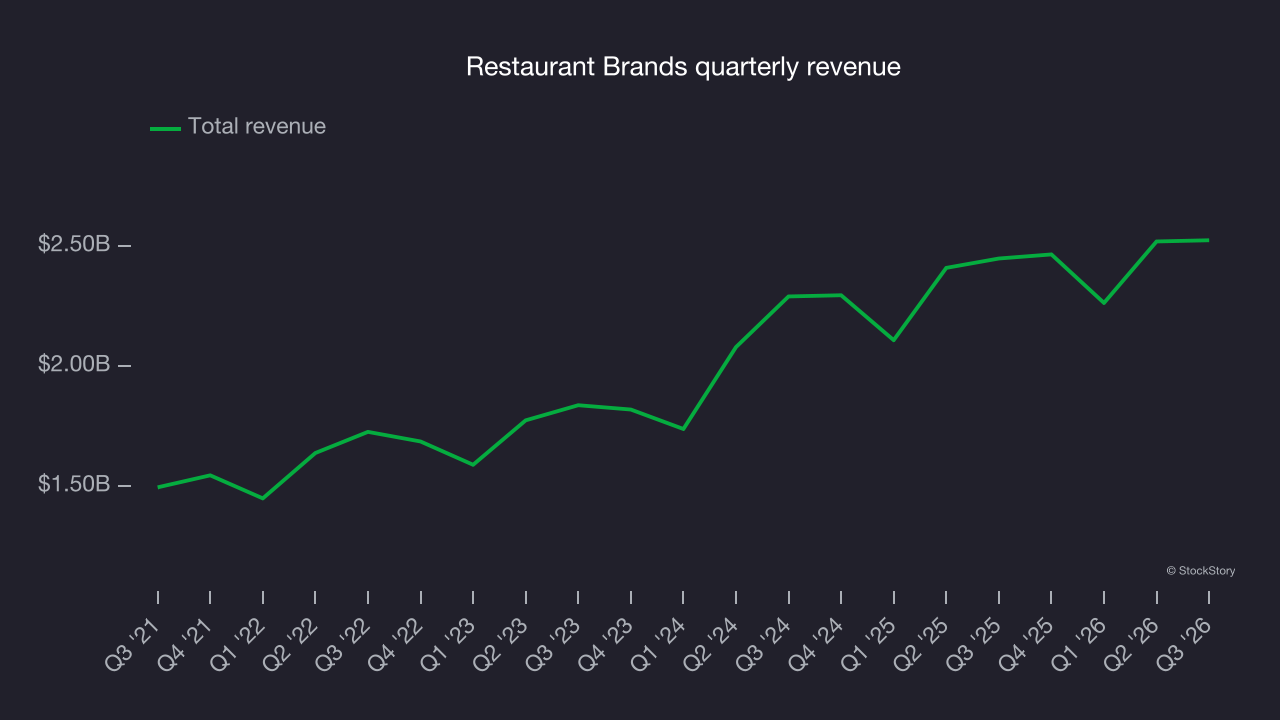
This quarter, Restaurant Brands’s revenue grew by 3.1% year on year to $2.53 billion, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 1.3% over the next 12 months, according to S&P, a deceleration versus the last seven years. This projection is underwhelming and indicates its menu offerings will see some demand headwinds. Still, the company is tracking well in other measures of financial health.
Restaurant performance
Number of restaurants
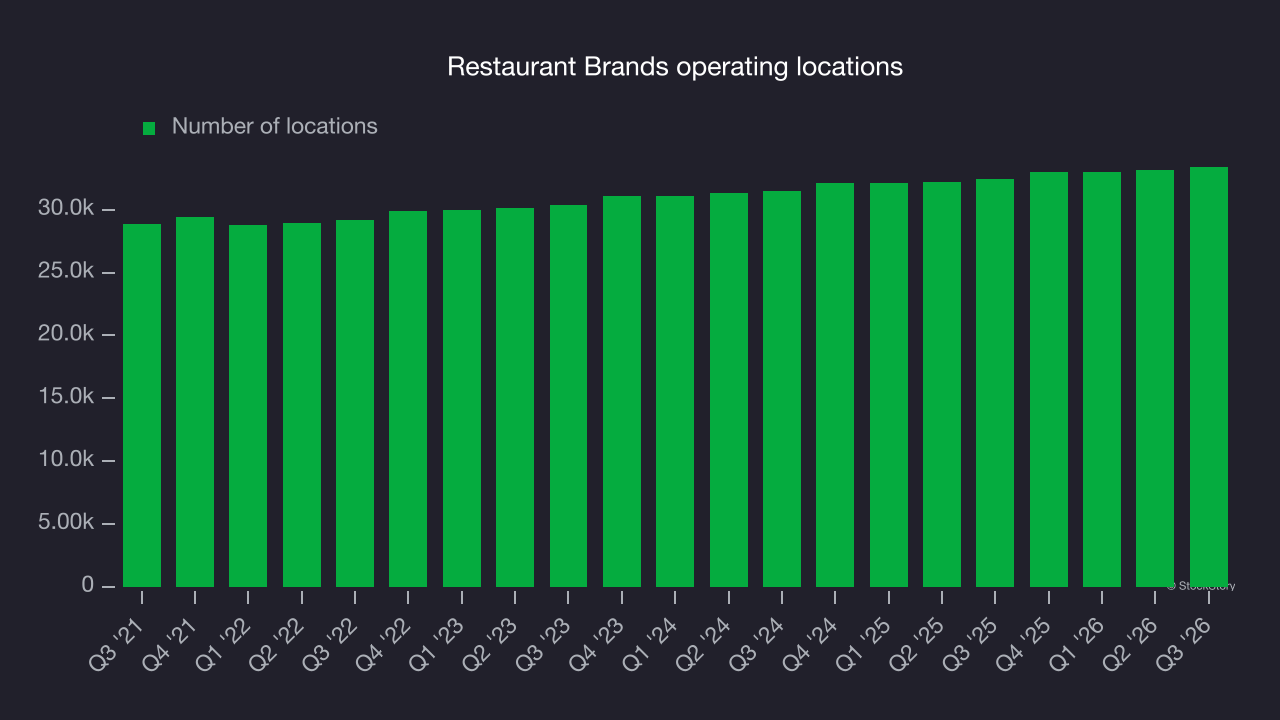
Restaurant Brands operated 33,401 locations in the latest quarter. It has opened new restaurants quickly over the last two years, averaging 3% annual growth, faster than the broader restaurant sector. Additionally, the company’s franchise model makes expansion easier: franchisees are primarily responsible for opening new restaurants while Restaurant Brands provides support.
When a chain opens new restaurants, it usually means it’s investing for growth because there’s healthy demand for its meals and there are markets where its concepts have few or no locations.
Same-store sales
The change in a company’s restaurant base only tells one side of the story. The other is the performance of its existing locations, which informs management teams whether they should expand or downsize their physical footprints. Same-store sales provide a deeper understanding of this issue because they measure organic growth at restaurants open for at least a year.
Restaurant Brands’s demand has been healthy for a restaurant chain over the last two years. On average, the company has grown its same-store sales by 2.9% per year. This performance suggests its rollout of new restaurants could be beneficial for shareholders. When a chain has demand, more locations should help it reach more customers and boost revenue growth.
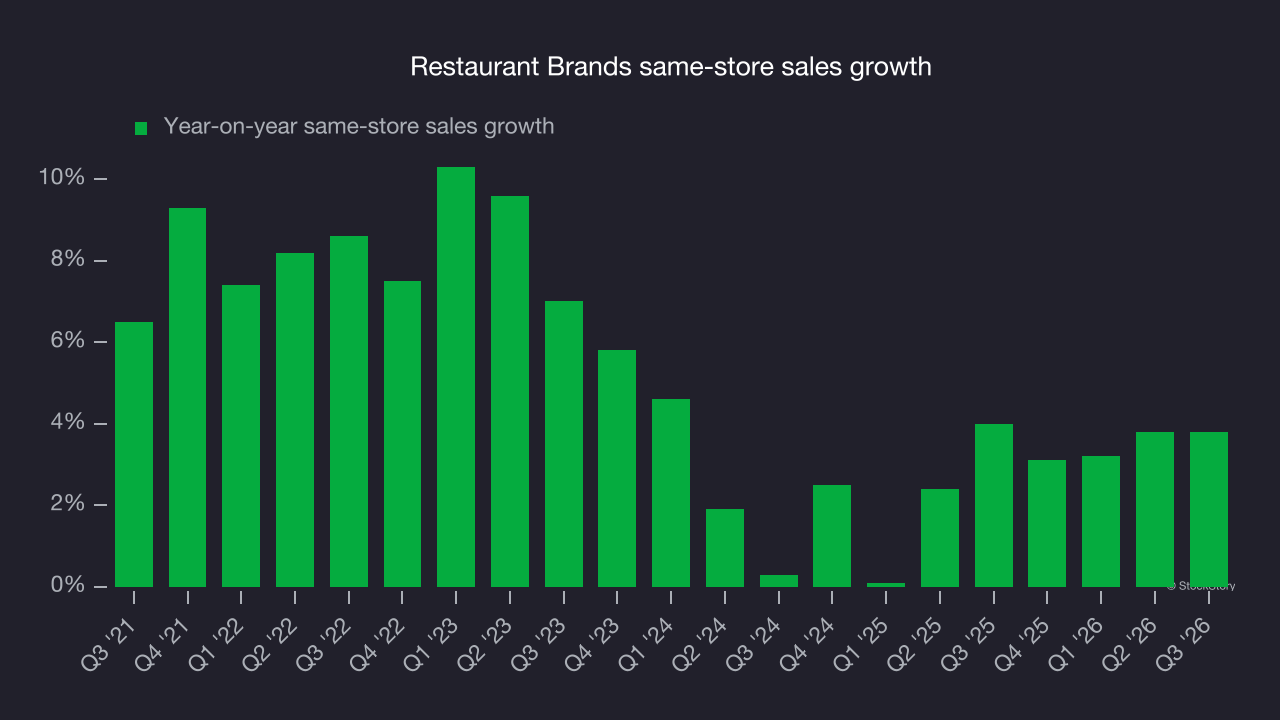
In the latest quarter, Restaurant Brands’s same-store sales rose 3.8% year on year. This performance was more or less in line with its historical levels.
Key takeaways from Restaurant Brands’s Q3 results
Restaurant Brands’ quarter could have been better: Same-store sales narrowly topped analysts’ consensus estimates, but revenue and EBITDA both fell slightly short of Wall Street’s consensus estimates. Shares edged lower 1.1% to $73.68 immediately after the report.
Considering Restaurant Brands at its current price? The latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when deciding whether to buy the stock. For more, read the full research report here (it’s free).