Regional banking company Renasant (NYSE: RNST) missed Wall Street’s revenue expectations in Q3 2026, with revenue flat year on year at $273 million. Its non-GAAP profit of $0.86 per share was 8.8% below analysts’ consensus estimates.
For more on Renasant, read our free full research report.
Renasant (RNST) Q3 2026 highlights:
- Net interest income $223.7 million vs analysts’ consensus estimates of $231.2 million (flat year on year, 3.3% miss)
- Net interest margin 3.8% vs analysts’ consensus estimates of 3.8% (4.3 basis point miss)
- Revenue $273 million vs S&P analysts’ consensus estimates of $282.3 million (flat year on year, 3.3% miss)
- Efficiency ratio 57.7% vs analysts’ consensus estimates of 55.7% (203.9 basis point miss)
- Adjusted EPS $0.86 vs S&P analysts’ consensus estimates of $0.94 (8.8% miss)
- Tangible book value per share $25.29 vs analysts’ consensus estimates of $25.91 (6.4% year-on-year growth, 2.4% miss)
- Market capitalization $3.82 billion
“Third quarter results reflect strong loan growth with a record level of loan production, continued momentum in core deposit growth and a stable core net interest margin. We maintained expense discipline alongside increased hiring efforts, were active in buybacks, and reduced our levels of criticized and nonperforming loans. We believe our team is well-positioned to build upon our year-to-date success as we grow customer relationships and hire talent throughout our footprint,” remarked Kevin D. Chapman, President and Chief Executive Officer of the Company.
Revenue growth
Net interest income and fee-based revenue are the two pillars supporting bank earnings. The former captures profit from the gap between lending rates and deposit costs, while the latter encompasses charges for banking services, credit products, wealth management and trading activities. Over the last five years, Renasant grew its revenue at a decent 10.8% compounded annual growth rate. Its growth was slightly above the average banking company and shows its offerings resonate with customers.
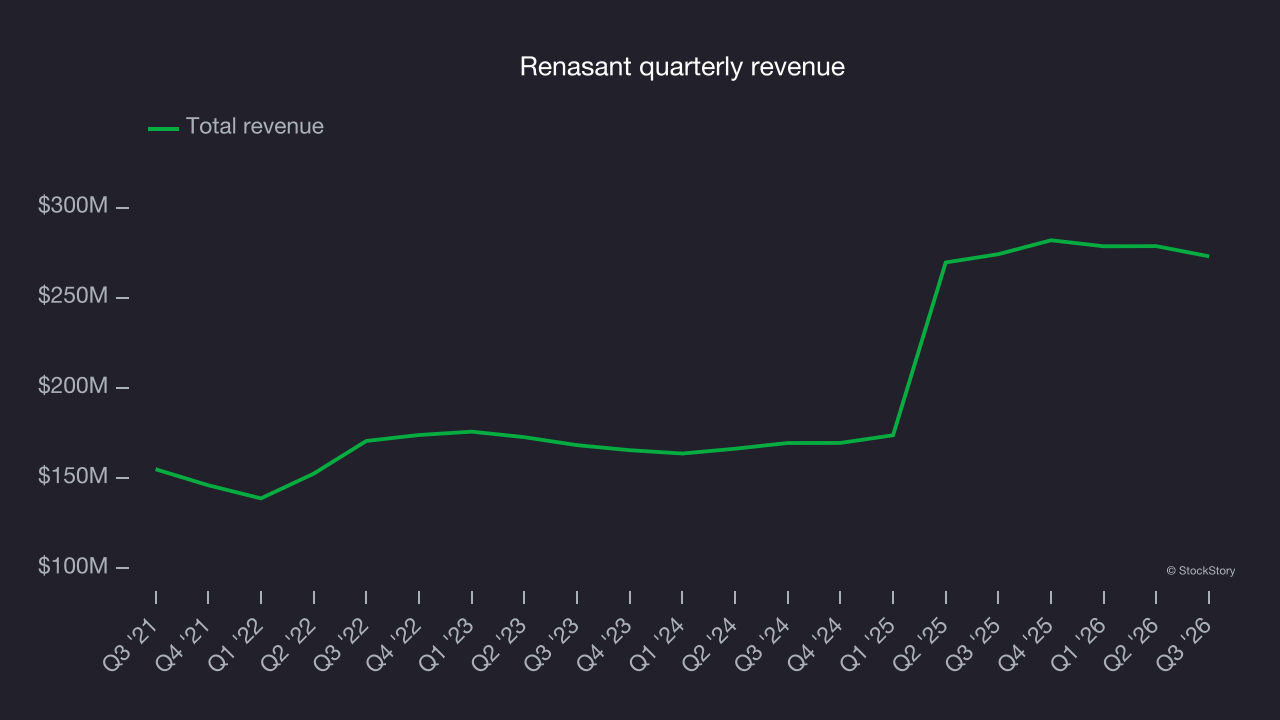
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Renasant’s annualized revenue growth of 29.3% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 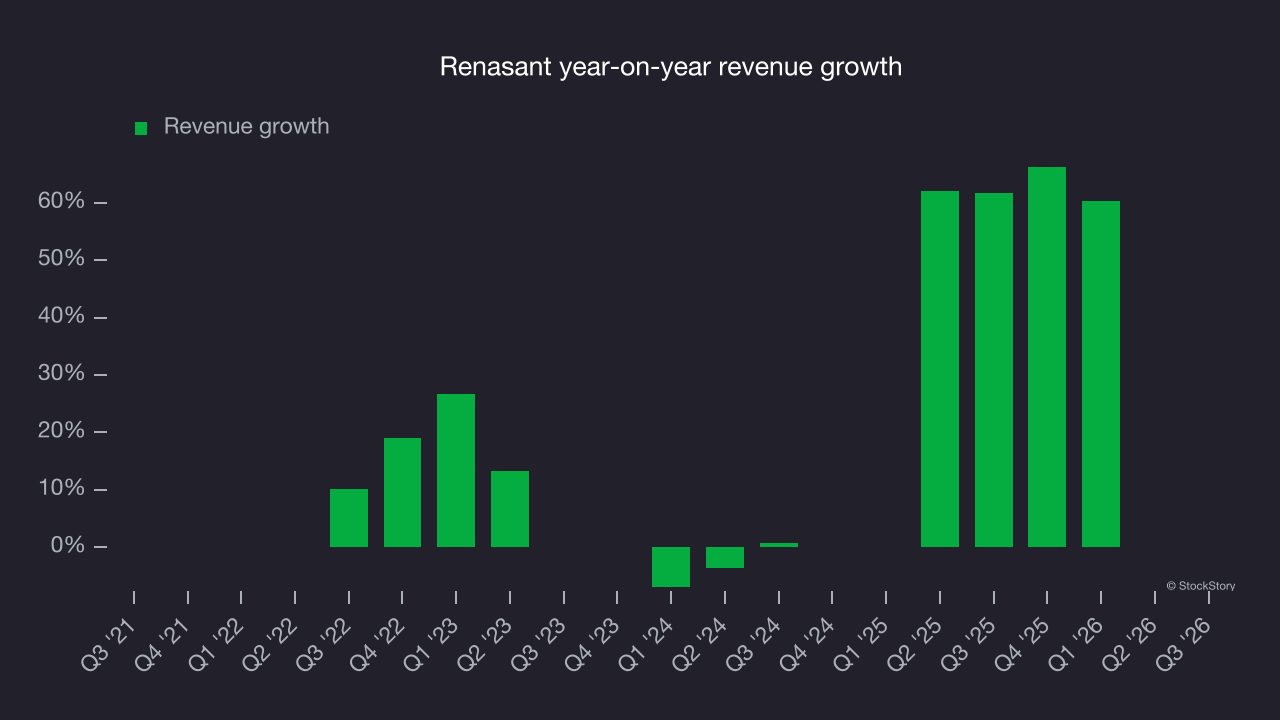 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Renasant’s $273 million of revenue was flat year on year, falling short of Wall Street’s consensus estimates.
Net interest income made up 77.2% of the company’s total revenue during the last five years, meaning lending operations are Renasant’s largest source of revenue.
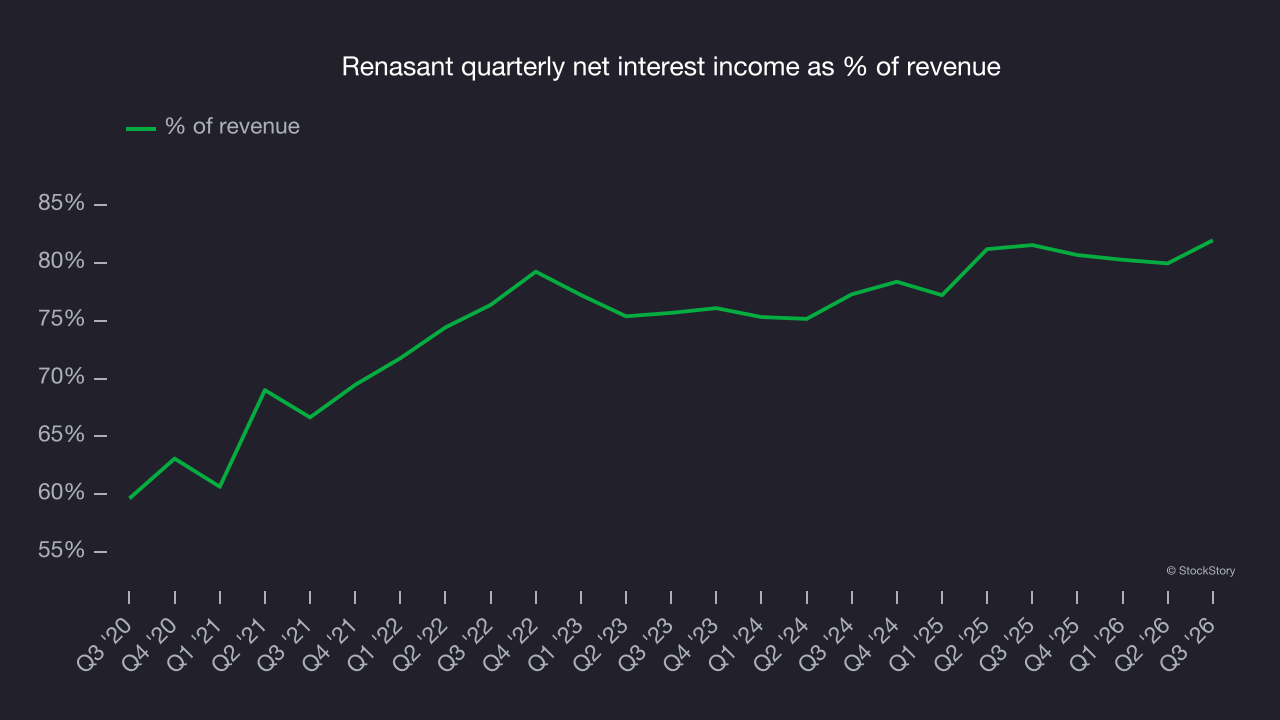
Markets consistently prioritize net interest income growth over fee-based revenue, recognizing its superior quality and recurring nature compared to the more unpredictable non-interest income streams.
Tangible book value per share (TBVPS)
The balance sheet drives banking profitability since earnings flow from the spread between borrowing and lending rates. As such, valuations for these companies concentrate on capital strength and sustainable equity accumulation potential.
Because of this, tangible book value per share (TBVPS) is the critical performance benchmark. By excluding intangible assets with uncertain liquidation values, this metric captures real, liquid net worth per share. EPS can be clouded by acquisition impacts or accounting flexibility around loan provisions, and TBVPS resists manipulation through financial engineering.
Renasant’s TBVPS grew at a sluggish 2.6% annual rate over the last five years. On a two-year basis, however, the trend has reversed as TBVPS dropped by 1.4% annually ($26.02 to $25.29 per share).
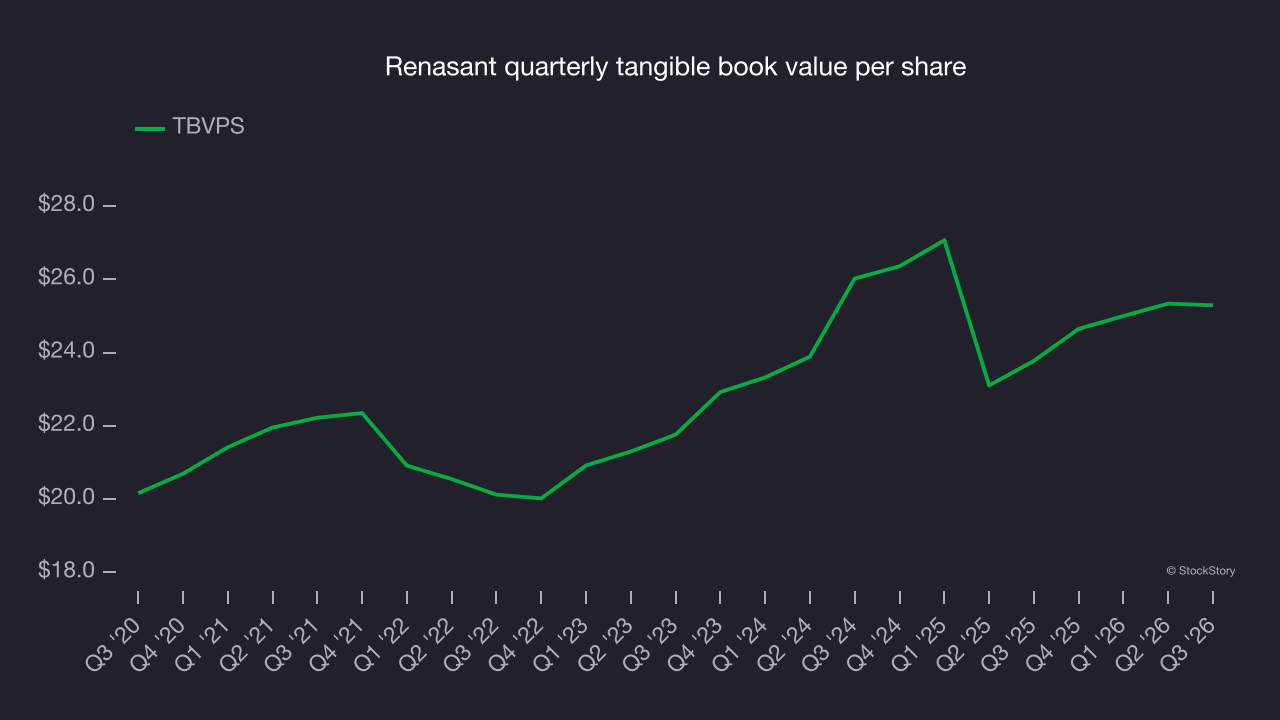
Over the next 12 months, consensus estimates call for Renasant’s TBVPS to grow by 13.3% to $28.65, a decent growth rate.
Key takeaways from Renasant’s Q3 results
Renasant’s revenue and net interest income both fell short of Wall Street’s consensus estimates, leaving few positives in a weaker quarter. Shares remained flat at $41.60 immediately after the report.
Renasant’s earnings report left more to be desired. To assess whether this quarter has created an opportunity to buy the stock, consider the latest results, but give more weight to longer-term business quality and valuation. For more on those factors, read the full research report here (it’s free).