

Beer company Boston Beer (NYSE: SAM) met Wall Street’s revenue expectations in Q3 2026, but sales fell by 3.2% year on year to $520.1 million. Its non-GAAP profit of $4.37 per share was 3.8% above analysts’ consensus estimates.
Is now the time to buy Boston Beer? Find out by accessing our full research report, it’s free.
Boston Beer (SAM) Q3 2026 highlights:
- Revenue: $520.1 million vs analyst estimates of $520.9 million (3.2% year-on-year decline, in line)
- Adjusted EPS: $4.37 vs analyst estimates of $4.21 (3.8% beat)
- Management raised its full-year Adjusted EPS guidance to $9.75 at the midpoint, a 2.6% increase
- Operating Margin: 10.8%, in line with the same quarter last year
- Free Cash Flow Margin: 13.1%, down from 16.6% in the same quarter last year
- Market Capitalization: $1.83 billion
“The demand environment remains challenging, and we are prioritizing actions within our control to strengthen our business and improve market share trends,” said Chairman, Founder and CEO Jim Koch. “We are encouraged by the strong performance of Sun Cruiser and remain focused on marketplace execution, while our continued emphasis on productivity and strong cash generation provide a solid foundation to invest behind our brands and drive long-term value.”
Company overview
Known for its flavorful beverages challenging the status quo, Boston Beer (NYSE: SAM) is a pioneer in craft brewing and a symbol of American innovation in the alcoholic beverage industry.
Revenue growth
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years.
With $1.91 billion in revenue over the past 12 months, Boston Beer is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers.
As you can see below, Boston Beer’s revenue declined by 2.6% per year over the last three years, a rough starting point for our analysis.
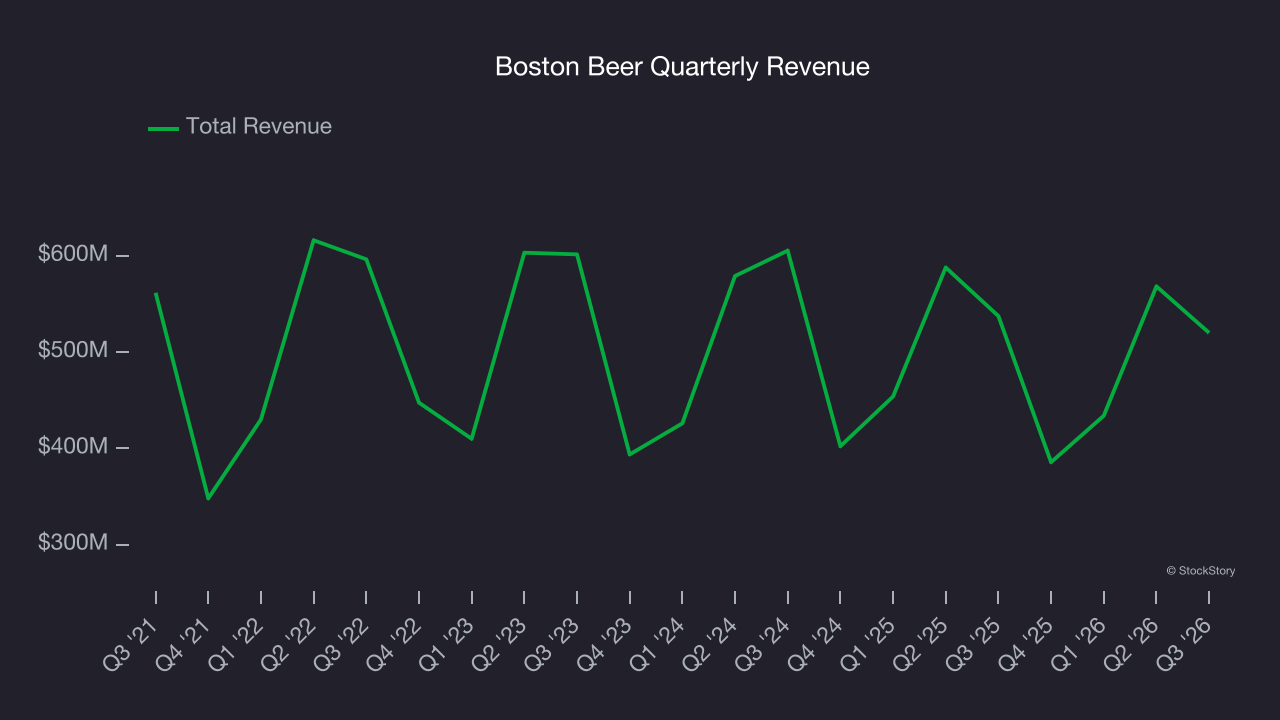
This quarter, Boston Beer reported a rather uninspiring 3.2% year-on-year revenue decline to $520.1 million of revenue, in line with Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months. Although this projection indicates its newer products will catalyze better top-line performance, it is still below the sector average.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Cash is king
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Boston Beer has shown robust cash profitability, driven by its attractive business model that enables it to reinvest or return capital to investors. The company’s free cash flow margin averaged 10.2% over the last two years, quite impressive for a consumer staples business. The divergence from its underwhelming operating margin stems from the add-back of non-cash charges like depreciation and stock-based compensation. GAAP operating profit expenses these line items, but free cash flow does not.
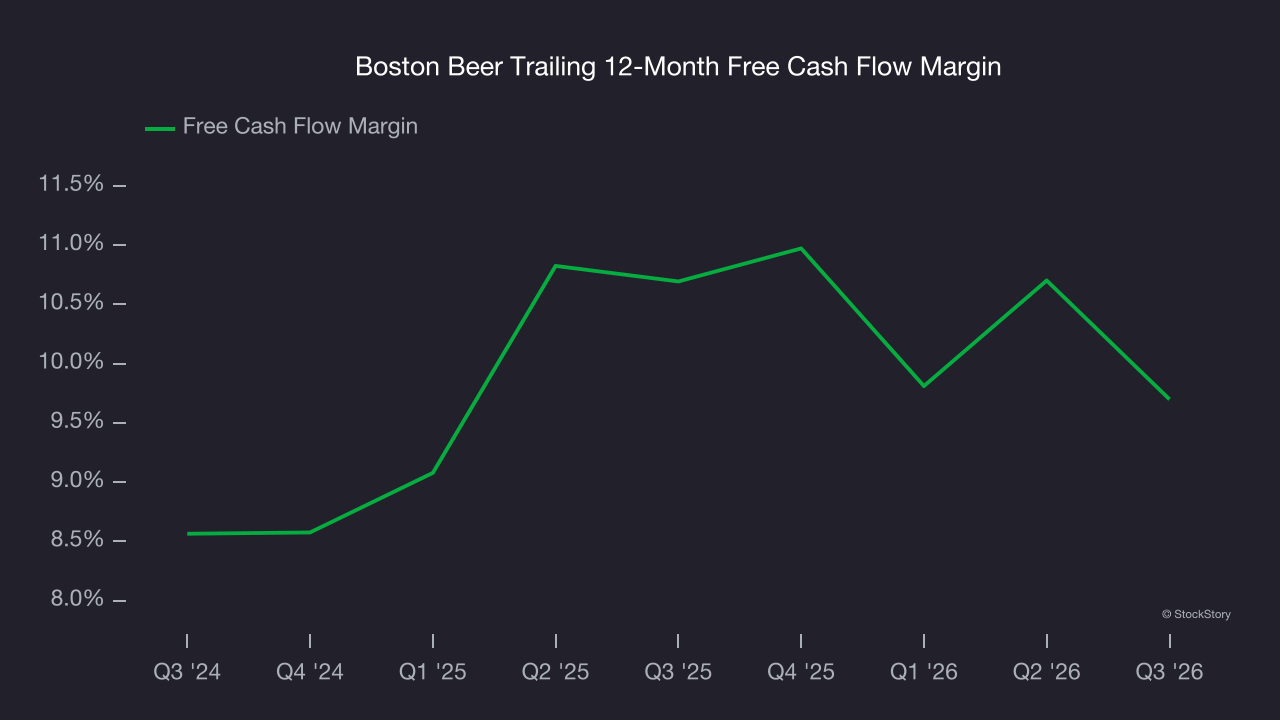
Boston Beer’s free cash flow clocked in at $68.26 million in Q3, equivalent to a 13.1% margin. The company’s cash profitability regressed as it was 3.5 percentage points lower than in the same quarter last year, but it’s still above its two-year average. We wouldn’t read too much into this quarter’s decline because investment needs can be seasonal, leading to short-term swings. Long-term trends are more important.
Key takeaways from Boston Beer’s Q3 results
It was great to see Boston Beer’s full-year EPS guidance top analysts’ expectations. We were also happy its gross margin narrowly outperformed Wall Street’s estimates. Overall, we think this was still a solid quarter with some key areas of upside. The market seemed to be hoping for more, and the stock traded down 1.8% to $192.50 immediately following the results.
So do we think Boston Beer is an attractive buy at the current price? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).