

Digital banking company Ally Financial (NYSE: ALLY) reported Q3 2026 results beating Wall Street’s revenue expectations, with sales up 8.1% year on year to $2.33 billion. Its non-GAAP profit of $1.34 per share was in line with analysts’ consensus estimates.
Is now the time to buy Ally Financial? Find out by accessing our full research report, it’s free.
Ally Financial (ALLY) Q3 2026 Highlights:
- Net Interest Margin: 3.6% vs analyst estimates of 3.6% (in line)
- Revenue: $2.33 billion vs analyst estimates of $2.30 billion (8.1% year-on-year growth, 1.3% beat)
- Efficiency Ratio: 45.7% vs analyst estimates of 55.2% (947.8 basis point beat)
- Adjusted EPS: $1.34 vs analyst estimates of $1.33 (in line)
- Tangible Book Value per Share: $41 vs analyst estimates of $43.75 (flat year on year, 6.3% miss)
- Market Capitalization: $11.32 billion
Company Overview
Born from the former GMAC (General Motors Acceptance Corporation) and rebranded in 2010, Ally Financial (NYSE: ALLY) operates a digital-first bank offering auto financing, insurance, mortgage lending, and investment services to consumers and commercial clients.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Unfortunately, Ally Financial’s 2.1% annualized revenue growth over the last five years was sluggish. This was below our standards and is a tough starting point for our analysis.
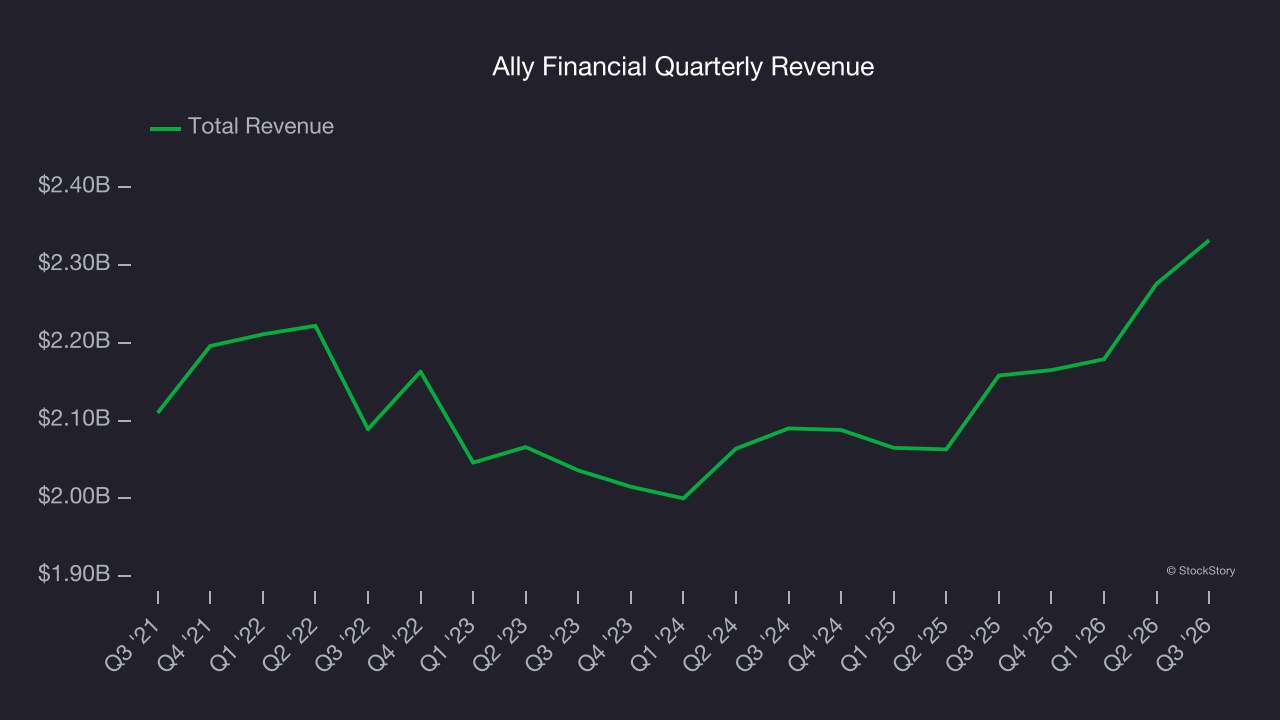
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. Ally Financial’s annualized revenue growth of 4.7% over the last two years is above its five-year trend, which is encouraging. 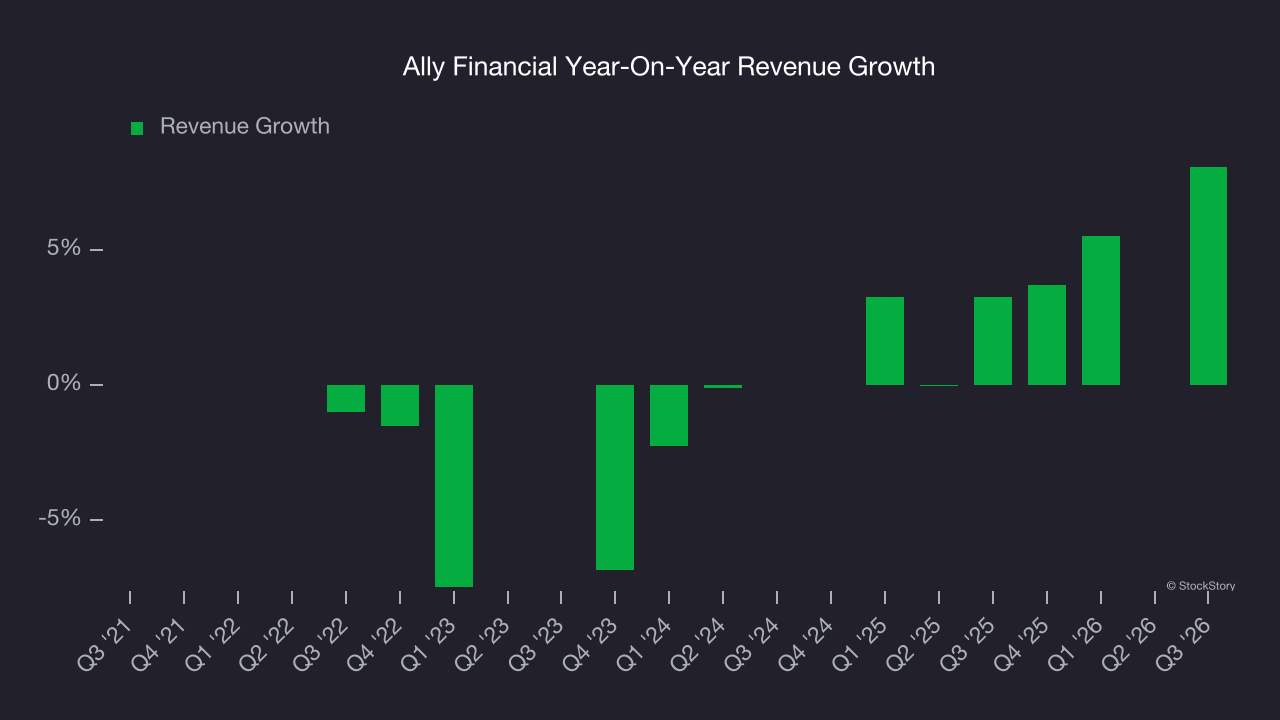 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Ally Financial reported year-on-year revenue growth of 8.1%, and its $2.33 billion of revenue exceeded Wall Street’s estimates by 1.3%.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Tangible Book Value Per Share (TBVPS)
Diversified financial companies operate across multiple business segments, from investment banking and trading to wealth management and specialized lending. Their valuations hinge on balance sheet quality and the ability to compound shareholder equity across these diverse operations.
When analyzing this sector, tangible book value per share (TBVPS) takes precedence over many other metrics. This measure isolates genuine per-share value and provides insight into the institution’s capital position across diverse operations. Other (and more commonly known) per-share metrics like EPS can sometimes be murky due to the complexity of multiple business lines, M&A activity, or accounting rules that vary across different financial services segments.
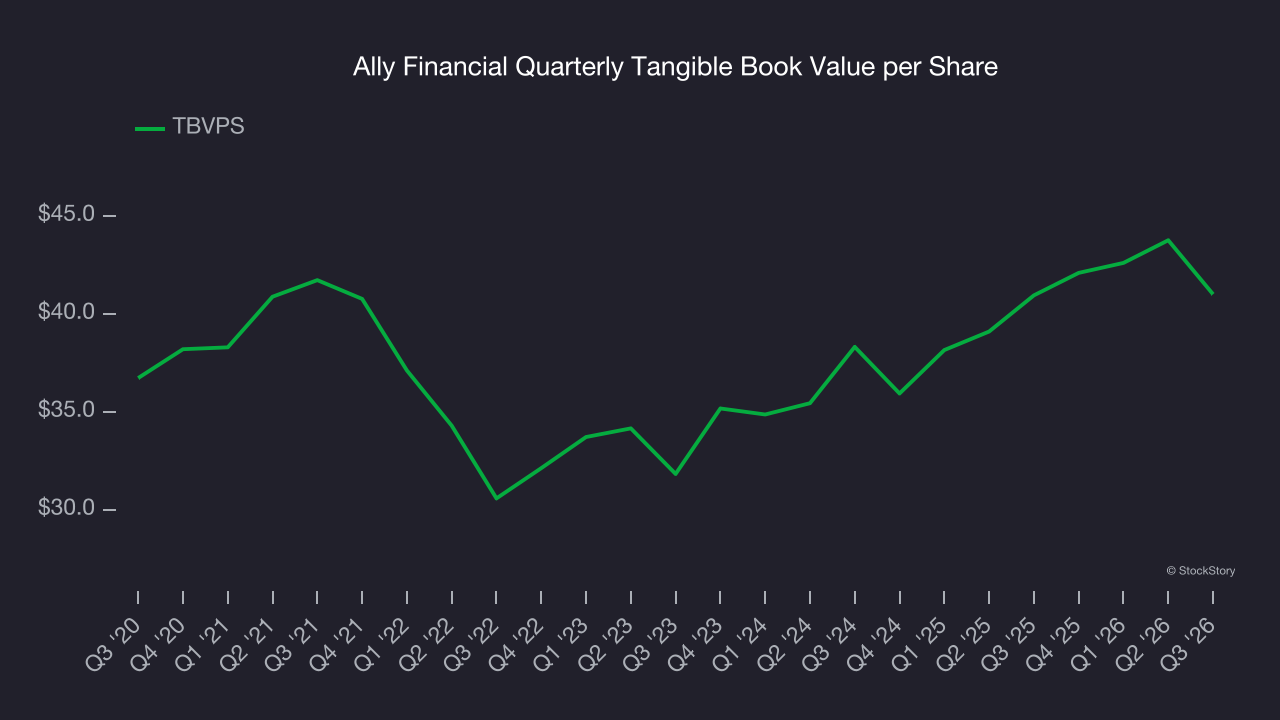
Ally Financial’s TBVPS was flat over the last five years. However, TBVPS growth has accelerated recently, growing by 3.4% annually over the last two years from $38.31 to $41 per share.
Tangible Book Value Per Share (TBVPS)
Financial firms profit by providing a wide range of services, making them fundamentally balance sheet-driven enterprises with multiple intermediation roles. Market participants emphasize balance sheet quality and sustained book value growth when evaluating these multifaceted institutions.
This explains why tangible book value per share (TBVPS) is a premier metric for the sector. TBVPS provides concrete per-share net worth that investors can trust when evaluating companies with complex, multi-faceted business models. Traditional metrics like EPS are helpful but face distortion from the complexity of diversified operations, M&A activity, and various accounting rules that can obscure true performance across multiple business lines.
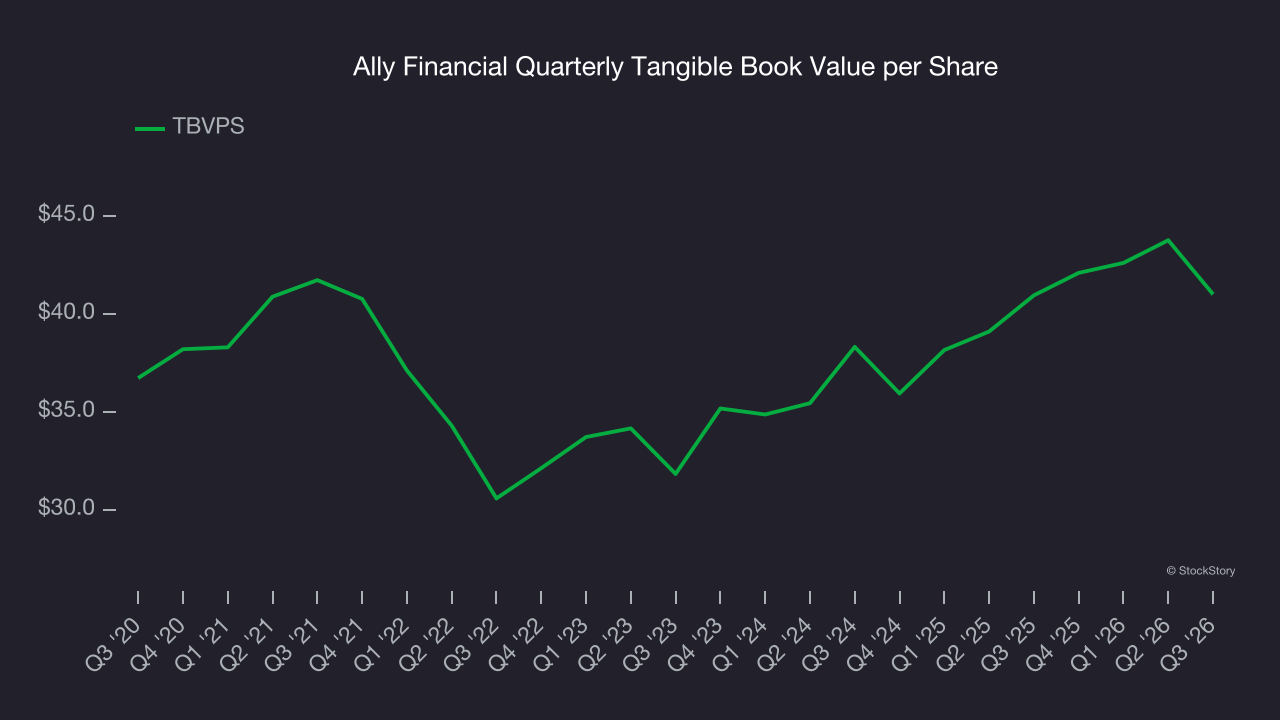
Ally Financial’s TBVPS was flat over the last five years. However, TBVPS growth has accelerated recently, growing by 3.4% annually over the last two years from $38.31 to $41 per share.
Key Takeaways from Ally Financial’s Q3 Results
It was good to see Ally Financial meet analysts’ net interest margin expectations this quarter. We were also happy its revenue narrowly outperformed Wall Street’s estimates. On the other hand, its efficiency ratio missed. Overall, this print had some key positives. The stock remained flat at $37.58 immediately after reporting.
Is Ally Financial an attractive investment opportunity right now? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).