

What a fantastic six months it’s been for H&R Block. Shares of the company have skyrocketed 47.2%, hitting $46.68. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in H&R Block, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think H&R Block Will Underperform?
We’re happy investors have made money, but we’re passing on H&R Block for now. Here are three reasons why there are better opportunities than HRB, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
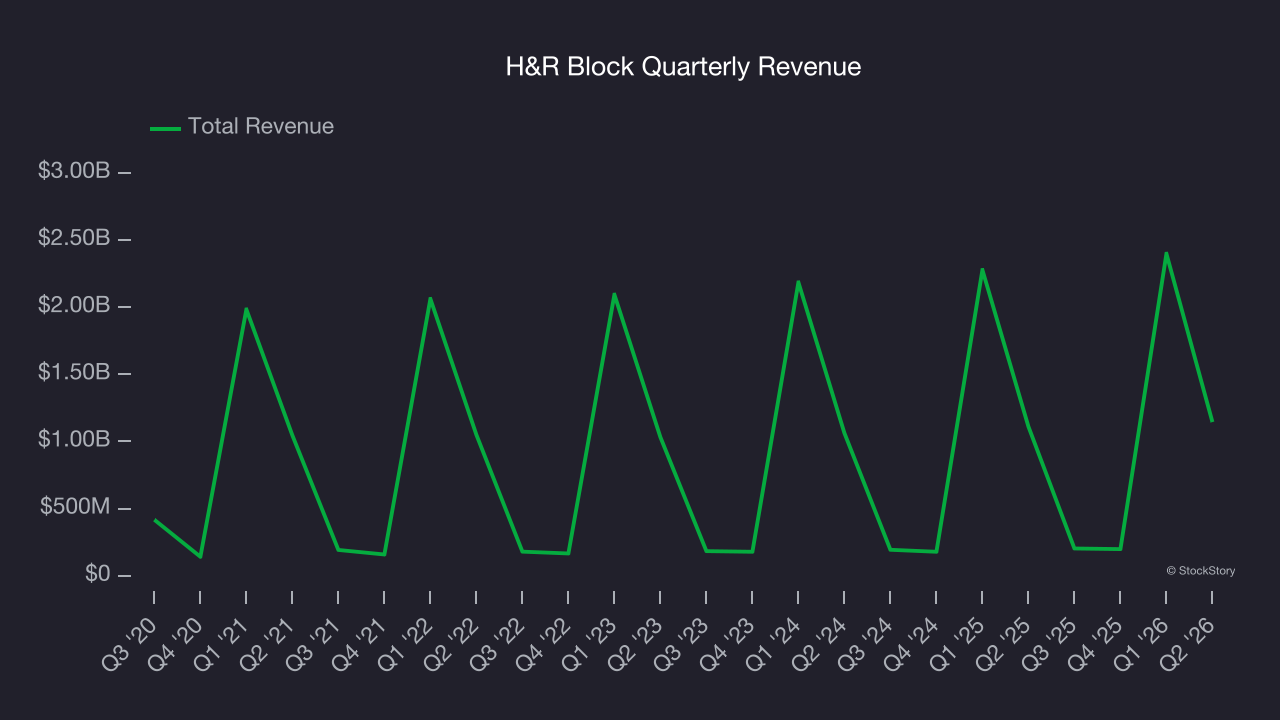
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, H&R Block grew its sales at a weak 1.9% compounded annual growth rate. This fell short of our benchmarks. We note H&R Block is a seasonal business because it generates most of its revenue during tax season, so the charts in our report will look a bit lumpy.
2. EPS Barely Growing
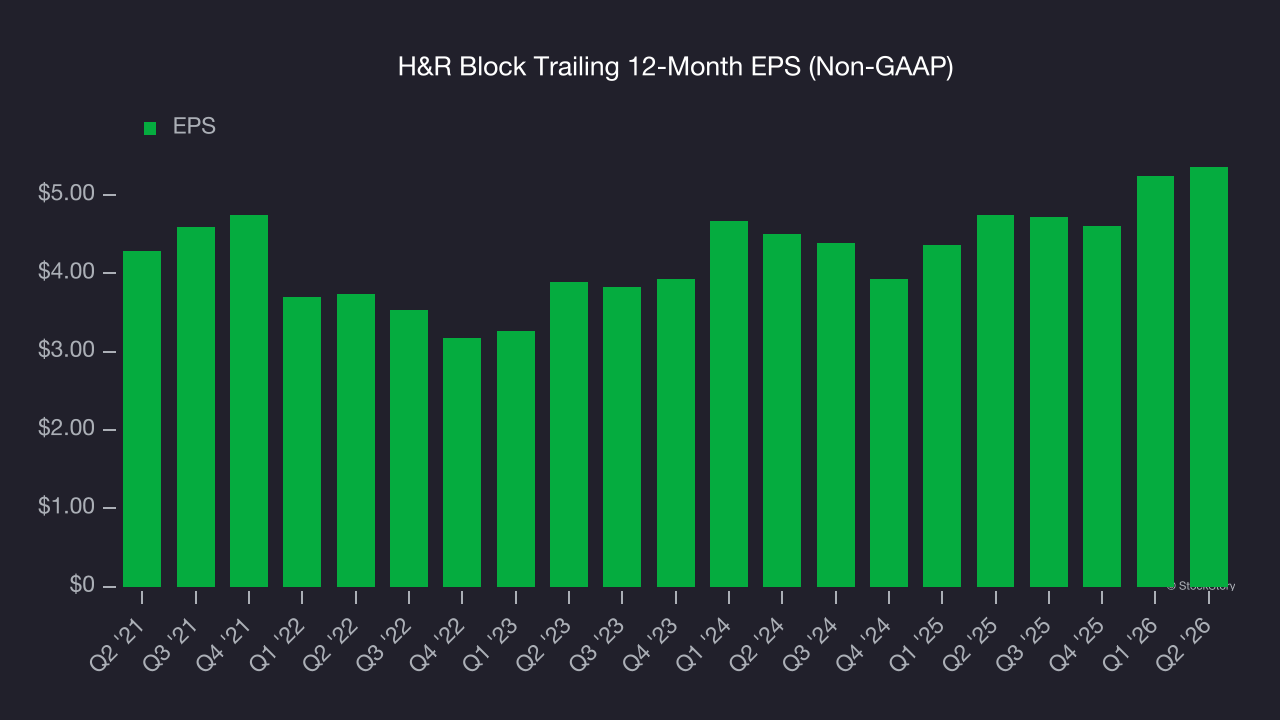
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
H&R Block’s EPS grew at 4.6% compounded annual growth rate over the last five years. On the bright side, this performance was better than its 1.9% annualized revenue growth and tells us the company became more profitable on a per-share basis as it expanded.
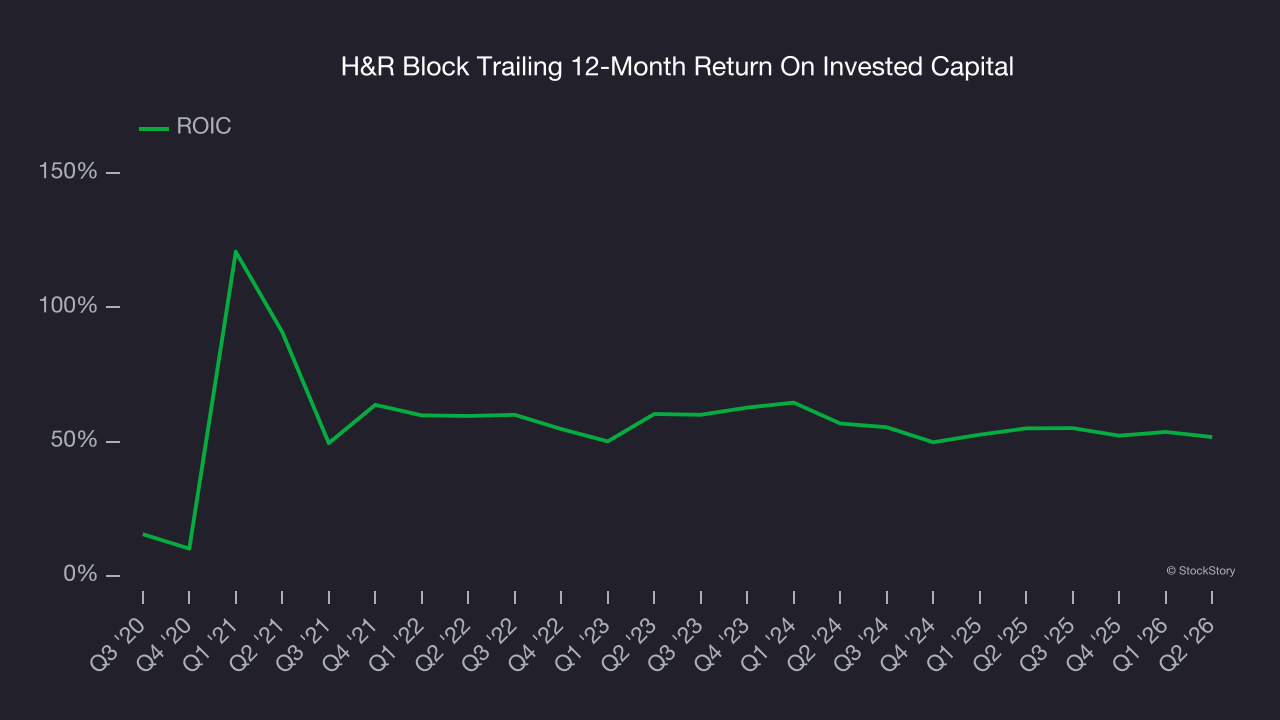
3. New Investments Fail to Bear Fruit as ROIC Declines
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Unfortunately, H&R Block’s ROIC has decreased over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
We see the value of companies helping consumers, but in the case of H&R Block, we’re out. After the recent surge, the stock trades at 7.8× forward P/E (or $46.68 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better investments elsewhere. We’d suggest looking at a top digital advertising platform riding the creator economy.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.