

Even though LSI (currently trading at $20.29 per share) has gained 6.1% over the last six months, it has lagged the S&P 500’s 14% return during that period. This may have investors wondering how to approach the situation.
Taking into account the weaker price action, does LYTS warrant a spot on your radar, or is it better left off your list? Find out in our full research report, it’s free.
Why Is LYTS a Good Business?
Enhancing commercial environments, LSI (NASDAQ: LYTS) provides lighting and display solutions for businesses and retailers.
1. Skyrocketing Revenue Shows Strong Momentum
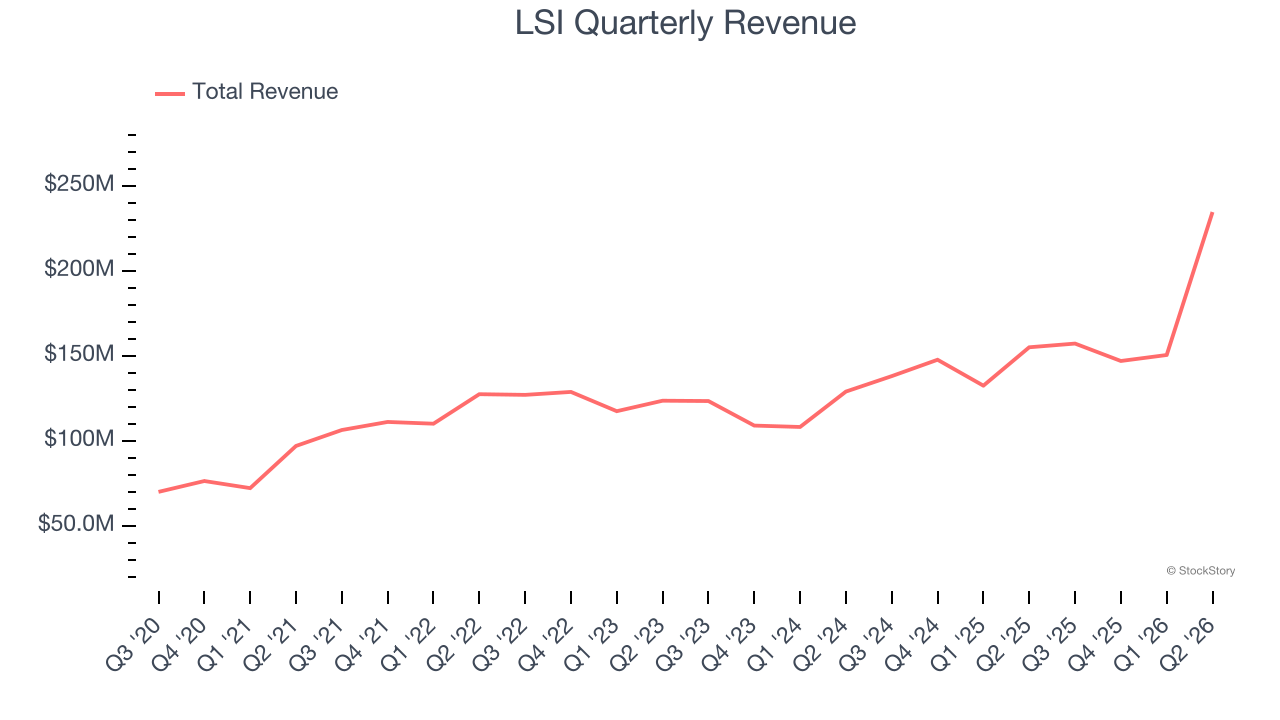
Reviewing a company’s long-term sales performance reveals insights into its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Over the last five years, LSI grew its sales at an incredible 16.9% compounded annual growth rate. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
2. Outstanding Long-Term EPS Growth
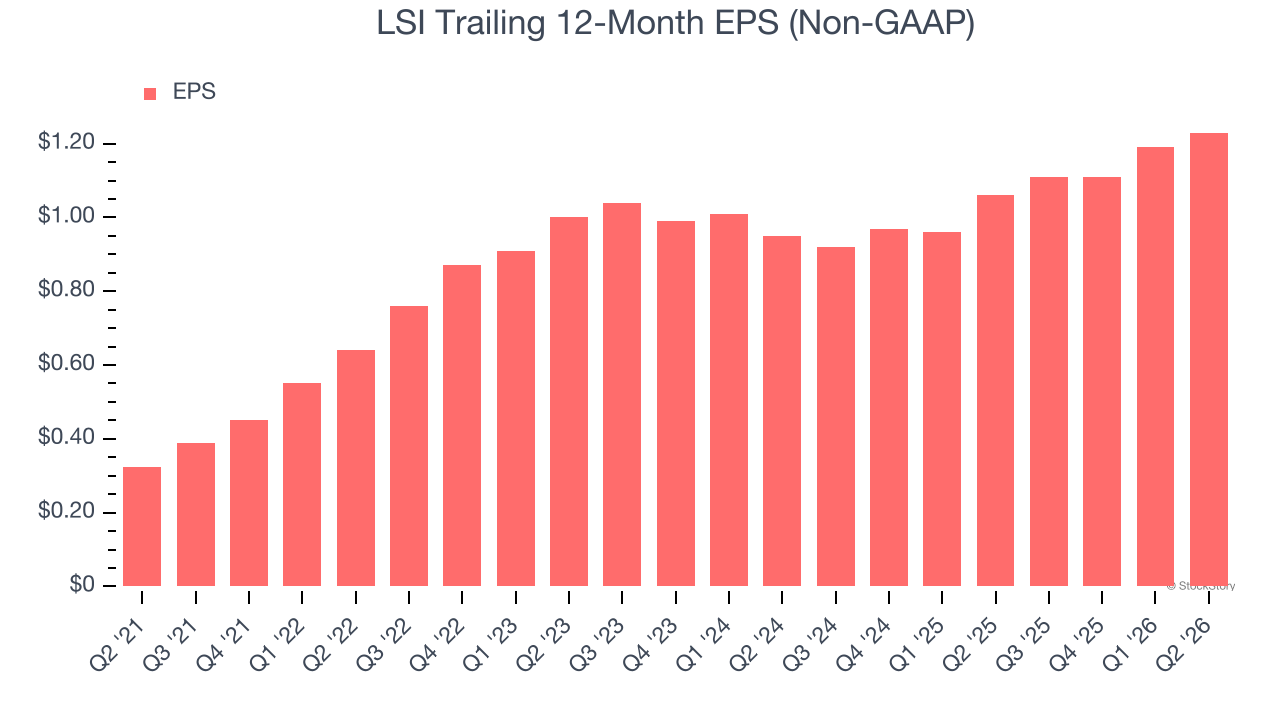
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
LSI’s EPS grew at 30.7% compounded annual growth rate over the last five years, higher than its 16.9% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
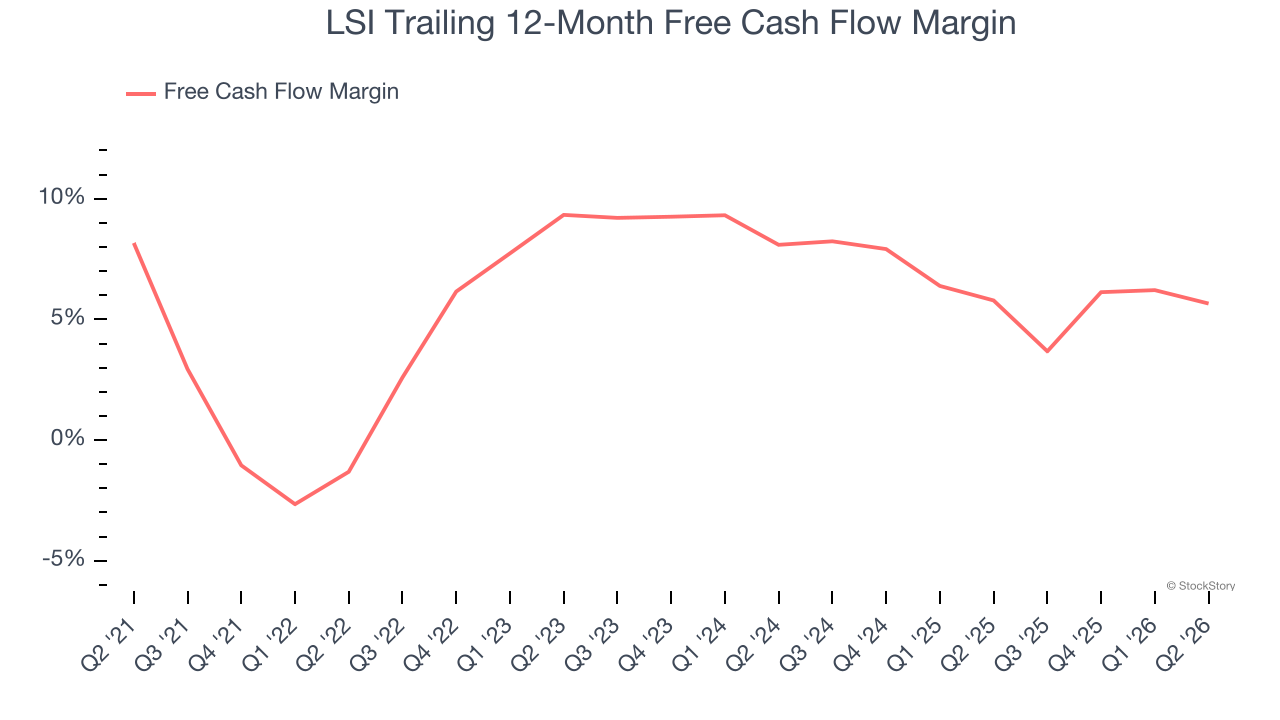
3. Increasing Free Cash Flow Margin Juices Financials
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
As you can see below, LSI’s margin expanded by 7 percentage points over the last five years. The company’s improvement shows it’s heading in the right direction, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. LSI’s free cash flow margin for the trailing 12 months was 5.7%.
Final Judgment
These are just a few reasons LSI is a high-quality business worth owning. With its shares underperforming the market lately, the stock trades at 15.1× forward P/E (or $20.29 per share). Is now a good time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than LSI
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.