Resideo has gotten torched over the last six months - since May 2026, its stock price has dropped 51.3% to $19.21 per share. This was partly due to its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy Resideo, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why do we think Resideo will underperform?
Even with the cheaper entry price, we’re sitting this one out for now. Here are three reasons why there are better opportunities than REZI, plus one stock we’d rather own.
1. Long-term revenue growth disappoints
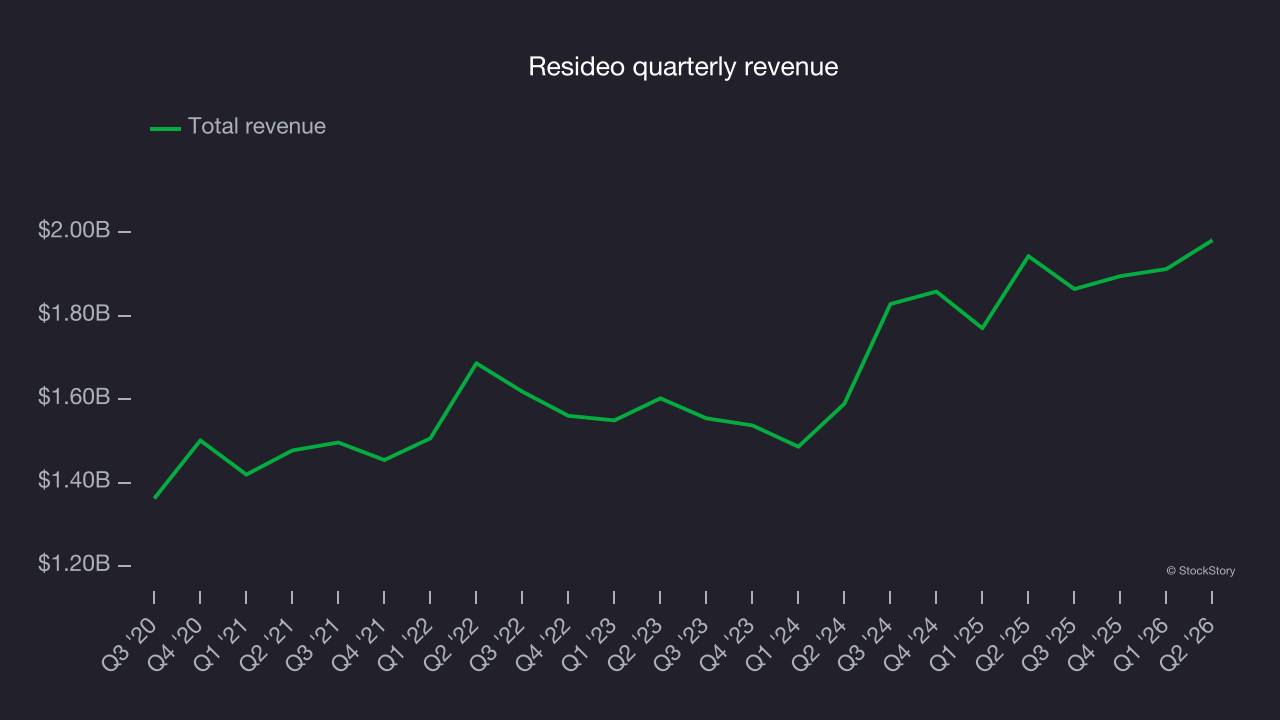
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Resideo grew its sales at a tepid 5.8% compounded annual growth rate. This was below our standard for the industrials sector.
2. Free cash flow margin dropping
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
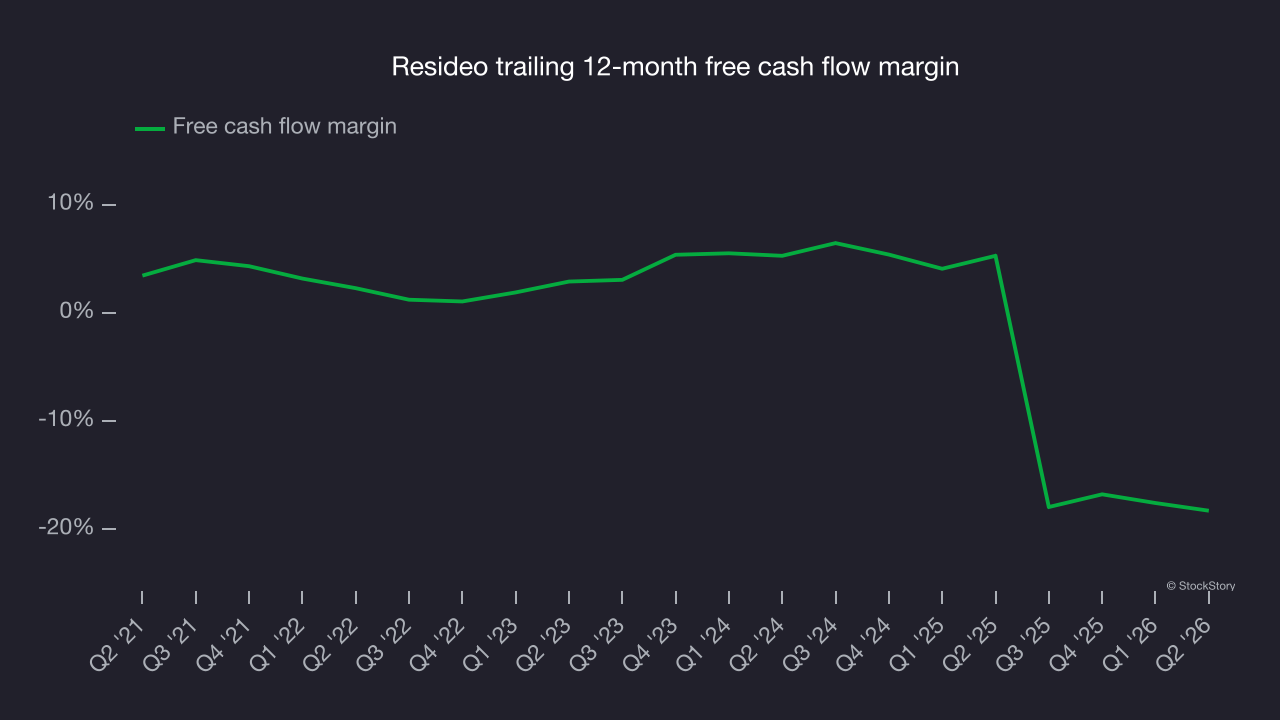
As you can see below, Resideo’s margin dropped by 20.6 percentage points over the last five years. Almost any movement in the wrong direction is undesirable because it is already burning cash. If the trend continues, it could signal it’s becoming a more capital-intensive business. Resideo’s free cash flow margin for the trailing 12 months was negative 18.3%.
3. New investments fail to bear fruit as ROIC declines
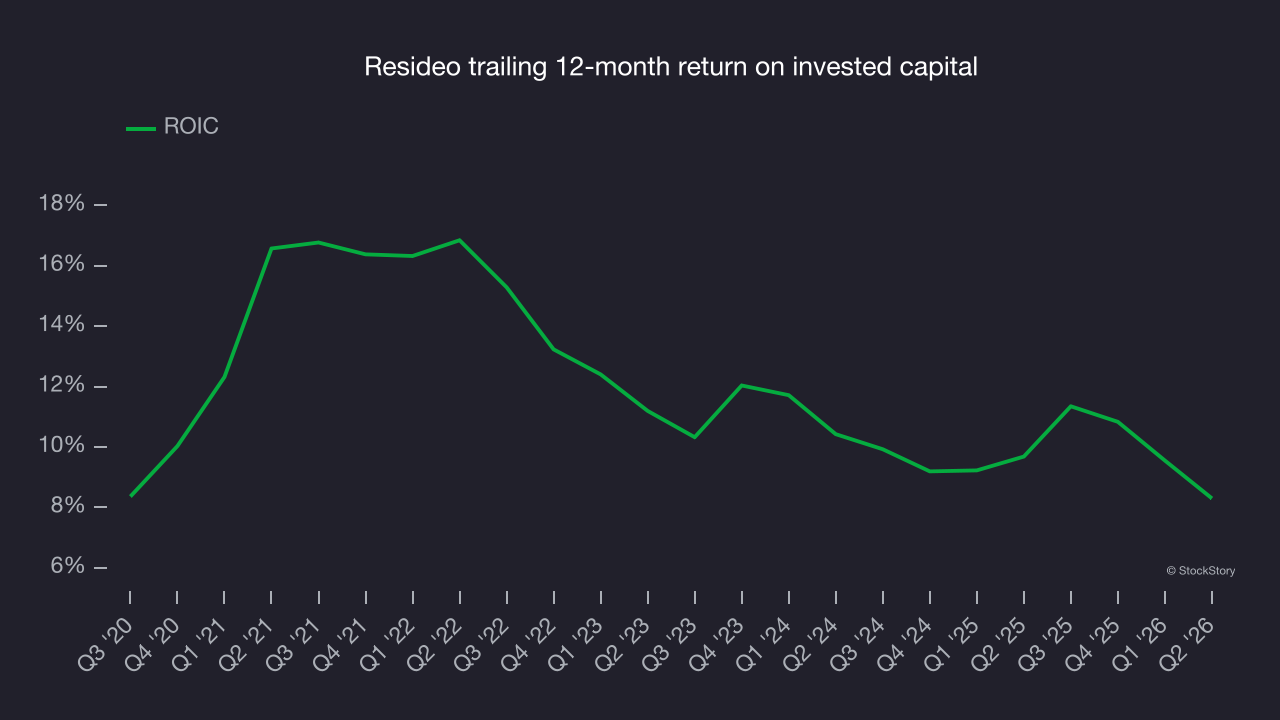
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Over the last few years, Resideo’s ROIC has unfortunately decreased. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final judgment
Resideo doesn’t pass our quality test. Following the recent decline, the stock trades at 10.3× forward P/E (or $19.21 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. There are more exciting stocks to buy at the moment. Let us point you toward a dominant aerospace business that has perfected its M&A strategy.
High-quality stocks for all market conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.