Packaging manufacturer Ball (NYSE: BALL) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 23.9% year on year to $4.19 billion. Its non-GAAP profit of $1.10 per share was 2.9% above analysts’ consensus estimates.
For more on Ball, read our free full research report.
Ball (BALL) Q3 2026 highlights:
- Revenue $4.19 billion vs S&P analysts’ consensus estimates of $3.76 billion (23.9% year-on-year growth, 11.4% beat)
- Adjusted EPS $1.10 vs S&P analysts’ consensus estimates of $1.07 (2.9% beat)
- Operating margin -1.8%, down from 13.9% in the same quarter last year
- Free cash flow margin 0.8%, down from 7.6% in the same quarter last year
- Market capitalization $18.02 billion
"Ball delivered another quarter of strong results, reflecting the power of our customer-focused strategy, disciplined execution and the ownership mindset embedded throughout our organization. In an operating environment that remains dynamic, our teams continued to execute at a high level, driving global volume and operating earnings growth. These results demonstrate the strength of the Ball Business System and our relentless focus on continuous improvement as we work to better serve customers and create long-term value for shareholders," said Ron Lewis, chief executive officer.
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Ball’s revenue grew at a sluggish 2.7% compounded annual growth rate over the last five years, falling short of our standards.
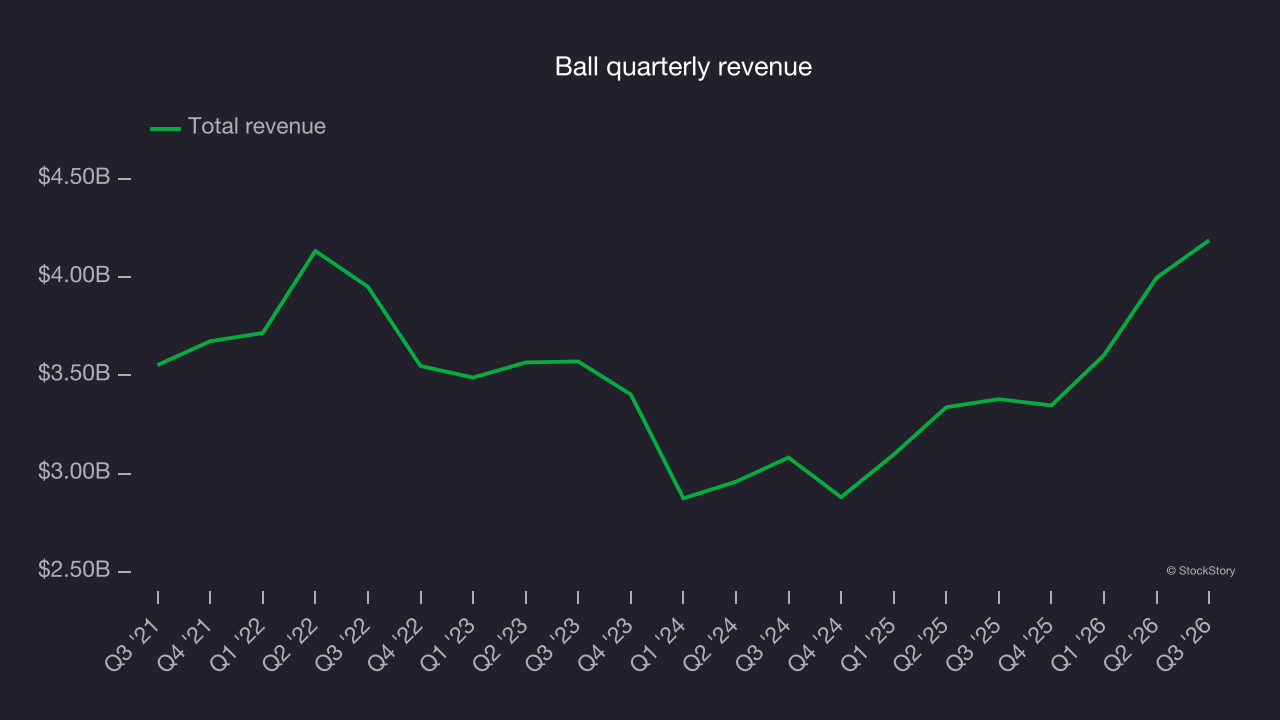
Long-term growth matters the most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Ball’s annualized revenue growth of 10.8% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 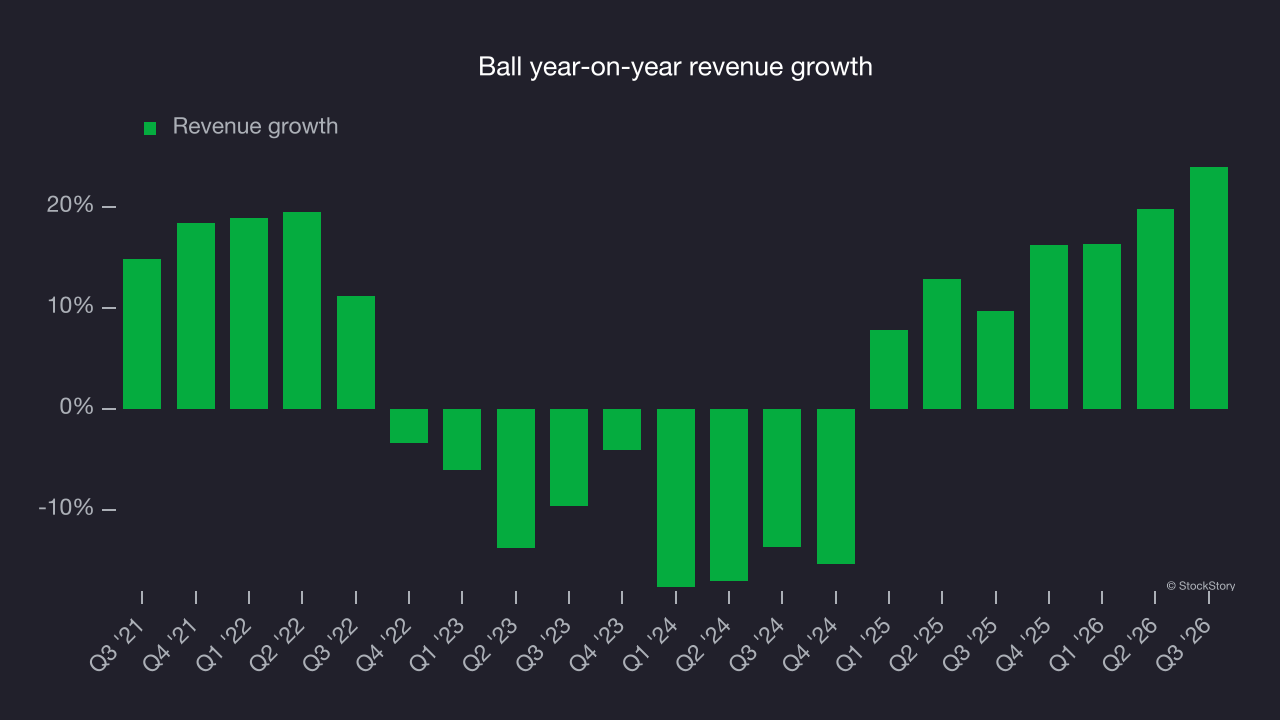
This quarter, Ball reported year-on-year revenue growth of 23.9%, and its $4.19 billion in revenue topped Wall Street’s consensus estimates by 11.4%.
Looking ahead, sell-side analysts expect revenue to grow 1.6% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and implies its products and services will face some demand challenges.
Operating margin
Ball has done a decent job managing its cost base over the last five years. The company has produced an average operating margin of 8.1%, higher than the broader industrials sector.
Analyzing the trend in its profitability, Ball’s operating margin decreased by 3 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
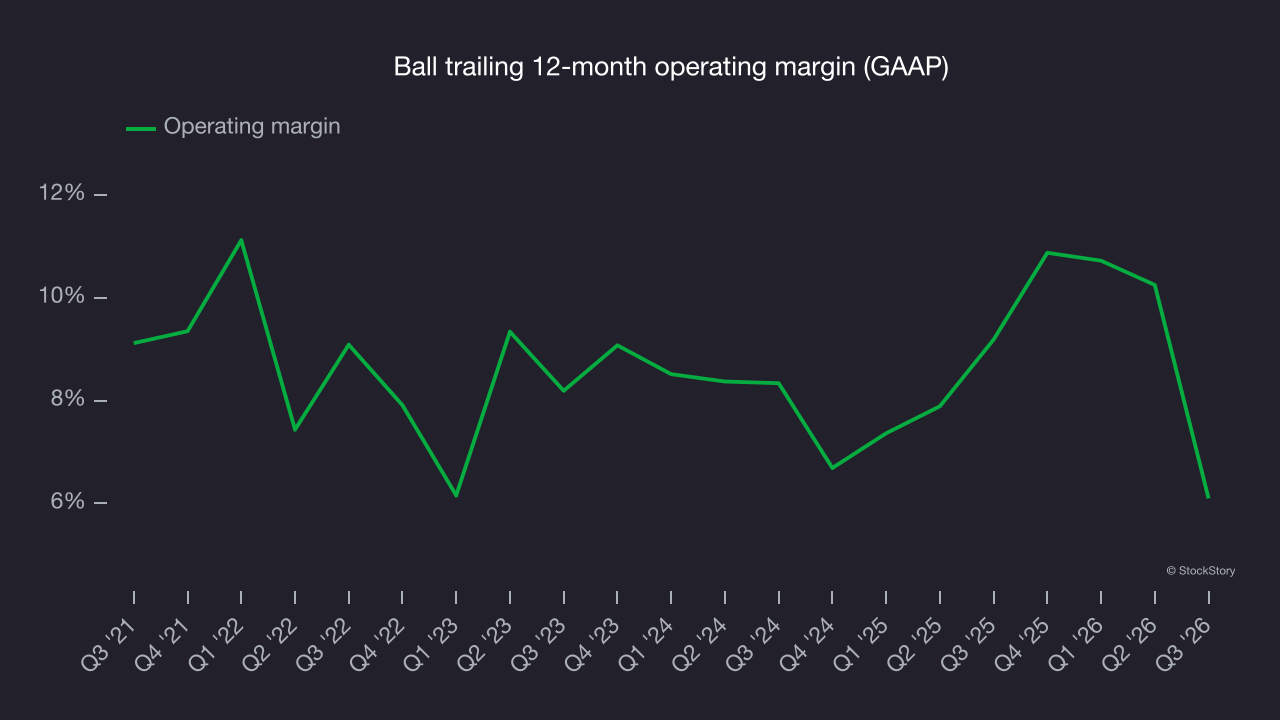
This quarter, Ball generated an operating margin of negative 1.8%, down 15.7 percentage points year on year. The larger decline in Ball’s operating margin relative to its gross margin suggests it was less efficient because expenses such as marketing, R&D and administrative overhead increased.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Ball’s weak 3.6% annual EPS growth over the last five years aligns with its revenue performance, indicating it maintained its per-share profitability as it expanded.
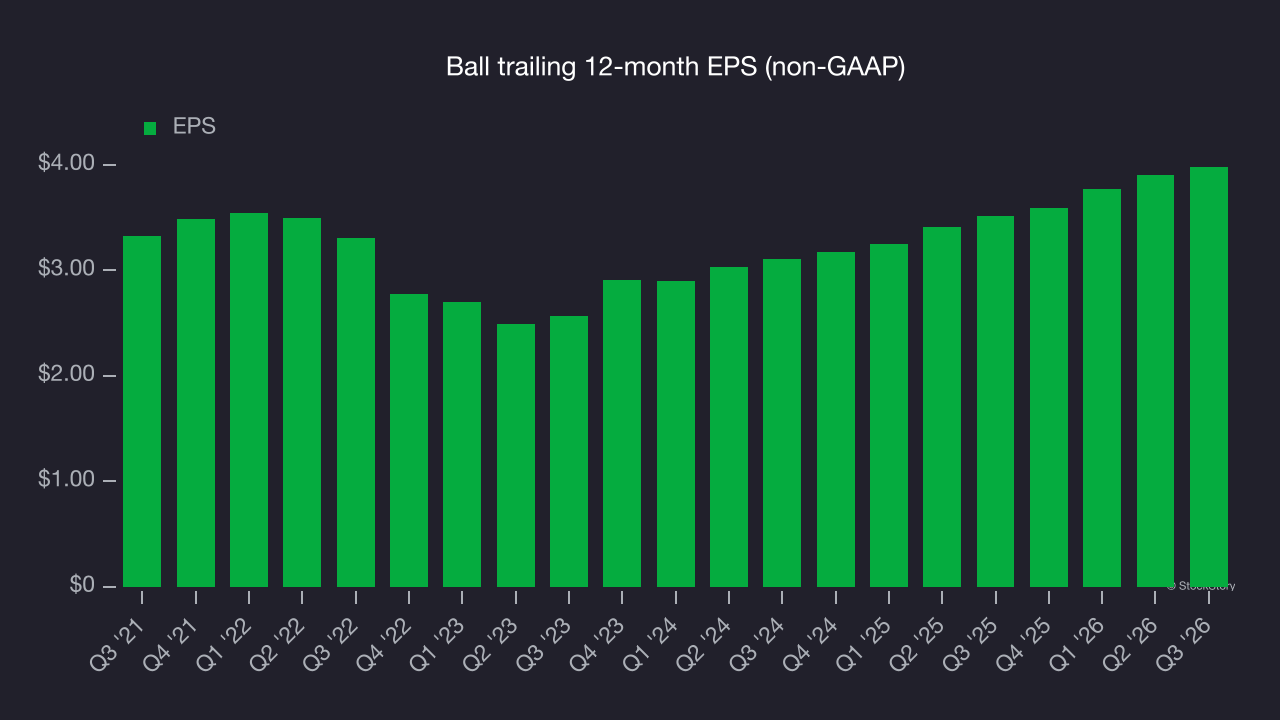
As with revenue, examining EPS over a shorter period helps identify changes in the business.
Ball’s two-year annual EPS growth of 13.1% was strong and topped its 10.8% two-year revenue growth.
A closer look at Ball’s earnings helps explain its performance. A two-year view shows that Ball has repurchased its stock, shrinking its share count by 13.6%. This indicates its EPS outperformed its revenue not because of increased operational efficiency but financial engineering, as buybacks boost per share earnings. 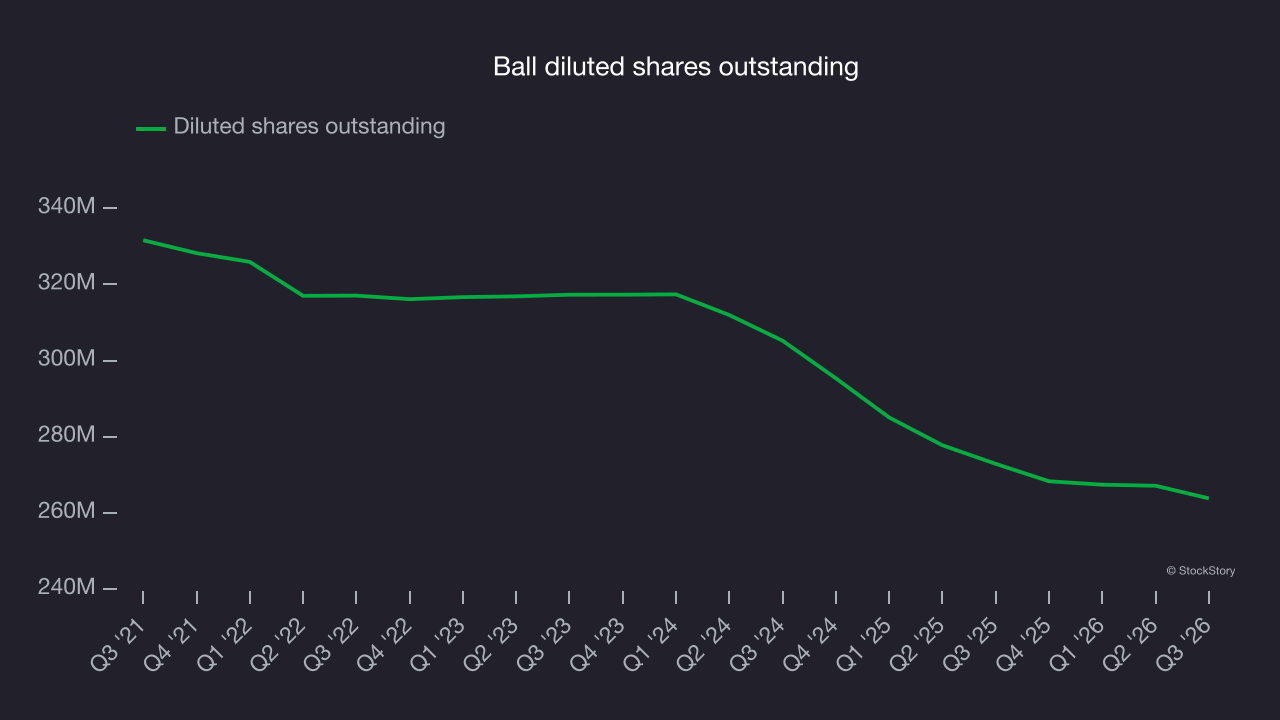
In Q3, Ball reported adjusted EPS of $1.10, up from $1.02 in the same quarter last year. The result beat analysts’ consensus estimates by 2.9%. Over the next 12 months, Wall Street expects Ball’s full-year EPS to grow 9.2% from $3.98 to $4.35, according to S&P.
Key takeaways from Ball’s Q3 results
Ball’s good quarter had two clear positives: revenue came in well ahead of analysts’ consensus estimates, and EPS also topped Wall Street’s expectations. But investors were likely hoping for more, with shares edging lower 1.8% to $66.85 immediately after the report.
To assess Ball as an investment, consider the bigger picture of valuation and business quality as well as the latest earnings. Read the full research report here for more on Ball (it’s free).