Global pharmaceutical company Merck (NYSE: MRK) announced better-than-expected revenue in Q3 2026, with revenue rising 4.7% year on year to $18.09 billion. The company expects the full year’s revenue to be around $67.05 billion, close to analysts’ consensus estimates. Its non-GAAP profit of $2.49 per share was 19.3% above analysts’ consensus estimates.
For more on Merck, read our free full research report.
Merck (MRK) Q3 2026 highlights:
- Revenue $18.09 billion vs S&P analysts’ consensus estimates of $17.31 billion (4.7% year-on-year growth, 4.5% beat)
- Adjusted EPS $2.49 vs S&P analysts’ consensus estimates of $2.09 (19.3% beat)
- Revenue guidance The company slightly lifted its revenue guidance for the full year to $67.05 billion at the midpoint from $66.8 billion
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $2.80 at the midpoint, a 3.1% increase
- Operating margin 30.7%, down from 37.7% in the same quarter last year
- Constant currency revenue rose 4% year on year, in line with the same quarter last year
- Market capitalization $347.7 billion
“Our science-led strategy is transforming our business,” said Robert M. Davis, chairman and chief executive officer. “The potentially practice-changing advances in oncology presented at last weekend’s ESMO meeting, including new data for our antibody-drug conjugate sac-TMT and the first Phase 3 validation of a therapeutic cancer vaccine, further clinically de-risk the substantial long-term opportunity of our late-phase pipeline. With positive momentum across multiple therapeutic areas, I’m increasingly confident in our ability to deliver long-term value for patients and shareholders.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last five years, Merck grew its revenue at a decent 7.9% compounded annual growth rate. Its growth was slightly above the average healthcare company and shows its offerings resonate with customers.
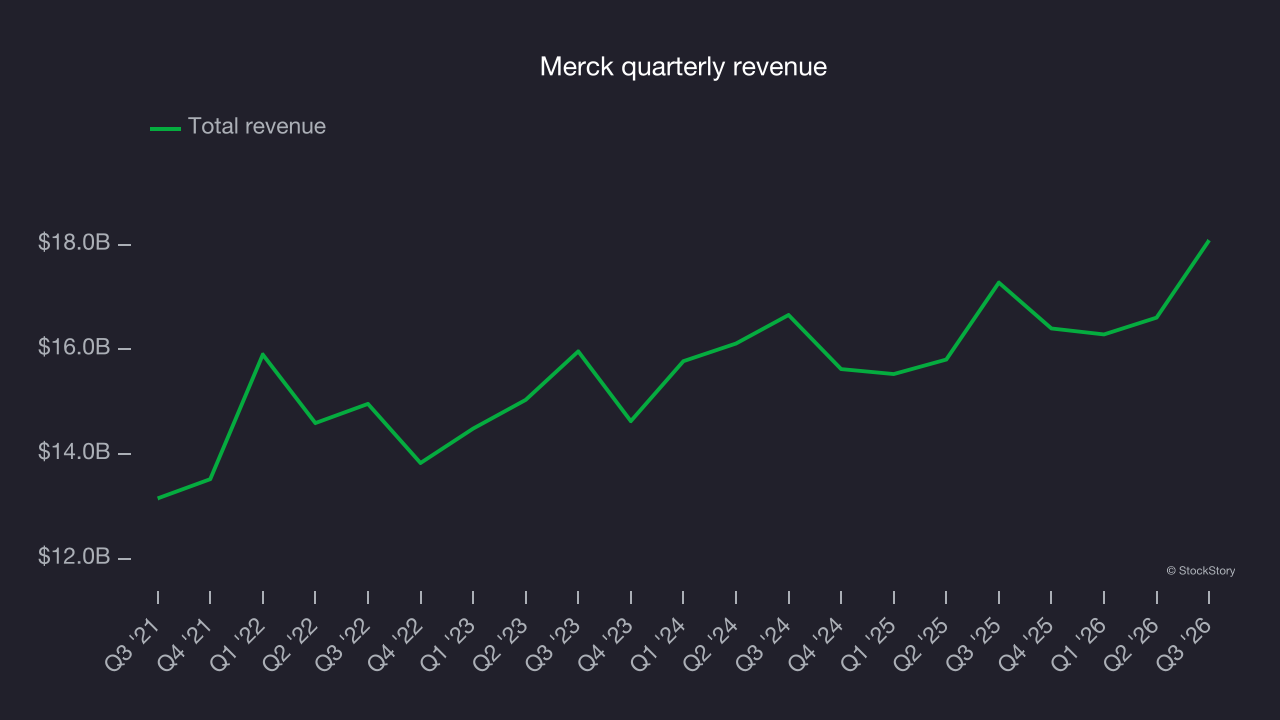
Long-term growth matters most, but within healthcare, a half-decade historical view may miss recent innovations or disruptive industry trends. Merck’s recent performance shows its demand has slowed as its annualized revenue growth of 3.3% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 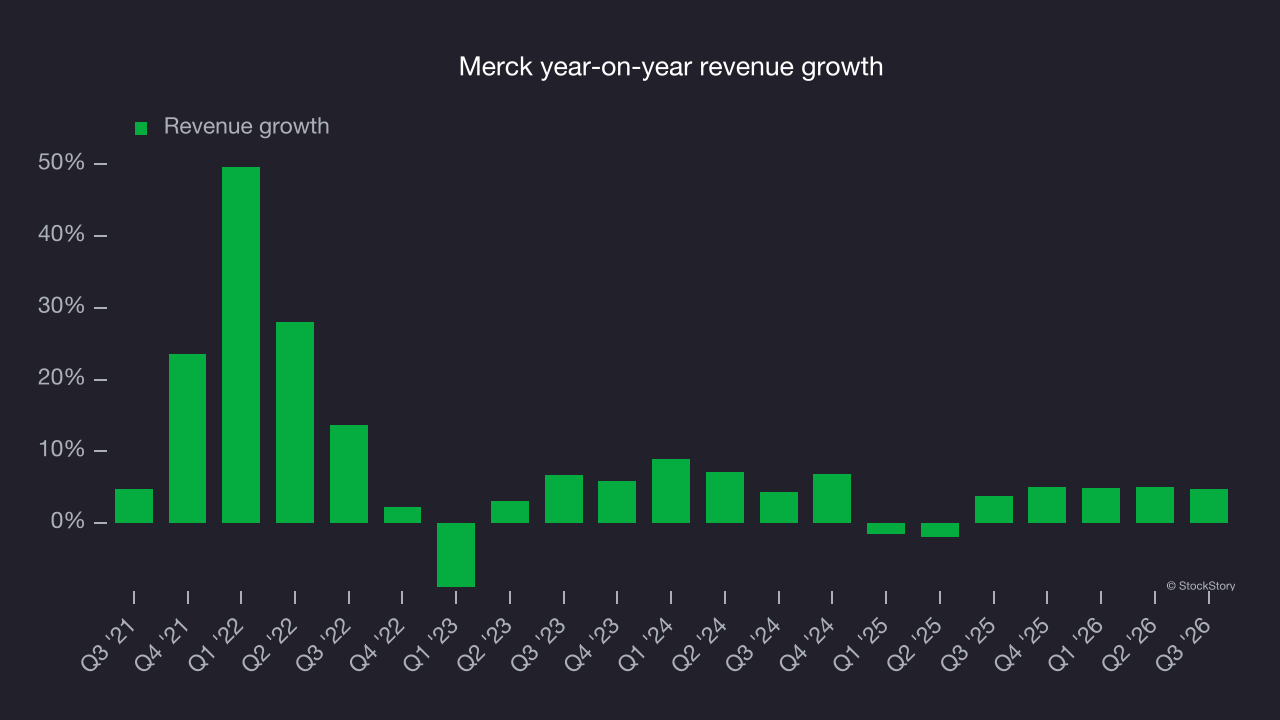
A closer look at the company’s revenue dynamics includes analyzing its constant currency revenue, which excludes currency movements that are outside its control and not indicative of demand. Over the last two years, its constant currency revenue averaged 3.4% year-on-year growth. This was in line with reported revenue growth, indicating that foreign exchange has not had a meaningful impact on revenue. 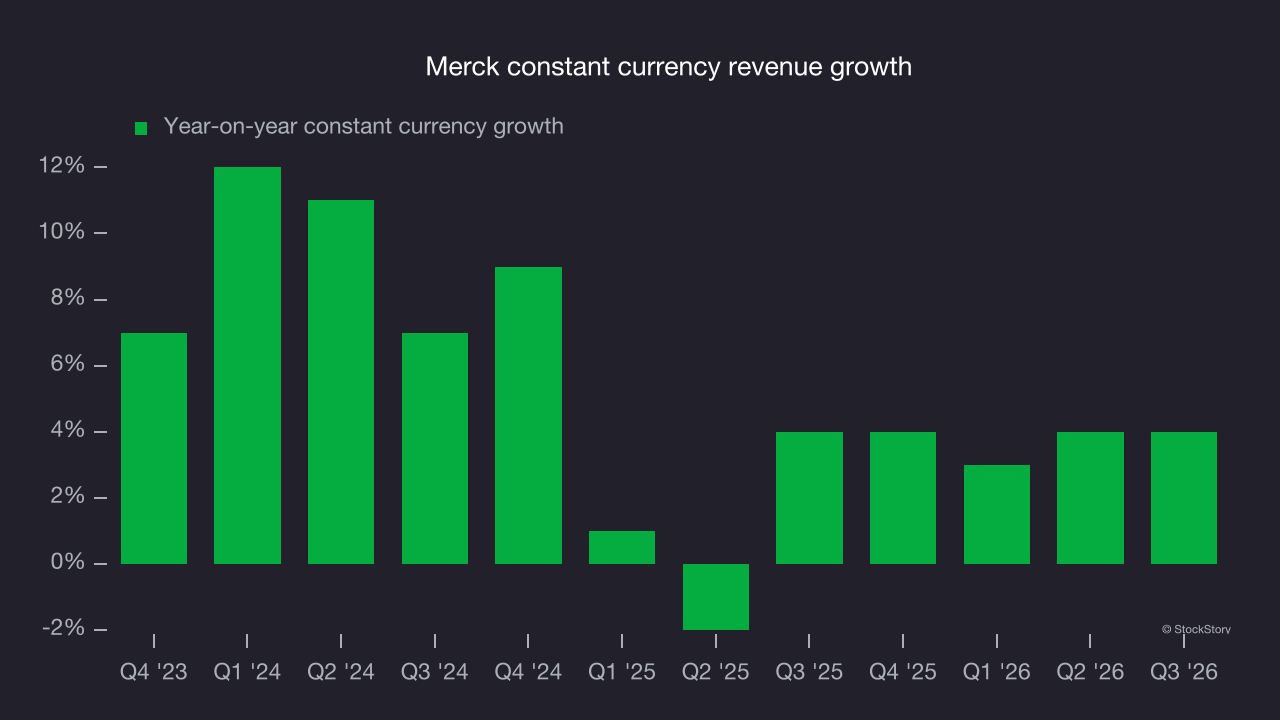
This quarter, Merck reported modest year-on-year revenue growth of 4.7% but beat Wall Street’s consensus estimates by 4.5%.
Looking ahead, sell-side analysts expect revenue to grow 1.7% over the next 12 months, according to S&P, a slight deceleration versus the last two years. This projection is underwhelming and implies its products and services will see some demand headwinds.
Adjusted operating margin
Merck has been an efficient company over the last five years. It was one of the more profitable businesses in the healthcare sector, with an average adjusted operating margin of 28.2%.
Looking at the trend in its profitability, Merck’s adjusted operating margin decreased by 22.3 percentage points over the last five years. The company’s two-year trajectory also shows it failed to restore profitability to its peak, as its margin fell by 12.3 percentage points. This poor performance shows its expenses were rising and it couldn’t pass those costs on to its customers.
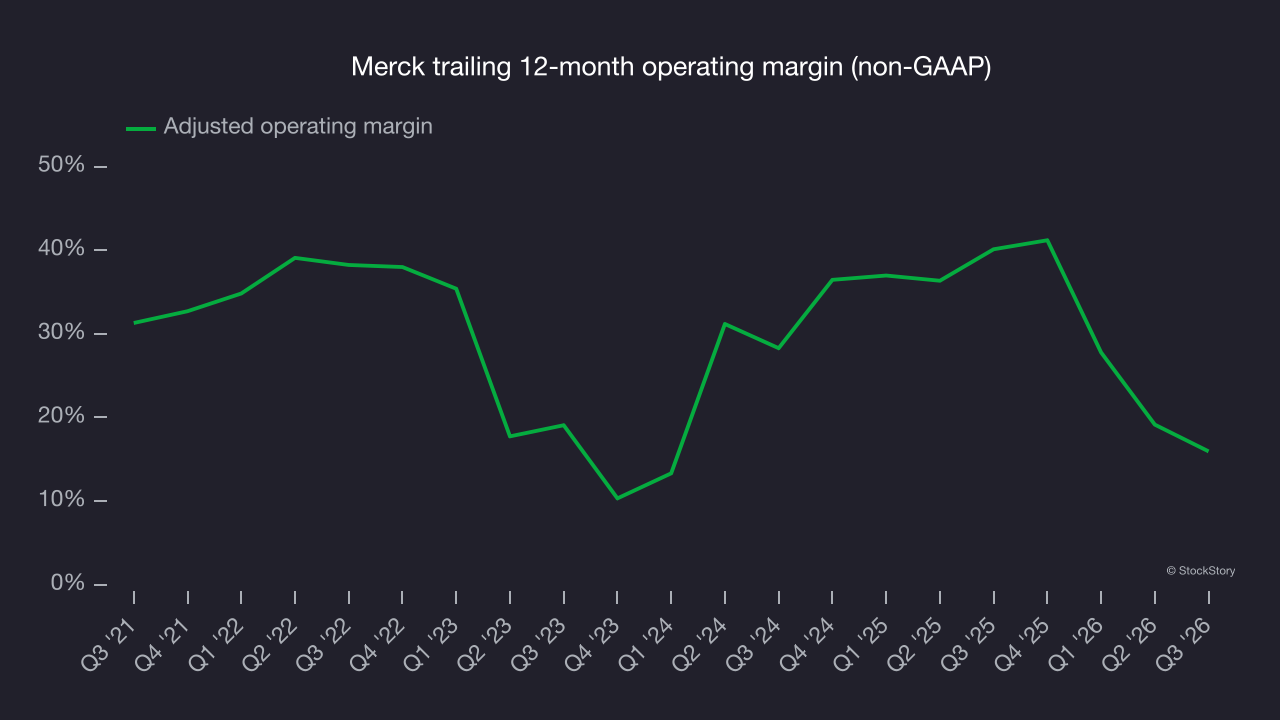
In Q3, Merck generated an adjusted operating margin of 30.7%, down 13 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Merck’s EPS declined by 11.6% annually over the last five years while its revenue grew by 7.9%. This indicates the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
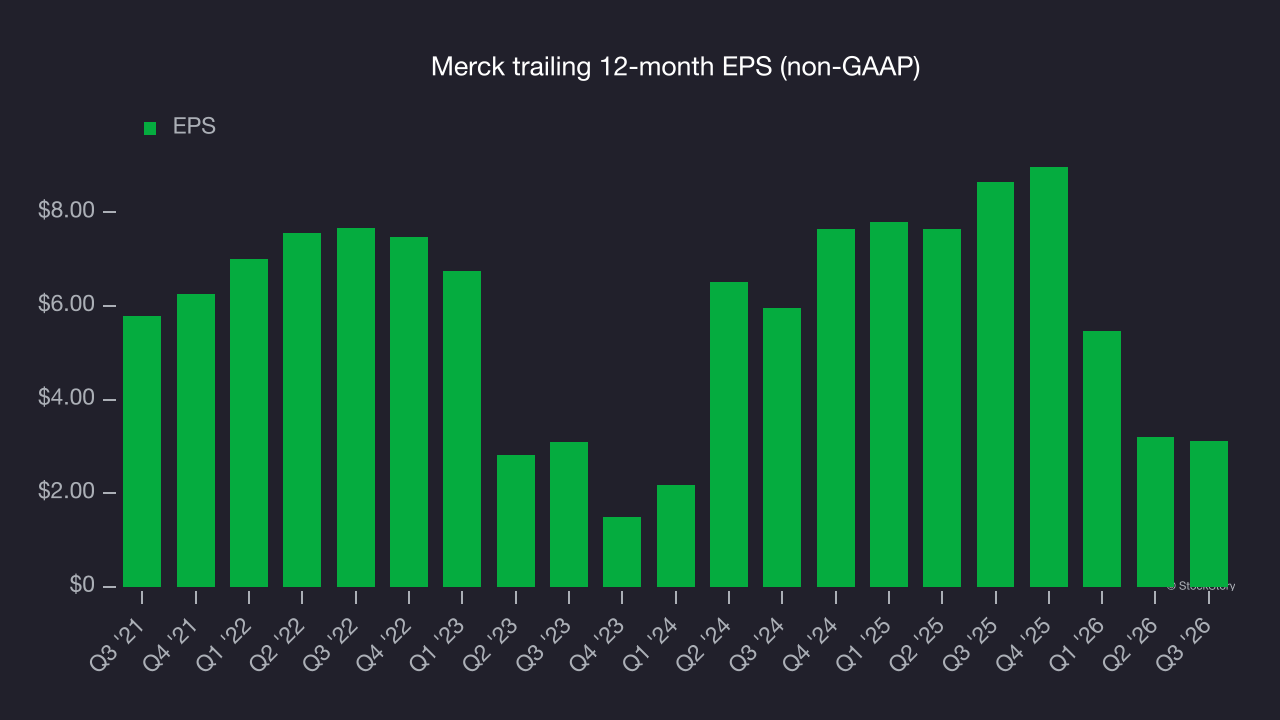
We can take a deeper look into Merck’s earnings to better understand the drivers of its performance. As we mentioned earlier, Merck’s adjusted operating margin declined by 22.3 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, Merck reported adjusted EPS of $2.49, down from $2.58 in the same quarter last year. Despite falling year on year, this result easily cleared analysts’ consensus estimates. Over the next 12 months, Wall Street expects Merck’s full-year EPS to grow 176% from $3.12 to $8.62, according to S&P.
Key takeaways from Merck’s Q3 results
Full-year EPS guidance was the standout in Merck’s solid quarter, coming in well above analysts’ consensus estimates. Revenue also topped Wall Street’s consensus. Shares rose 2.2% to $144.16 immediately after the results.
Merck had a solid quarter, but the broader investment picture also matters. When assessing the stock, it’s important to consider its valuation and business quality alongside the latest quarter’s results. For more on Merck, read the full research report here (it’s free).