Luxury casino and resort operator Monarch (NASDAQ: MCRI) missed Wall Street’s revenue expectations in Q3 2026 as revenue rose 2.4% year on year to $146.3 million. Its GAAP profit of $1.76 per share was 4.1% below analysts’ consensus estimates.
For more on Monarch, read our full research report for free.
Monarch (MCRI) Q3 2026 highlights:
- Revenue $146.3 million vs S&P analysts’ consensus estimates of $148 million (2.4% year-on-year growth, 1.2% miss)
- EPS (GAAP) $1.76 vs analysts’ consensus estimates of $1.84 (4.1% miss)
- Adjusted EBITDA $56.02 million vs analysts’ consensus estimates of $56.35 million (38.3% margin, 0.6% miss)
- Operating margin 28.2%, up from 26.7% in the same quarter last year
- Market capitalization $2.08 billion
“We continue to return capital to stockholders through share repurchases and dividends. In the third quarter of 2026, we purchased, in open market transactions, 300,859 shares of Monarch common stock for $37 million. In the third quarter of 2026, we also returned $5.3 million to stockholders through our quarterly cash dividend. We ended the quarter with a solid cash position of $137.4 million.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Over the last five years, Monarch grew its revenue at a 10.5% annual rate. Though this growth is acceptable on an absolute basis, revenue growth alone is not enough in the consumer discretionary sector, which can display significant earnings volatility. The bar for the sector is therefore particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, the five-year compounded annual growth rate starts around Covid, when revenue was depressed before rebounding.
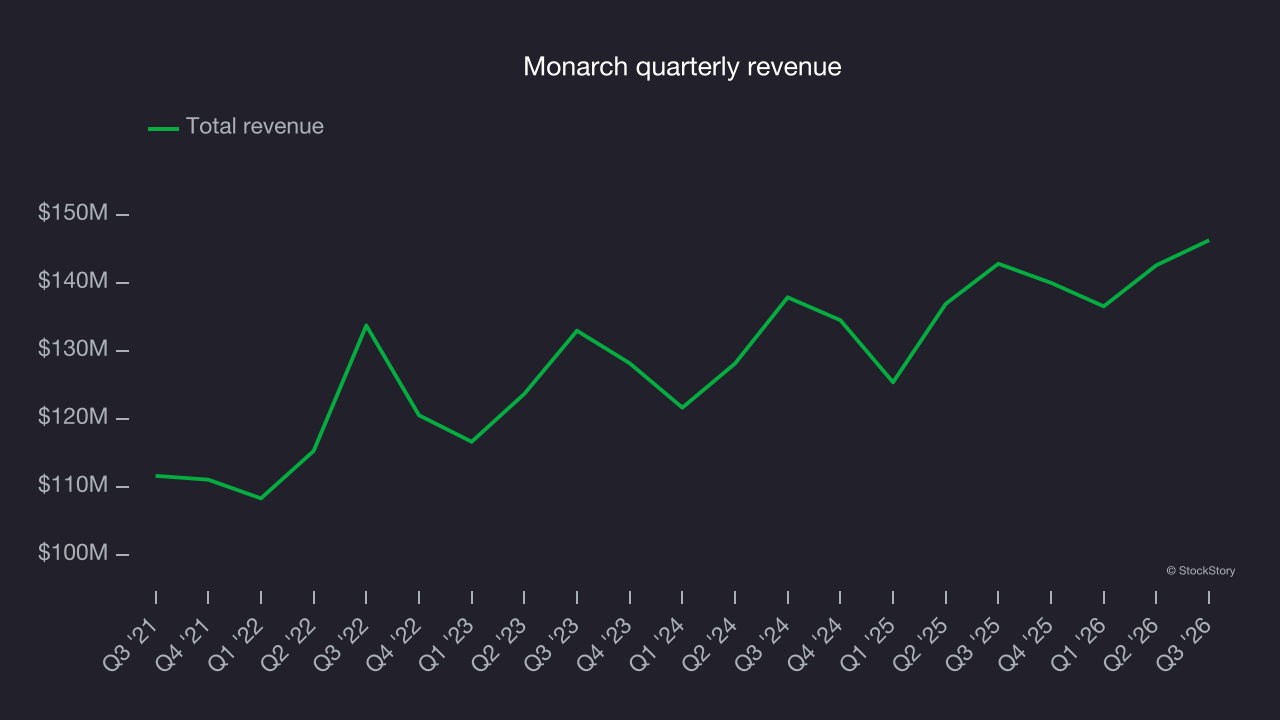
Long-term growth matters most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new product or trend. Monarch’s recent performance shows its demand has slowed as its annualized revenue growth of 4.7% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. Note that Covid hurt Monarch’s business in 2020 and part of 2021, and it rebounded thereafter. 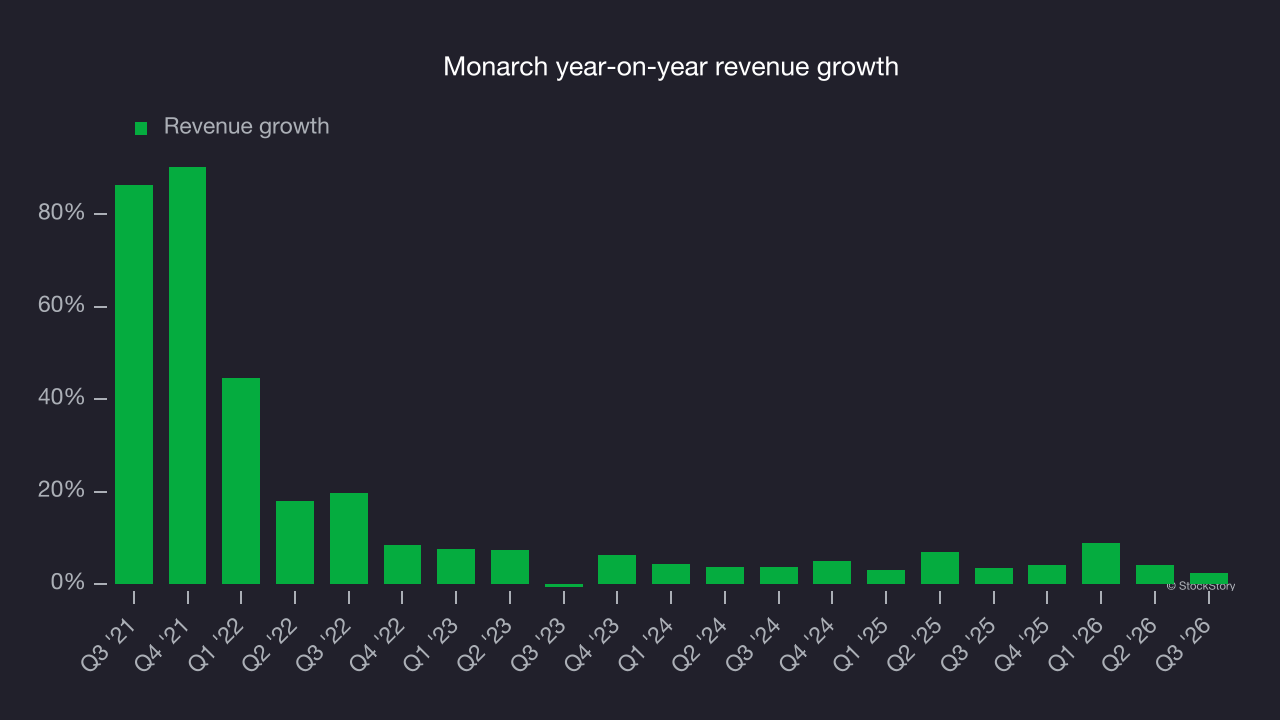
Monarch also breaks out the revenue for its three most important segments: Casino, Dining and Hotel, which are 56.6%, 23.4% and 15.5% of revenue. Over the last two years, Monarch’s revenue in all three segments increased. Its Casino revenue (Poker, Blackjack) averaged year-on-year growth of 5.3% while its Dining (food and beverage) and Hotel (overnight stays) revenue averaged 3.5% and 5.9%. 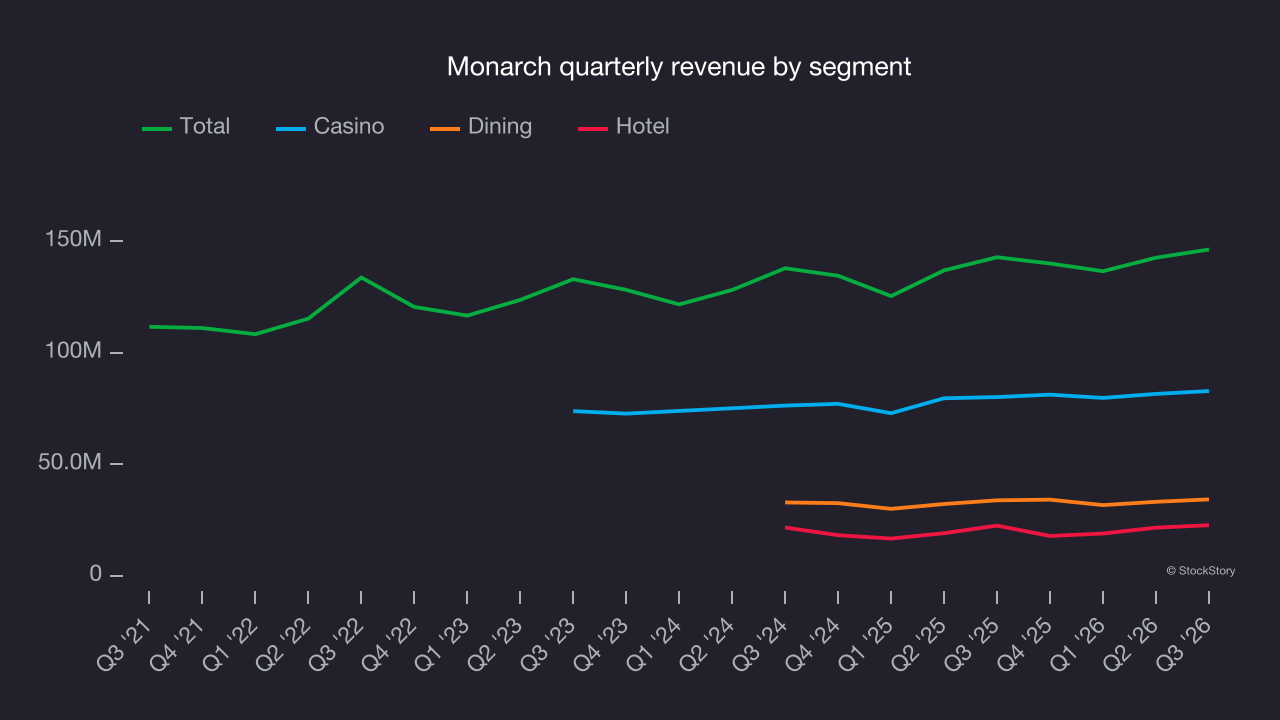
This quarter, Monarch’s revenue grew by 2.4% year on year to $146.3 million, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 2.3% over the next 12 months, according to S&P, a slight deceleration versus the last two years. This projection is underwhelming and indicates its products and services will face some demand challenges.
Operating margin
Monarch’s operating margin has been trending up over the last 12 months and averaged 22.9% over the last two years. The company’s improved efficiency is a positive, but its suboptimal cost structure still leaves it with poor profitability for a consumer discretionary business.
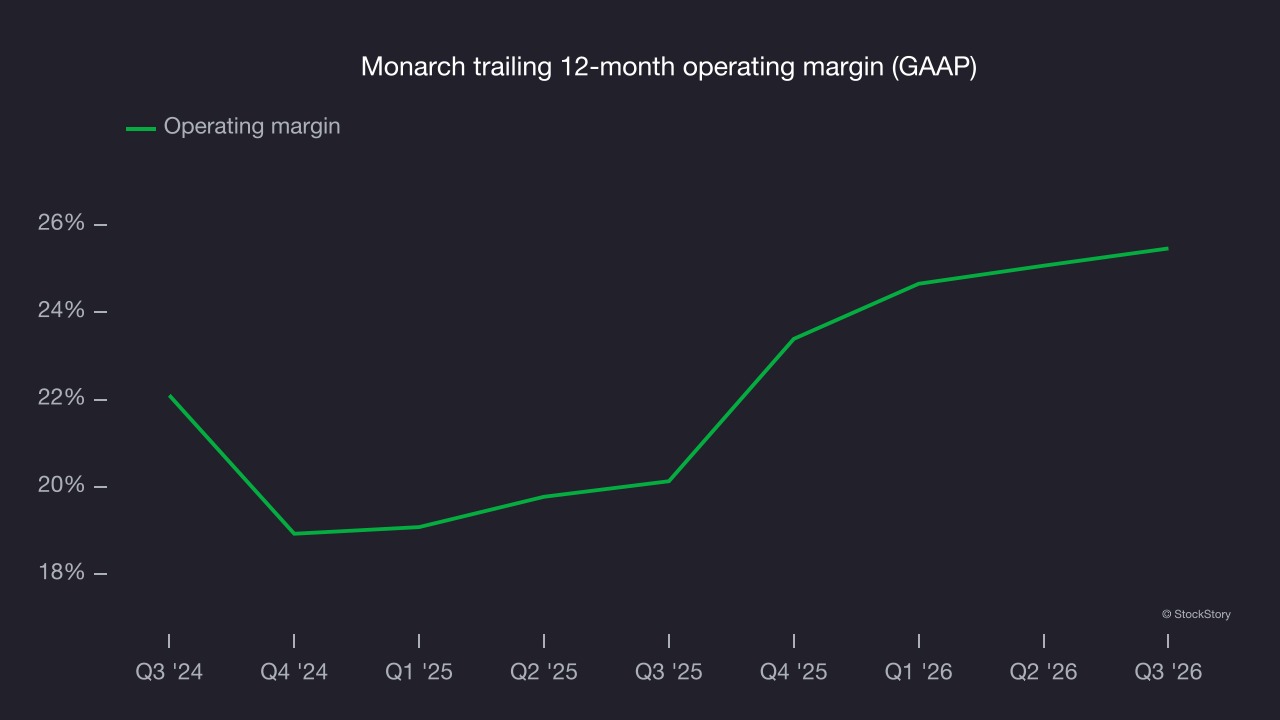
In Q3, Monarch generated an operating margin of 28.2%, up 1.5 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Monarch’s EPS grew at a 13.8% compounded annual growth rate over the last five years. On the positive side, this outpaced its 10.5% annualized revenue growth, indicating the company became more profitable on a per-share basis as it expanded.
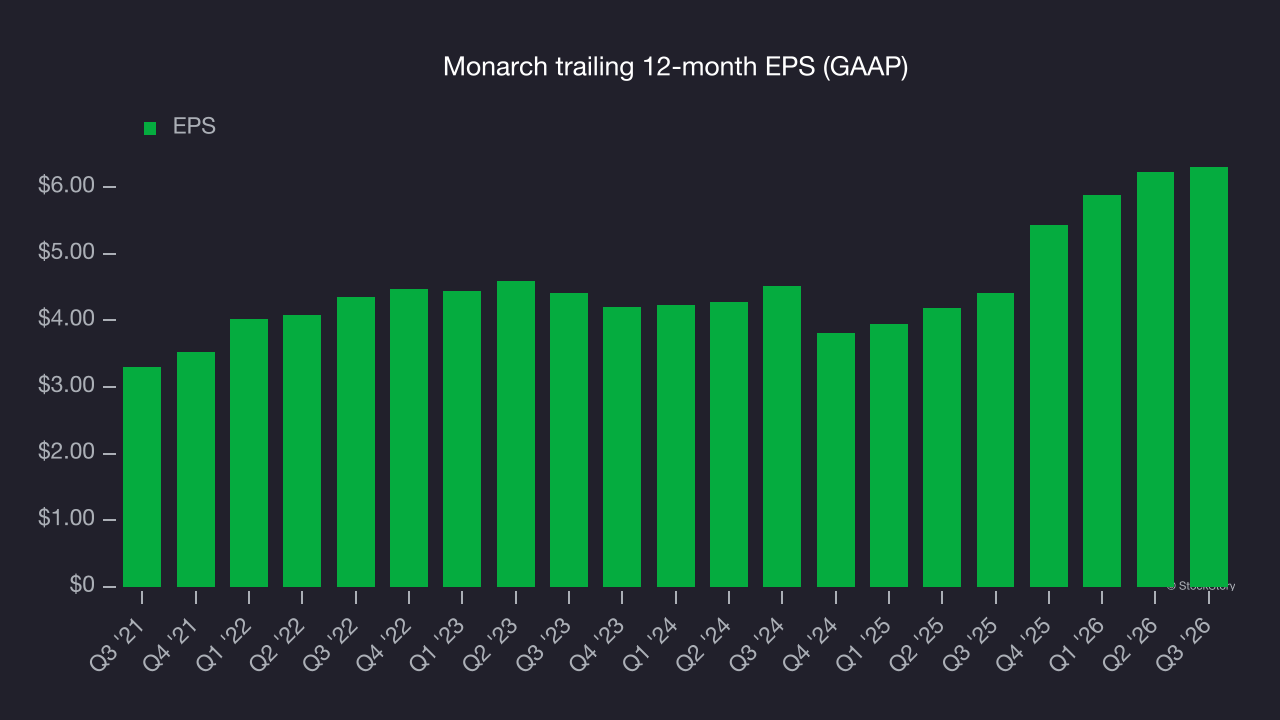
In Q3, Monarch reported EPS of $1.76, up from $1.69 in the same quarter last year. Despite growing year on year, EPS missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects Monarch’s full-year EPS to grow 7.6% from $6.30 to $6.78, according to S&P.
Key takeaways from Monarch’s Q3 results
Monarch delivered a weaker quarter with few positives: EPS missed expectations and revenue came in slightly below Wall Street’s consensus estimates. Shares fell 3.3% to $111.78 immediately after the results.
Monarch’s earnings report left more to be desired. Whether this quarter has created a buying opportunity depends on the bigger picture. That decision should take into account valuation, business quality and the latest earnings. For more on Monarch, read our full research report here (it’s free).