
Shanghai, China--(Newsfile Corp. - November 21, 2026) - Frost & Sullivan has officially released the "2026 Global Medical Robots Industry Development Blue Book". The Blue Book systematically reviews the development of the medical robots industry, covering the definition and classification of medical robots, the industry value chain and market access, and the clinical applications, core technologies and competitive landscapes across ten major segments: laparoscopic surgical robots, orthopedic surgical robots, natural orifice surgical robots, neurosurgical robots, vascular interventional robots, dental robots, percutaneous puncture robots, ablation robots, hair transplantation robots, and rehabilitation robots. It also examines China's policy evolution, capital-market trends, overseas expansion, and representative enterprise cases, providing a reference for healthcare institutions, technology providers, investors, and other industry participants. (To learn more about the 2026 Global Medical Robots Industry Development Blue Book, please visit: https://hub.frost.com/global-medical-robots-industry-development-blue-book/)
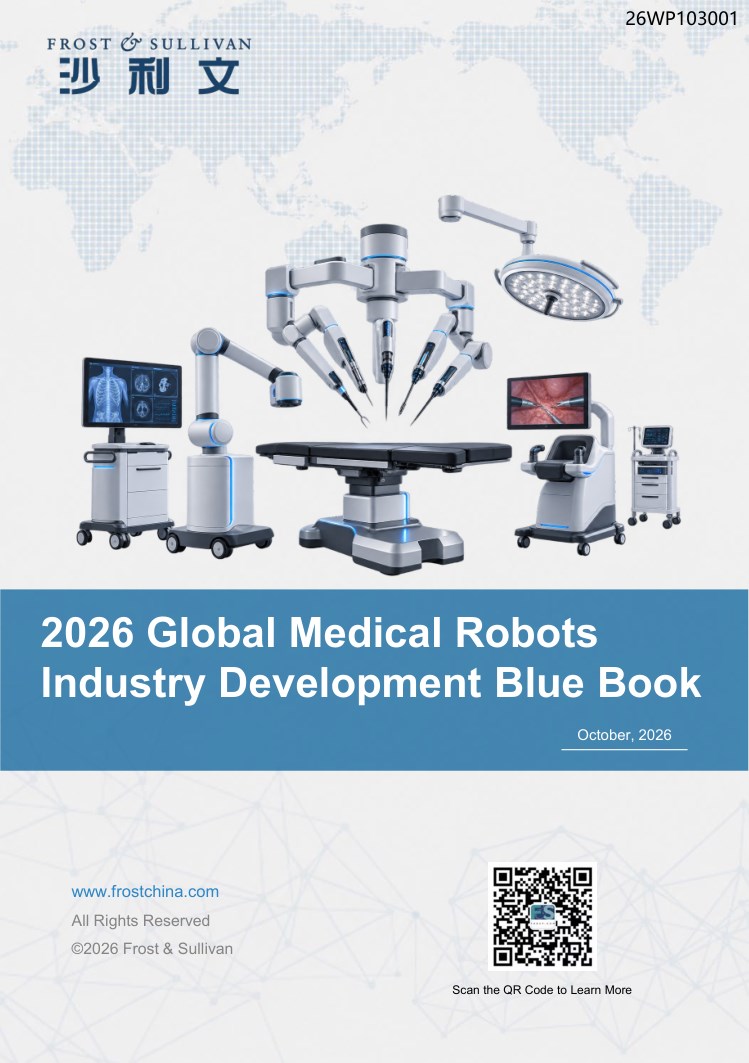
Medical robots are intelligent robotic systems that assist or replace healthcare personnel in diagnosis, treatment, rehabilitation, nursing and hospital operations. By integrating precision engineering, medical imaging, artificial intelligence, sensing and automatic control, medical robots can improve surgical precision, standardization and efficiency while supporting minimally invasive treatment, rehabilitation training and hospital operations. Based on application scenarios and functions, medical robots can be broadly classified into surgical robots, rehabilitation robots, assistive robots, and medical service or operation-support robots.
The medical robots industry value chain is evolving from a traditional linear equipment-manufacturing model into a network-like ecosystem centered on "technology-platform-application-data-iteration". Upstream suppliers provide core components and technical infrastructure, including precision components, control systems, vision sensors and AI algorithms; midstream companies integrate hardware, software and clinical workflows into robotic platforms and commercial systems; and downstream healthcare institutions generate clinical applications and data feedback that support product refinement and standardized workflows. Business models are also evolving beyond equipment sales toward recurring revenue from consumables, software and services.
The Blue Book examines ten major medical robot segments in detail. Laparoscopic surgical robots are moving from import-dominated competition toward a more diversified market with multi-port, single-port and multi-platform products. Orthopedic robots are expanding across joint replacement, spine, trauma and sports medicine, with competition shifting toward intelligent planning, dynamic tracking, execution and multi-indication platforms. Natural orifice, neurosurgical, vascular interventional, dental, percutaneous puncture, ablation, hair transplantation and rehabilitation robots are developing along differentiated clinical and technical pathways, with clinical validation, usability, workflow integration and service capabilities becoming increasingly important.
China's medical robot policy framework has evolved from early support for core technology research and domestic innovation toward a broader lifecycle framework covering product development, registration, hospital deployment, procurement, medical service pricing and reimbursement. Policies supporting intelligent medical robot development, streamlined equipment deployment approvals, import substitution, and health insurance and medical service pricing are progressively reducing institutional barriers to clinical translation and commercialization.
As the industry develops, capital-market evaluation is moving beyond technology feasibility and product registration toward commercialization and sustainable clinical use. For early-stage companies, technology barriers, product pipelines, clinical trials and regulatory milestones remain important. After products enter hospitals, installed base, physician coverage, market share and clinical application become increasingly relevant. At scale, utilization, procedure or treatment volume, consumables and service revenue, gross margin and the path to profitability are becoming core indicators of long-term business quality and valuation.
Chinese medical robot manufacturers are accelerating international expansion, with overseas strategies evolving from product registration and distributor-led sales toward clinical validation, physician training, local channels and service systems. Because medical robots combine high technical complexity with high clinical and regulatory barriers, international competitiveness increasingly depends on product performance, regulatory approvals, clinical evidence, physician recognition and localized commercial and after-sales capabilities. The industry is therefore moving from "product export" toward "clinical export" and "system export".
Looking ahead, medical robots are expected to advance toward greater precision, minimally invasive treatment, intelligence, platformization and global reach. Artificial intelligence and multimodal sensing will strengthen robots' understanding of complex clinical environments and support clinical decision-making, while robotic involvement will extend from navigation and mechanical assistance toward more sophisticated execution and human-machine collaboration. As lifecycle business models combining equipment, consumables, software and services mature, clinical value, payment mechanisms and the ability to achieve large-scale deployment will become increasingly important to the next stage of industry growth.
The development of medical robots is also reshaping the competitive landscape across the broader healthcare ecosystem. Equipment manufacturers are strengthening software, AI and platform capabilities; technology suppliers are integrating components, algorithms and sensing into more scalable systems; hospitals and specialist centers are becoming important sources of clinical validation and data feedback; and service networks are becoming critical to training, maintenance and long-term utilization. These changes are encouraging deeper collaboration among technology companies, healthcare institutions, clinicians and other ecosystem participants.
The Blue Book further analyzes representative companies and industry development pathways, including Baihui Weikang, Edge Medical (2675.HK), Rossum Robot and SAGEBOT. Their product portfolios and commercialization progress illustrate different approaches to clinical specialization, platform development and internationalization, providing practical reference points for understanding how medical robot companies can move from technological innovation to sustained clinical and commercial deployment.
As medical robots move from technical validation toward broader clinical adoption, the industry is entering a stage in which clinical value, regulatory access, payment mechanisms, utilization and service capabilities are increasingly connected. The 2026 Global Medical Robots Industry Development Blue Book provides a structured view of these changes and highlights the opportunities and challenges that will shape the next stage of medical robot industry development in China and globally.
The 2026 Global Medical Robots Industry Development Blue Book highlights the following:
- Definition, Classification, and Industry Value Chain: Defining medical robots, distinguishing surgical, rehabilitation, assistive, and medical service or operation-support robots, and analyzing the evolving value chain from core components to clinical applications and data feedback.
- Ten Major Medical Robot Segments: Examining laparoscopic, orthopedic, natural orifice, neurosurgical, vascular interventional, dental, percutaneous puncture, ablation, hair transplantation, and rehabilitation robots, including their technologies, applications, competitive landscapes, and development trends.
- China's Policy Evolution: Analyzing policy support across intelligent medical robot development, equipment deployment approvals, import substitution, medical service pricing, and health insurance, and assessing the impact on clinical translation and commercialization.
- Capital-Market Trends and Valuation: Exploring listing milestones, review criteria, operating performance, and how valuation drivers evolve from R&D and registration toward commercialization, utilization, recurring revenue, and profitability.
- International Expansion of Chinese Medical Robot Manufacturers: Reviewing stages and models of global expansion, major overseas markets, regulatory and market access differences, key challenges, and the shift from product export to clinical and system-level internationalization.
- Clinical and Commercialization Drivers: Assessing how clinical evidence, physician adoption, installed base, procedure or treatment volume, utilization, consumables, software and services influence the long-term commercial value of medical robot products.
- Technology and Business Model Evolution: Highlighting the integration of AI, multimodal sensing, precision engineering and automatic control, together with the maturation of equipment-plus-consumables-plus-software-plus-services lifecycle models.
- Representative Enterprise Cases: Providing case studies of Baihui Weikang, Edge Medical (2675.HK), Rossum Robot and SAGEBOT to illustrate different approaches to product development, commercialization and industry expansion.
Key Topics Covered
1. Medical Robots Industry Development Overview: Technology Integration and Clinical Needs
- a. Definition and Classification of Medical Robots
- b. Medical Robots Industry Chain Analysis
- c. Analysis of Major Medical Robots
- i. Laparoscopic Surgical Robots
- ii. Orthopedic Surgical Robots
- iii. Natural Orifice Surgical Robots
- iv. Neurosurgical Robots
- v. Vascular Interventional Robots
- vi. Dental Robots
- vii. Percutaneous Puncture Robots
- viii. Ablation Robots
- ix. Hair Transplantation Robots
- x. Rehabilitation Robots
- d. Medical Robots Industry Drivers and Future Trends
2. Medical Robots Industry Policy Evolution Analysis
- a. Evolution of China's Medical Robots Industrial Policy
- b. Policy Milestones and Industry Impact
3. Medical Robots Industry Capital-Market Trends
- a. Listing Milestones and Review Criteria
- b. Listed Medical Robot Companies: Performance and Valuation Trends
4. Medical Robots Overseas Trend Analysis
- a. Global Expansion of Chinese Medical Robot Manufacturers
- b. Regulatory and Market Access Differences
- c. International Expansion Strategies of Representative Companies
5. Medical Robots Industry Representative Enterprise Cases
- Baihui Weikang
- Edge Medical (2675.HK)
- Rossum Robot
- SAGEBOT
About Frost & Sullivan
Frost & Sullivan, the Growth Partnership Company, works in collaboration with clients to leverage visionary innovation that addresses the global challenges and related growth opportunities that will make or break today's market participants. For more than 60 years, Frost & Sullivan has been supporting the Global 1000, emerging businesses, the public sector, and investors in developing growth strategies.
Media Contact
Company Name: Frost & Sullivan
Website: http://www.frostchina.com
Email: PR@frostchina.com
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/324988