What a time it’s been for Q2 Holdings. In the past six months alone, the company’s stock price has increased by a massive 49.5%, reaching $73.75 per share. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Q2 Holdings, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why is Q2 Holdings not exciting?
We’re happy investors have made money, but we’re cautious about Q2 Holdings. Here are three reasons why QTWO doesn’t excite us, plus one stock we’d rather own.
1. Weak billings point to soft demand
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
Q2 Holdings’s billings came in at $240 million in Q3, and over the last four quarters, its year-on-year growth averaged 11.5%. This performance was underwhelming and suggests that increasing competition is causing challenges in acquiring/retaining customers. 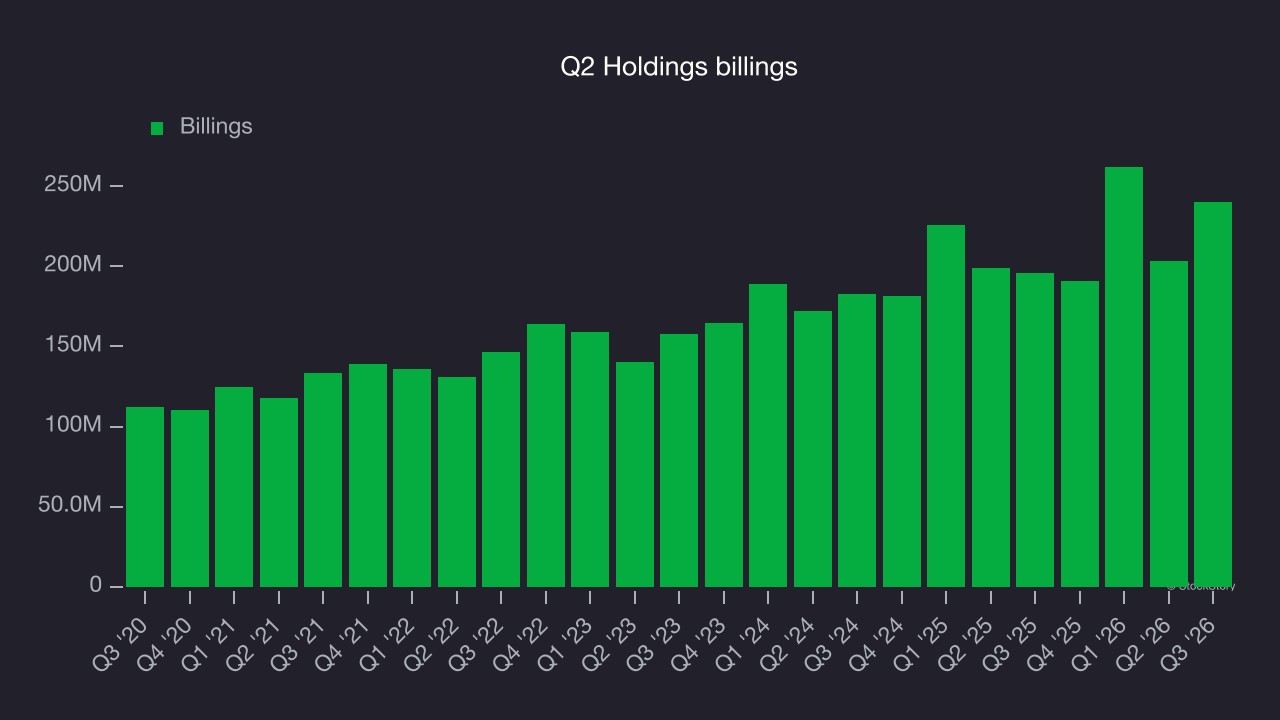
2. Projected revenue growth is slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Q2 Holdings’s revenue to rise by 9.8%, according to S&P, a deceleration versus its 12.7% annualized growth for the past five years. This projection is underwhelming and suggests its products and services will face some demand challenges.
3. Low gross margin reveals weak structural profitability
For software companies like Q2 Holdings, gross profit tells us how much money remains after paying for the base cost of products and services (typically servers, licenses, and certain personnel). These costs are usually low as a percentage of revenue, explaining why software is more lucrative than other sectors.
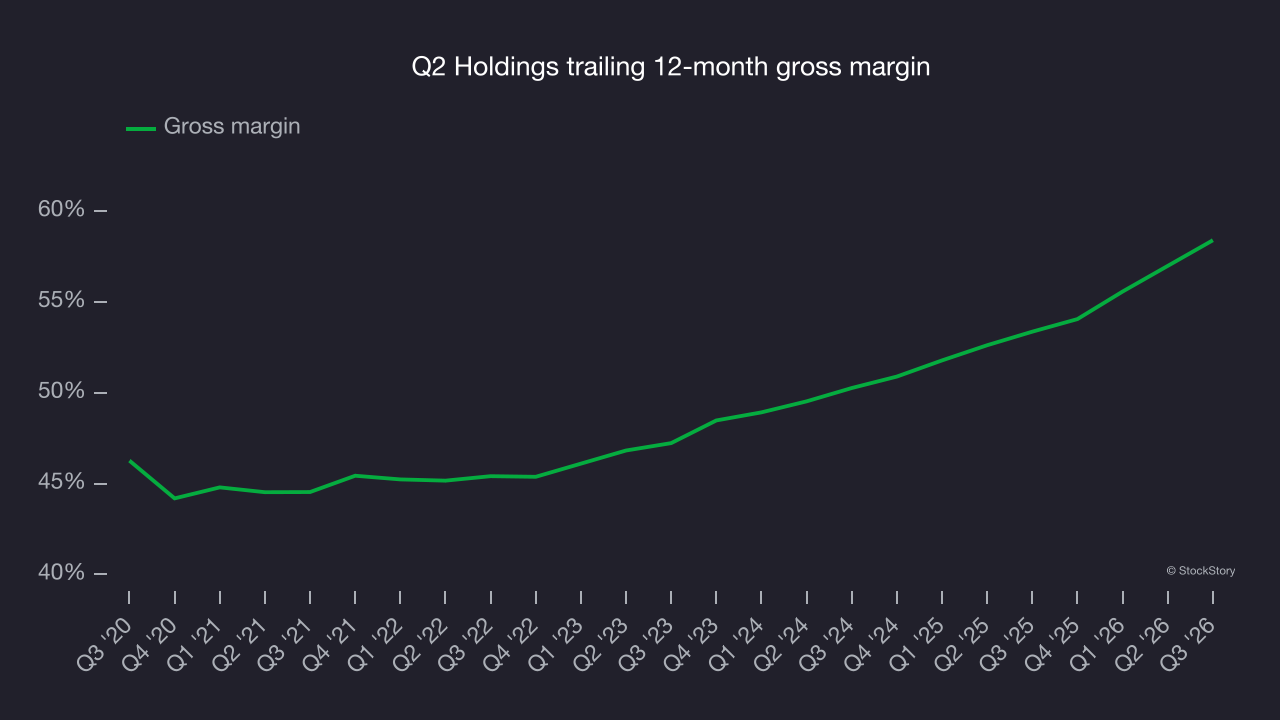
Q2 Holdings’s gross margin is substantially worse than most software businesses, signaling it has relatively high infrastructure costs compared to asset-lite businesses like ServiceNow. As you can see below, it averaged a 58.4% gross margin over the last year. That means Q2 Holdings paid its providers a lot of money ($41.60 for every $100 in revenue) to run its business.
The market not only cares about gross margin levels but also how they change over time because expansion creates firepower for profitability and free cash generation. Q2 Holdings has seen gross margins improve by 8.1 percentage points over the last 2 years, which is elite in the software space.
Final judgment
Q2 Holdings isn’t a terrible business, but it doesn’t pass our quality test. After the recent rally, the stock trades at 5× forward price-to-sales (or $73.75 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re fairly confident there are better stocks to buy right now. We’d recommend looking at one of our all-time favorite software stocks.
High-quality stocks for all market conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.