Colgate-Palmolive currently trades at $86.14 per share and has shown little upside over the past six months, posting a middling return of 1.9%. The stock also fell short of the S&P 500’s 18.4% gain during that period.
Given the weaker price action, is now a good time to buy CL? Or should investors expect a bumpy road ahead? Find out in our full research report, it’s free.
Why Does CL Stock Spark Debate?
Formed after the 1928 combination between toothpaste maker Colgate and soap maker Palmolive-Peet, Colgate-Palmolive (NYSE: CL) is a consumer products company that focuses on personal, household, and pet products.
Two Positive Attributes:
1. Elite Gross Margin Powers Best-In-Class Business Model
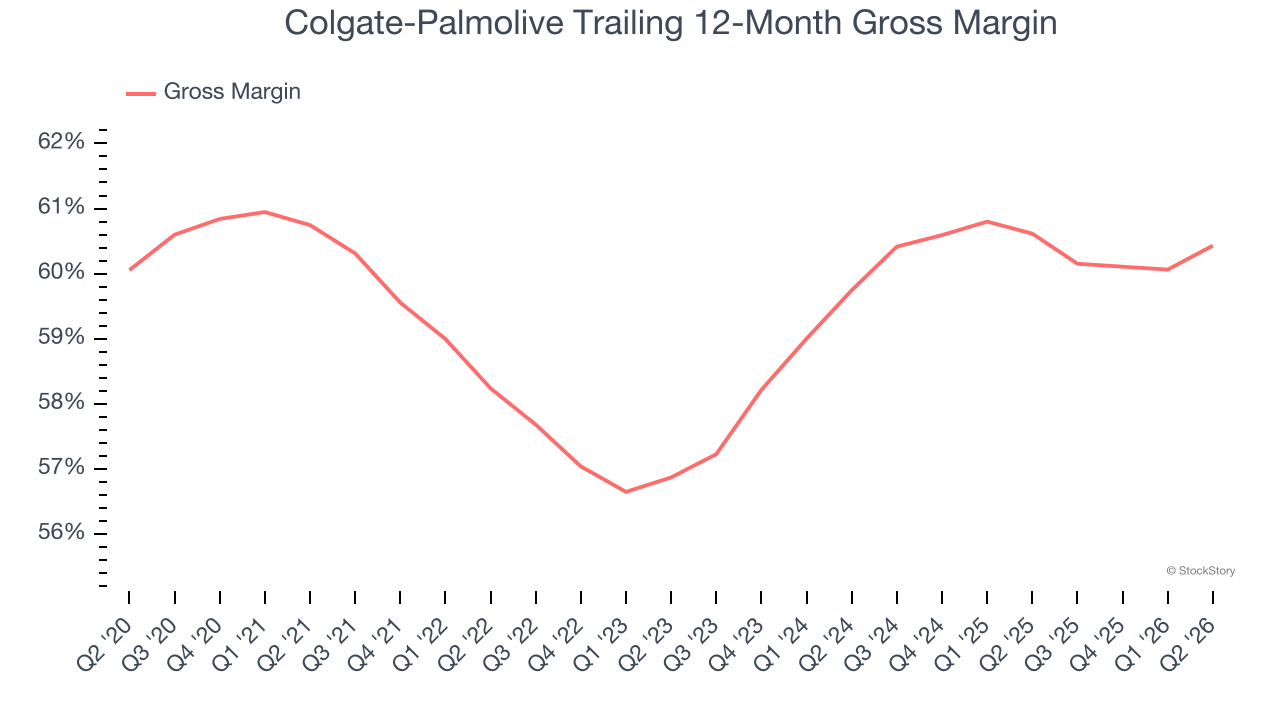
All else equal, we prefer higher gross margins because they make it easier to generate more operating profits and indicate that a company commands pricing power by offering more differentiated products.
Colgate-Palmolive has best-in-class unit economics for a consumer staples company, enabling it to invest in areas such as marketing and talent to grow its brand. As you can see below, it averaged an elite 60.5% gross margin over the last two years. That means Colgate-Palmolive only paid its suppliers $39.48 for every $100 in revenue.
2. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
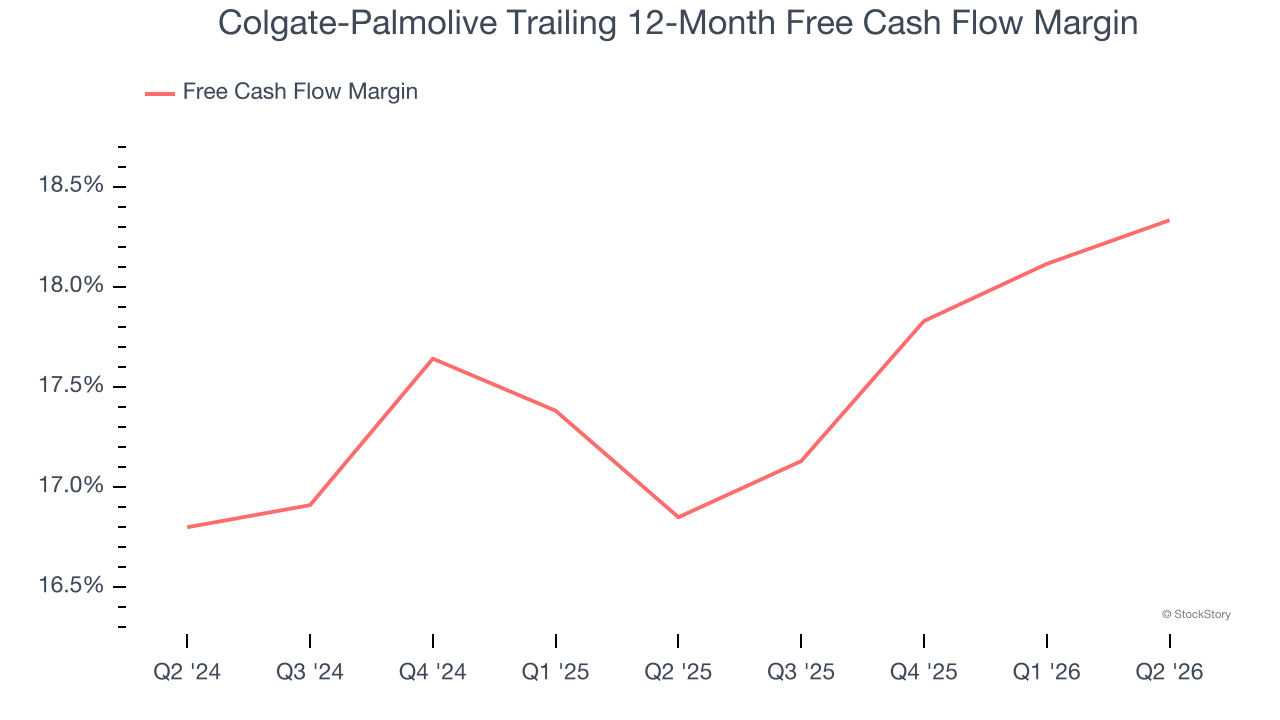
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Colgate-Palmolive has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the consumer staples sector, averaging 17.6% over the last two years.
One Reason to Be Careful:
Slow Organic Growth Suggests Waning Demand In Core Business
When analyzing revenue growth, we care most about organic revenue growth. This metric captures a business’s performance excluding one-time events such as mergers, acquisitions, and divestitures as well as foreign currency fluctuations.
The demand for Colgate-Palmolive’s products has generally risen over the last two years but lagged behind the broader sector. On average, the company’s organic sales have grown by 2.8% year on year. 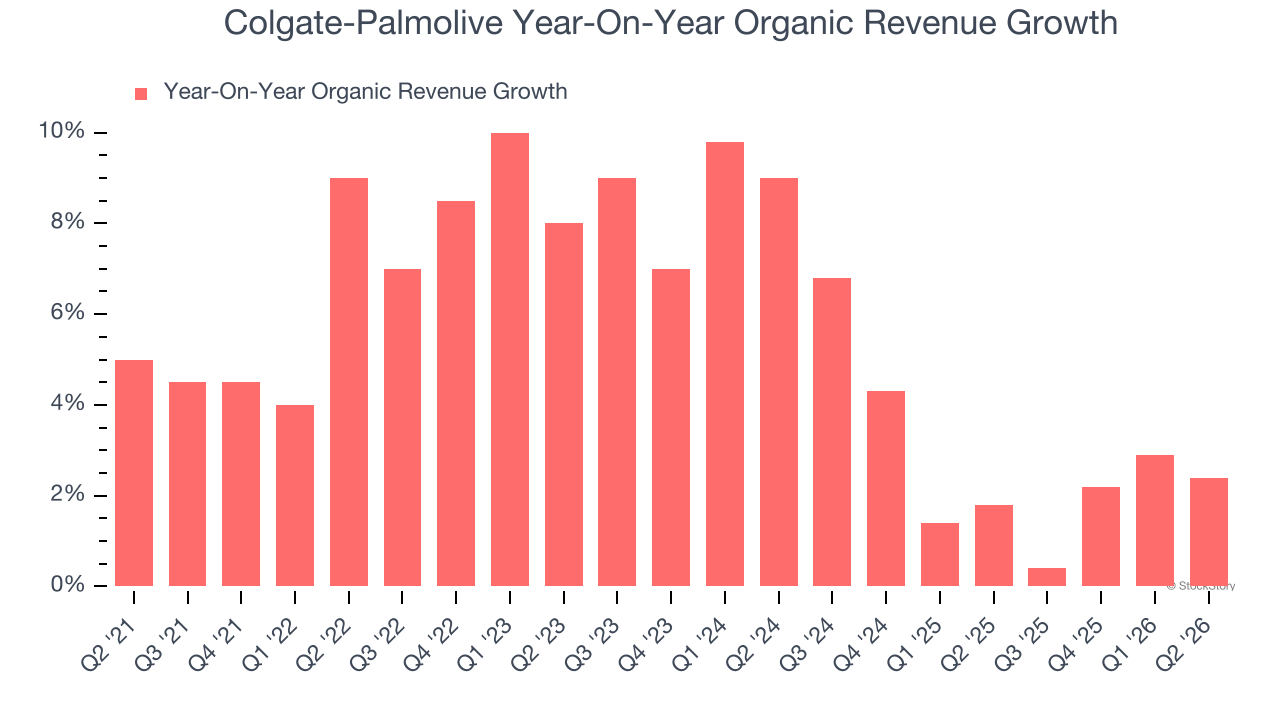
Final Judgment
Colgate-Palmolive’s merits more than compensate for its flaws. With its shares trailing the market in recent months, the stock trades at 22.2× forward P/E (or $86.14 per share). Is now a good time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than Colgate-Palmolive
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.