Over the last six months, C.H. Robinson Worldwide’s shares have sunk to $149, producing a disappointing 10.7% loss - a stark contrast to the S&P 500’s 18% gain. This might have investors contemplating their next move.
Is there a buying opportunity in C.H. Robinson Worldwide, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is C.H. Robinson Worldwide Not Exciting?
Even with the cheaper entry price, we’re sitting this one out for now. Here are three reasons we avoid CHRW, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
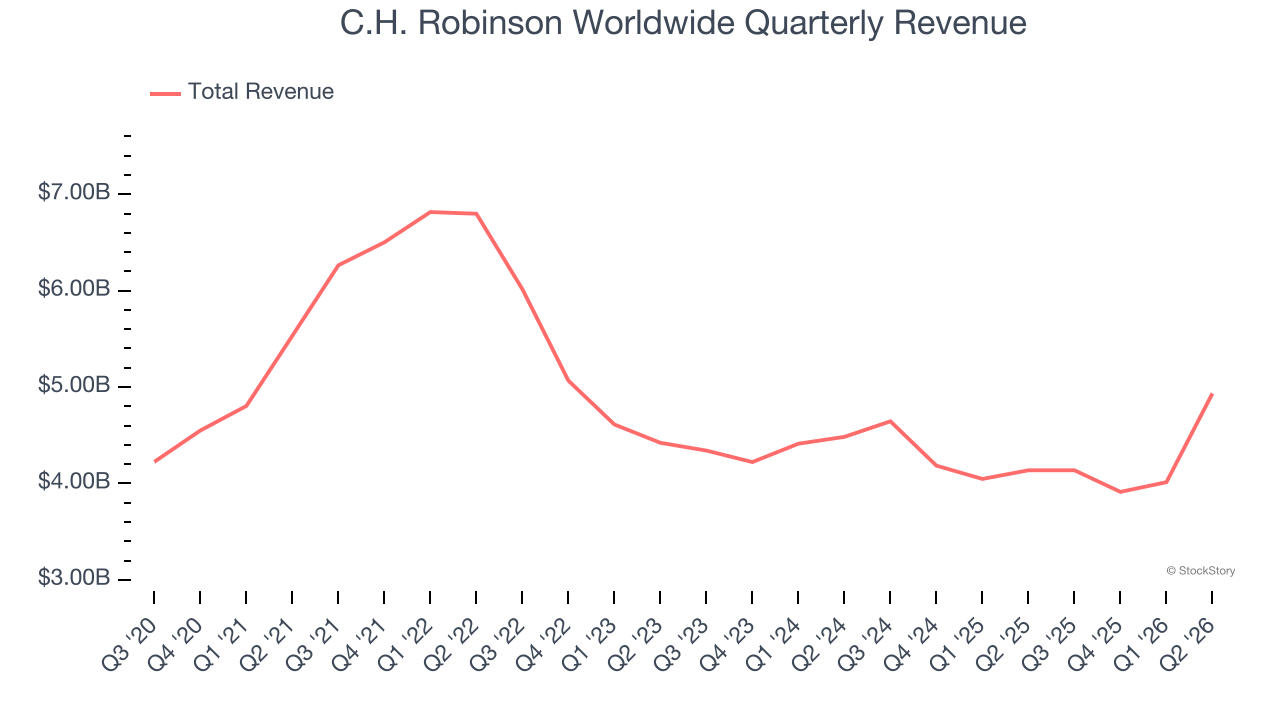
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. C.H. Robinson Worldwide’s demand was weak over the last five years as its sales fell at a 2.3% annual rate. This was below our standards and signals it’s a lower quality business.
2. Low Gross Margin Reveals Weak Structural Profitability
All else equal, we prefer higher gross margins because they make it easier to generate more operating profits and indicate that a company commands pricing power by offering more differentiated products.
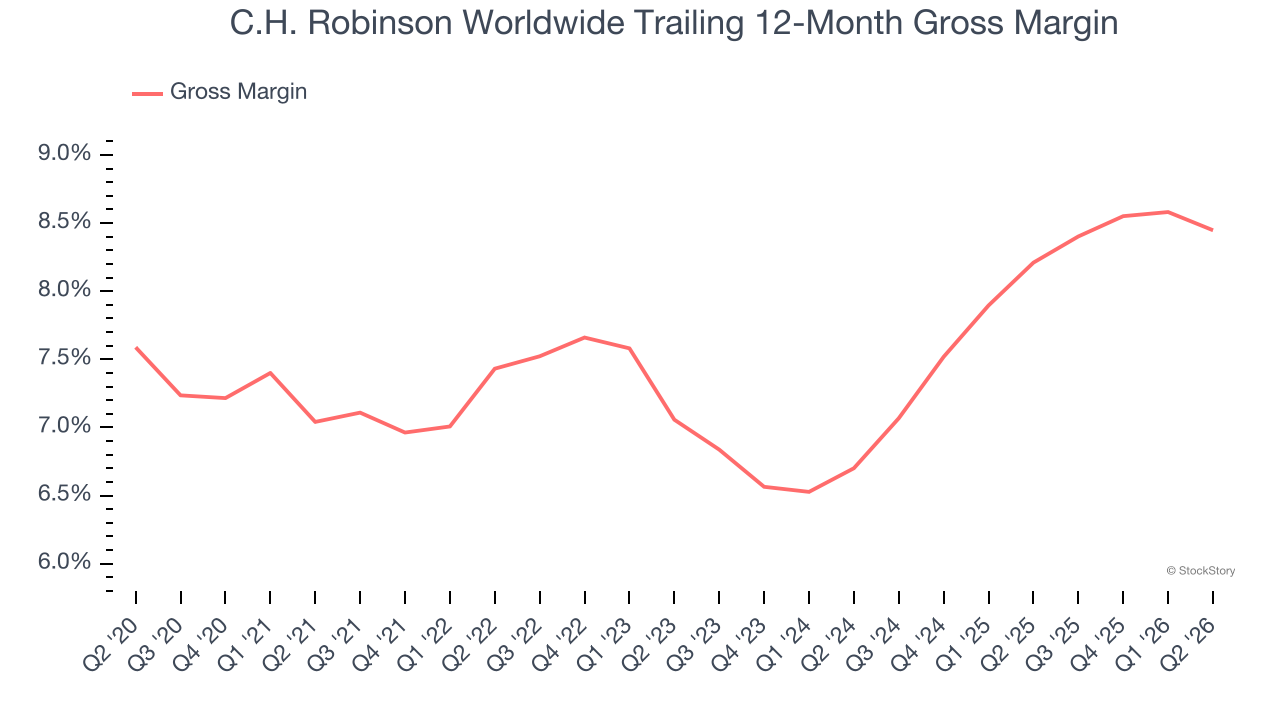
C.H. Robinson Worldwide has bad unit economics for an industrials business, signaling it operates in a competitive market. As you can see below, it averaged a 7.5% gross margin over the last five years. Said differently, C.H. Robinson Worldwide had to pay a chunky $92.46 to its suppliers for every $100 in revenue.
3. New Investments Fail to Bear Fruit as ROIC Declines
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
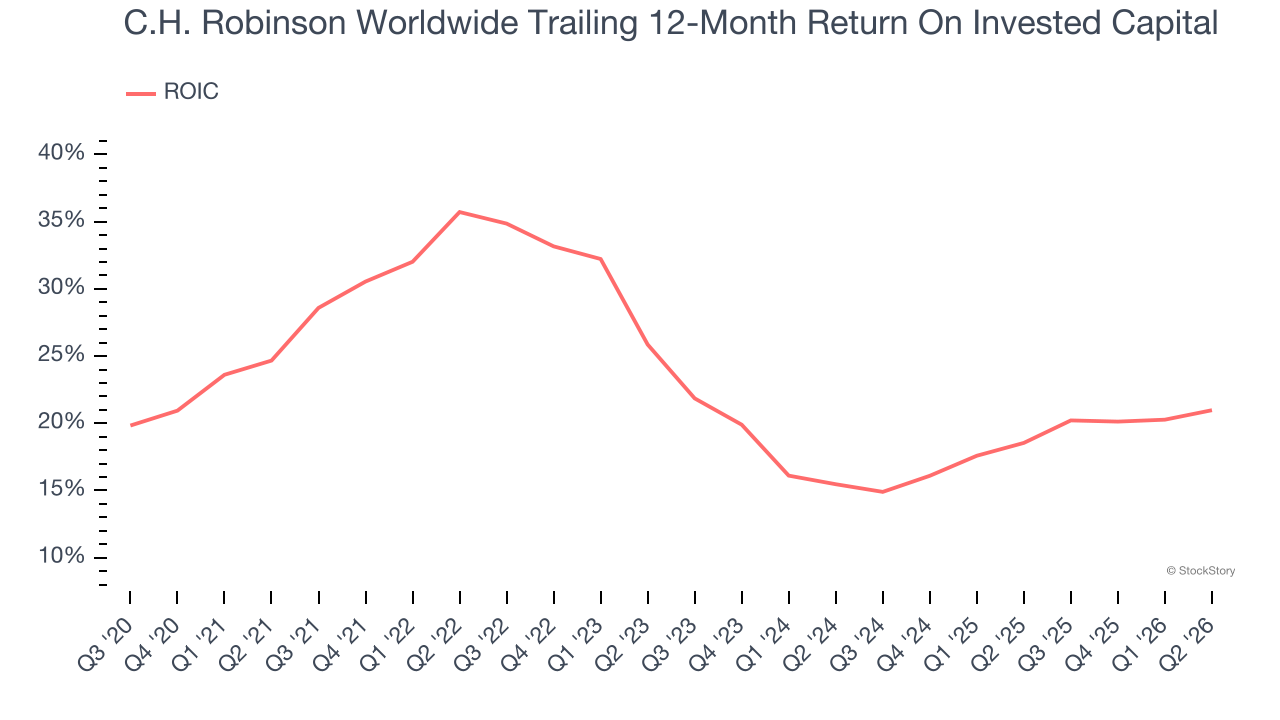
Over the last few years, C.H. Robinson Worldwide’s ROIC has unfortunately decreased significantly. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
C.H. Robinson Worldwide isn’t a terrible business, but it doesn’t pass our quality test. Following the recent decline, the stock trades at 22.1× forward P/E (or $149 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We’re fairly confident there are better investments elsewhere. We’d recommend looking at an all-weather company that owns household favorite Taco Bell.
Stocks We Like More Than C.H. Robinson Worldwide
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.