Lantheus currently trades at $100.02 and has been a dream stock for shareholders. It’s returned 270% since September 2021, blowing past the S&P 500’s 74.5% gain. The company has also beaten the index over the past six months as its stock price is up 32.1% thanks to its solid quarterly results.
Is there a buying opportunity in Lantheus, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Lantheus Not Exciting?
Despite the momentum, we don’t have much confidence in Lantheus. Here are three reasons we avoid LNTH, plus one stock we’d rather own.
1. Lackluster Revenue Growth
Long-term growth is the most important, but within healthcare, a stretched historical view may miss new innovations or demand cycles. Lantheus’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 4% over the last two years was well below its five-year trend. 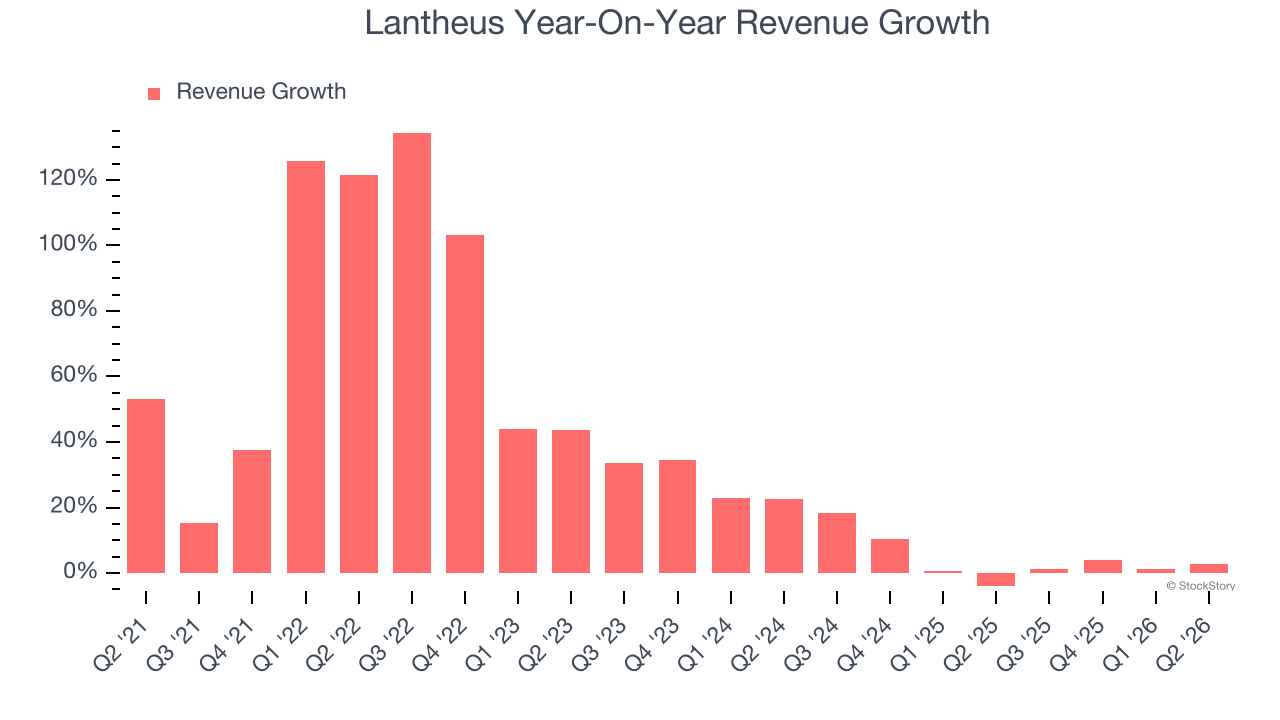
2. Revenue Projections Show Stormy Skies Ahead
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Lantheus’s revenue to drop by 1.2%, a decrease from its 32.8% annualized growth for the past five years. This projection is underwhelming and indicates its products and services will see some demand headwinds.
3. Shrinking Adjusted Operating Margin
Adjusted operating margin is one of the best measures of profitability because it tells us how much money a company takes home after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
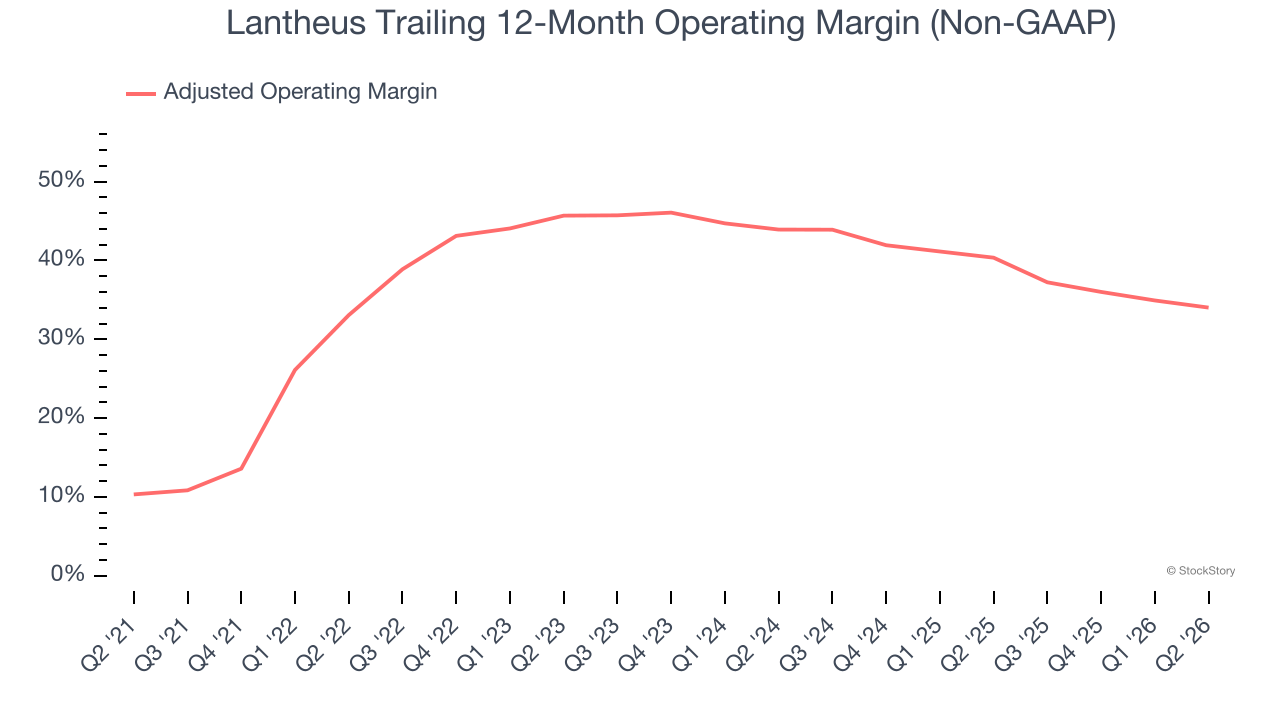
Analyzing the trend in its profitability, Lantheus’s adjusted operating margin decreased by 9.9 percentage points over the last two years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its adjusted operating margin for the trailing 12 months was 34%.
Final Judgment
Lantheus isn’t a terrible business, but it isn’t one of our picks. With its shares outperforming the market lately, the stock trades at 17.3× forward P/E (or $100.02 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re pretty confident there are superior stocks to buy right now. We’d recommend looking at a safe-and-steady industrials business benefiting from an upgrade cycle.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.