Wrapping up Q2 earnings, we look at the numbers and key takeaways for the oilfield services stocks, including Atlas Energy Solutions (NYSE: AESI) and its peers.
Oilfield services companies provide equipment, technology, and services enabling exploration and production activities, including drilling, completion, well intervention, and reservoir evaluation. Their fortunes closely track upstream capital spending cycles. Tailwinds include increased drilling activity during favorable commodity environments, demand for efficiency-enhancing technologies, and growing offshore and unconventional resource development. Headwinds include significant revenue volatility tied to oil and gas price swings and producer spending discipline. Intense competition pressures pricing and margins, while the energy transition may structurally reduce long-term demand. Workforce availability and technological disruption require continuous adaptation.
The 25 oilfield services stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 4.6%.
In light of this news, share prices of the companies have held steady as they are up 4.3% on average since the latest earnings results.
Atlas Energy Solutions (NYSE: AESI)
Building the world's first long-haul proppant conveyor system to reduce truck traffic, Atlas Energy Solutions (NYSE: AESI) mines and processes sand used as proppant to prop open fractures in oil and gas wells during hydraulic fracturing.
Atlas Energy Solutions reported revenues of $293.2 million, up 1.6% year on year. This print exceeded analysts’ expectations by 3.1%. Despite the top-line beat, it was still a mixed quarter for the company with a narrow beat of analysts’ EBITDA estimates but a significant miss of analysts’ EPS estimates.
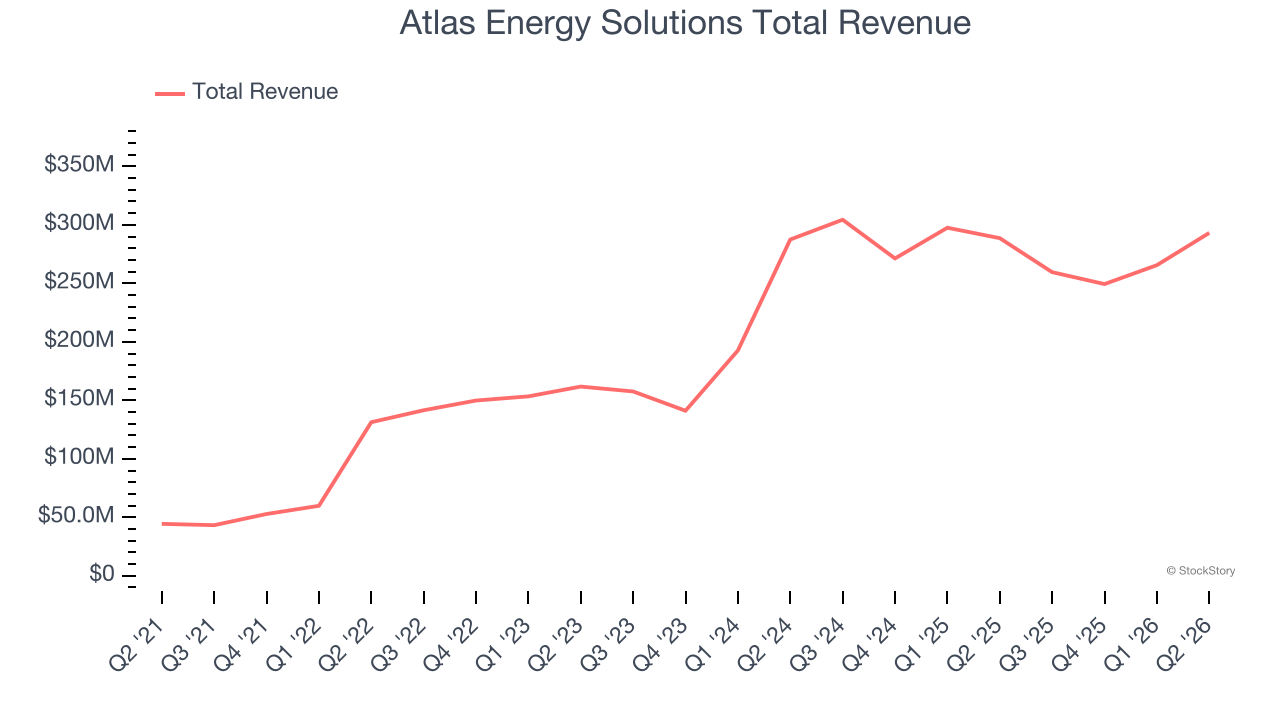
Interestingly, the stock is up 24.6% since reporting and currently trades at $13.62.
Read our full report on Atlas Energy Solutions here, it’s free.
Best Q2: Select Water Solutions (NYSE: WTTR)
Managing over 24 billion barrels of produced water annually across major U.S. shale plays, Select Water Solutions (NYSE: WTTR) provides water sourcing, recycling, disposal, and treatment services for oil and gas producers.
Select Water Solutions reported revenues of $395.8 million, up 8.7% year on year, outperforming analysts’ expectations by 5.7%. The business had an incredible quarter with a beat of analysts’ EPS and EBITDA estimates.
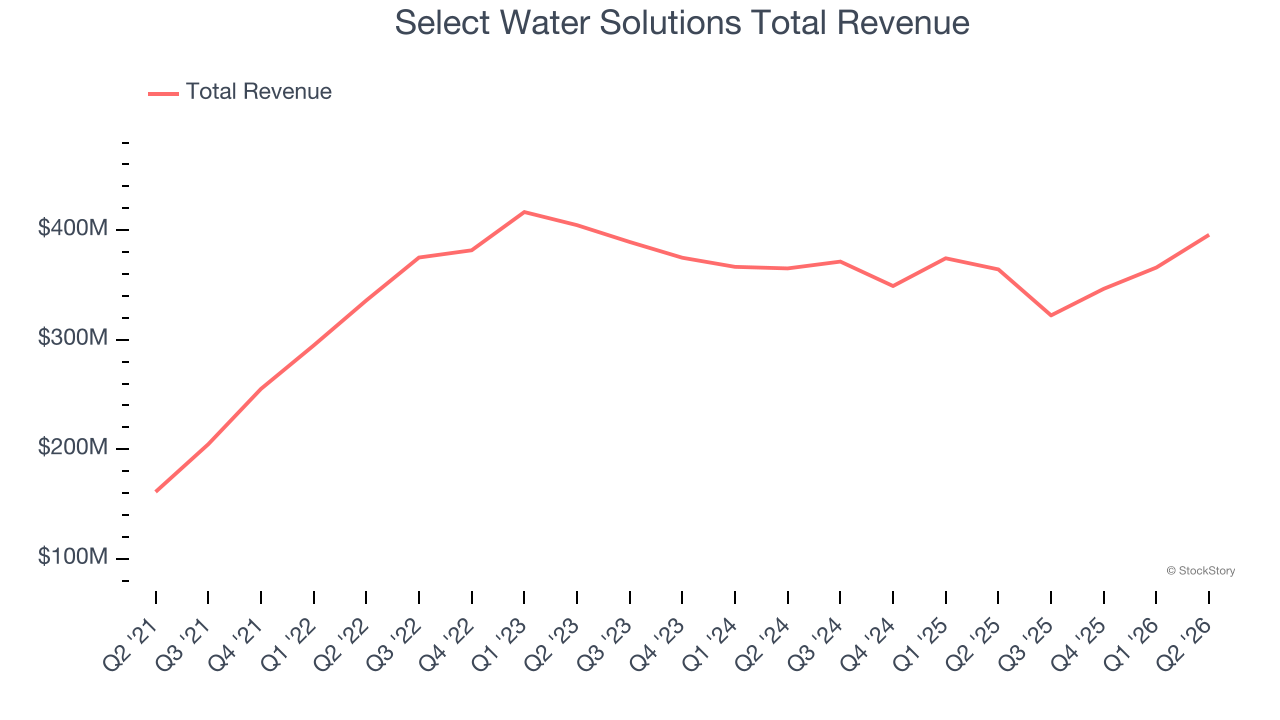
The market seems happy with the results as the stock is up 10.6% since reporting. It currently trades at $20.46.
Is now the time to buy Select Water Solutions? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: ProPetro (NYSE: PUMP)
Operating exclusively in the Permian Basin—one of America's most prolific oil-producing regions—ProPetro (NYSE: PUMP) provides hydraulic fracturing services that pump high-pressure fluid and sand into oil wells to release trapped hydrocarbons.
ProPetro reported revenues of $305.8 million, down 6.2% year on year, falling short of analysts’ expectations by 1.6%. It was a disappointing quarter as it posted a significant miss of analysts’ EBITDA and EPS estimates.
As expected, the stock is down 4.6% since the results and currently trades at $10.17.
Read our full analysis of ProPetro’s results here.
RPC (NYSE: RES)
Operating primarily in the Permian Basin with 10 hydraulic fracturing fleets, RPC (NYSE: RES) provides specialized services and equipment like hydraulic fracturing, coiled tubing, and cementing to help oil and gas companies complete and maintain wells.
RPC reported revenues of $460.9 million, up 9.5% year on year. This result surpassed analysts’ expectations by 1.1%. Overall, it was a stunning quarter as it also produced a beat of analysts’ EPS and EBITDA estimates.
The stock is up 12.6% since reporting and currently trades at $5.77.
Read our full, actionable report on RPC here, it’s free.
Expro (NYSE: XPRO)
Operating in over 50 countries from deepwater offshore platforms to remote onshore fields, Expro (NYSE: XPRO) provides equipment and services that help oil and gas companies drill wells, measure production, and maintain well integrity.
Expro reported revenues of $393.2 million, down 7% year on year. This number beat analysts’ expectations by 3%. More broadly, it was a slower quarter as it recorded a significant miss of analysts’ EPS and EBITDA estimates.
The stock is up 4.8% since reporting and currently trades at $16.42.
Read our full, actionable report on Expro here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.