Clean Energy Fuels’s stock price has taken a beating over the past six months, shedding 23.1% of its value and falling to $1.70 per share. This may have investors wondering how to approach the situation.
Is now the time to buy Clean Energy Fuels, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Clean Energy Fuels Will Underperform?
Even with the cheaper entry price, we don’t have much confidence in Clean Energy Fuels. Here are three reasons why CLNE doesn’t excite us, plus one stock we’d rather own.
1. Fewer Distribution Channels Limit Its Ceiling
In Energy, scale separates fragile single-asset producers from platform-style businesses that generate revenue across entire basins and infrastructure networks.
Clean Energy Fuels’s $442.4 million of revenue in the last year is pretty small for the industry, suggesting the company is a subscale business in an industry where scale matters.
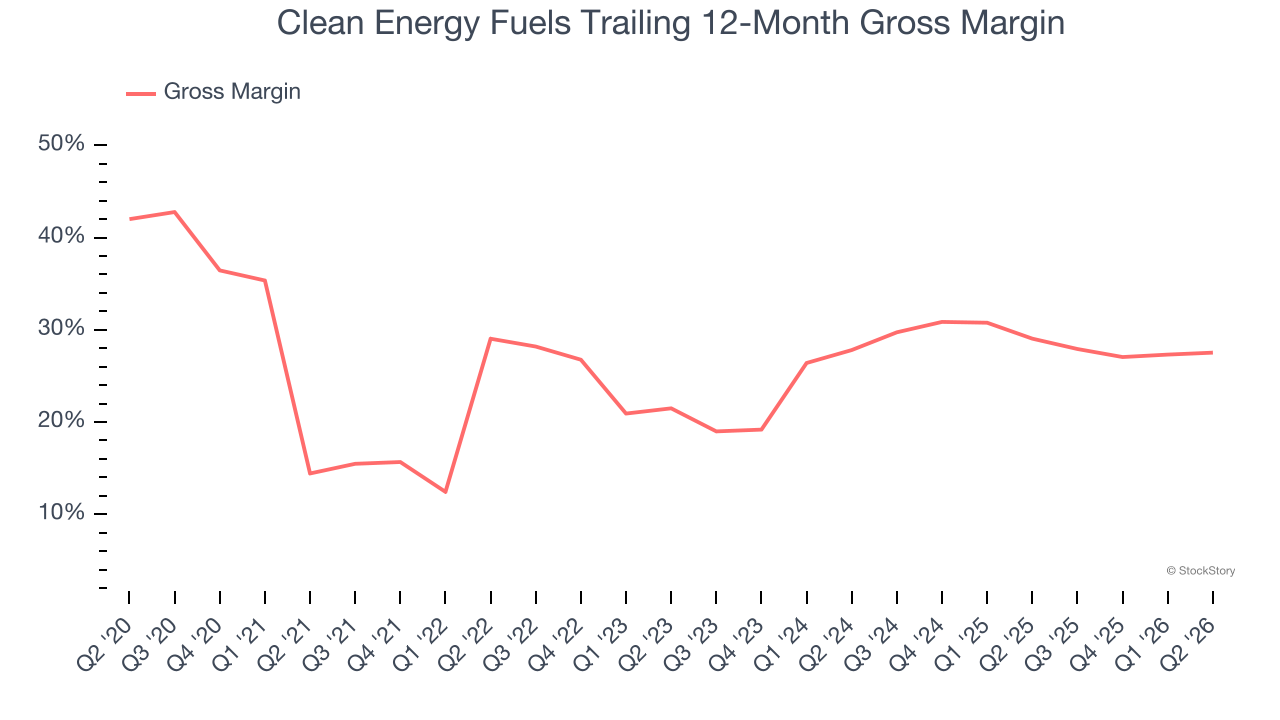
2. Low Gross Margin Reveals Weak Structural Profitability
While energy gross margins can be distorted by commodity prices, hedging, and short-term cost swings, sustained margins across a full cycle reflect a producer’s underlying asset quality, infrastructure position, and cost structure.
Clean Energy Fuels, which averaged 26.8% gross margin over the last five years, exhibited bottom-tier unit economics in the sector. It means the company will struggle at higher commodity prices than peers with better gross margins.
3. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
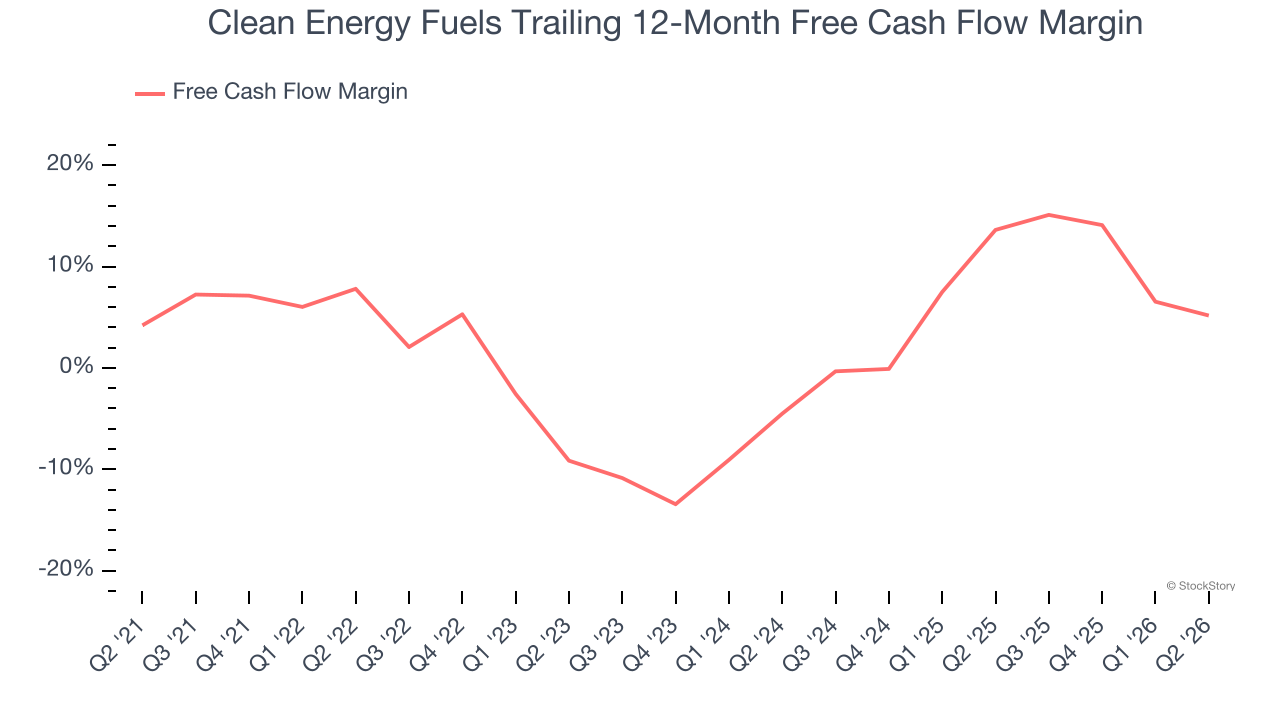
Clean Energy Fuels has shown weak cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 2.3%, below what we’d expect for an upstream and integrated energy business.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Clean Energy Fuels, we’ll be cheering from the sidelines. Following the recent decline, the stock trades at 6.9× forward EV-to-EBITDA (or $1.70 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better investments elsewhere. Let us point you toward the most entrenched endpoint security platform on the market.
Stocks We Like More Than Clean Energy Fuels
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.