Energy Recovery has gotten torched over the last six months - since March 2026, its stock price has dropped 30.1% to $7.07 per share. This was partly due to its softer quarterly results and might have investors contemplating their next move.
Is now the time to buy Energy Recovery, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Energy Recovery Not Exciting?
Despite the more favorable entry price, we’re passing on Energy Recovery for now. Here are three reasons we avoid ERII, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
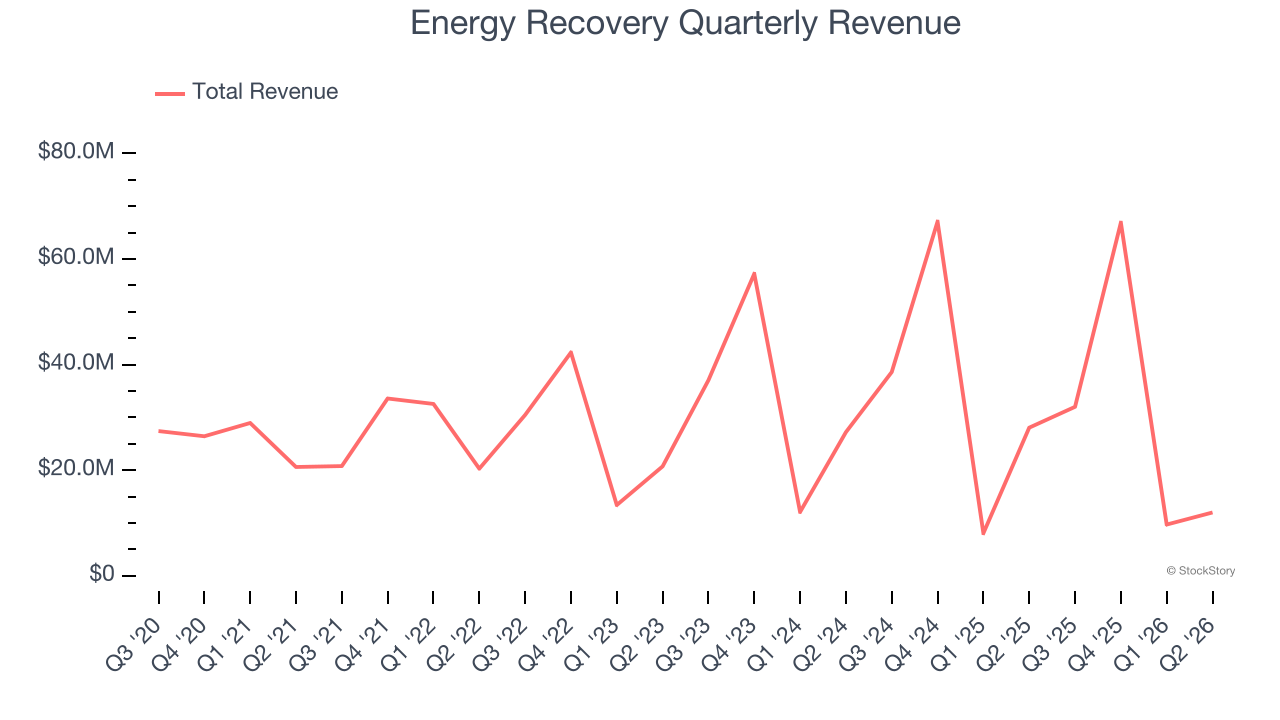
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Unfortunately, Energy Recovery’s 3.1% annualized revenue growth over the last five years was sluggish. This fell short of our benchmark for the industrials sector.
2. Revenue Projections Show Stormy Skies Ahead
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Energy Recovery’s revenue to drop by 36.2%, a decrease from its 3.1% annualized growth for the past five years. This projection doesn’t excite us and suggests its products and services will see some demand headwinds.
3. EPS Growth Has Stalled Over the Last Two Years
While long-term earnings trends give us the big picture, we also track EPS over a shorter period because it can provide insight into an emerging theme or development for the business.
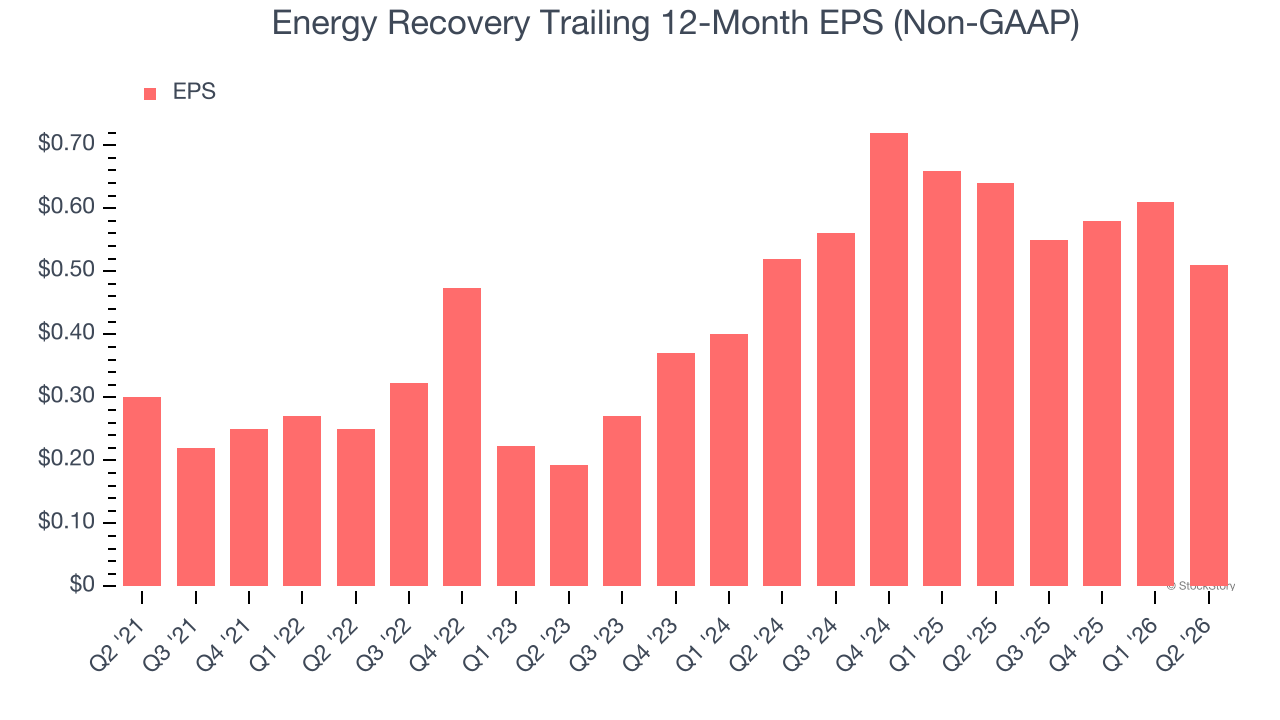
Energy Recovery’s flat EPS over the last two years was weak.
Final Judgment
Energy Recovery isn’t a terrible business, but it doesn’t pass our quality test. After the recent drawdown, the stock trades at 1,398× forward P/E (or $7.07 per share). At this valuation, there’s a lot of good news priced in - we think other companies feature superior fundamentals at the moment. We’d recommend looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks We Like More Than Energy Recovery
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.