

Let’s dig into the relative performance of Weatherford (NASDAQ: WFRD) and its peers as we unravel the now-completed Q2 mixed or offshore upstream e&p earnings season.
This category includes smaller or niche E&P companies operating in specialized basins, geographies, or resource types outside major classifications. These firms may target unconventional resources, frontier regions, or specific commodity niches. Tailwinds include potential for outsized returns from successful exploration, acquisition opportunities during industry downturns, and specialized expertise commanding premium valuations. Headwinds include higher operational and geological risks, limited scale reducing negotiating power and cost efficiencies, and constrained capital market access during challenging commodity environments. Regulatory risks and ESG concerns may disproportionately affect smaller operators with fewer resources for compliance.
The 21 mixed or offshore upstream e&p stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 8%.
Thankfully, share prices of the companies have been resilient as they are up 8.6% on average since the latest earnings results.
Weatherford (NASDAQ: WFRD)
Operating in roughly 75 countries with over 300 facilities worldwide, Weatherford (NASDAQ: WFRD) provides equipment and services for drilling, completing, and maintaining oil and gas wells.
Weatherford reported revenues of $1.11 billion, down 8.2% year on year. This print exceeded analysts’ expectations by 3.4%. Despite the top-line beat, it was still a slower quarter for the company with a significant miss of analysts’ EPS estimates.
Girish Saligram, President and Chief Executive Officer, commented, “Despite the significant disruption in the Middle East due to the Iran conflict, our second-quarter results, especially adjusted free cash flow, were strong, demonstrating the reliability and resilience of our operating paradigm. I am proud of the One Weatherford team for coming together to deliver once again."
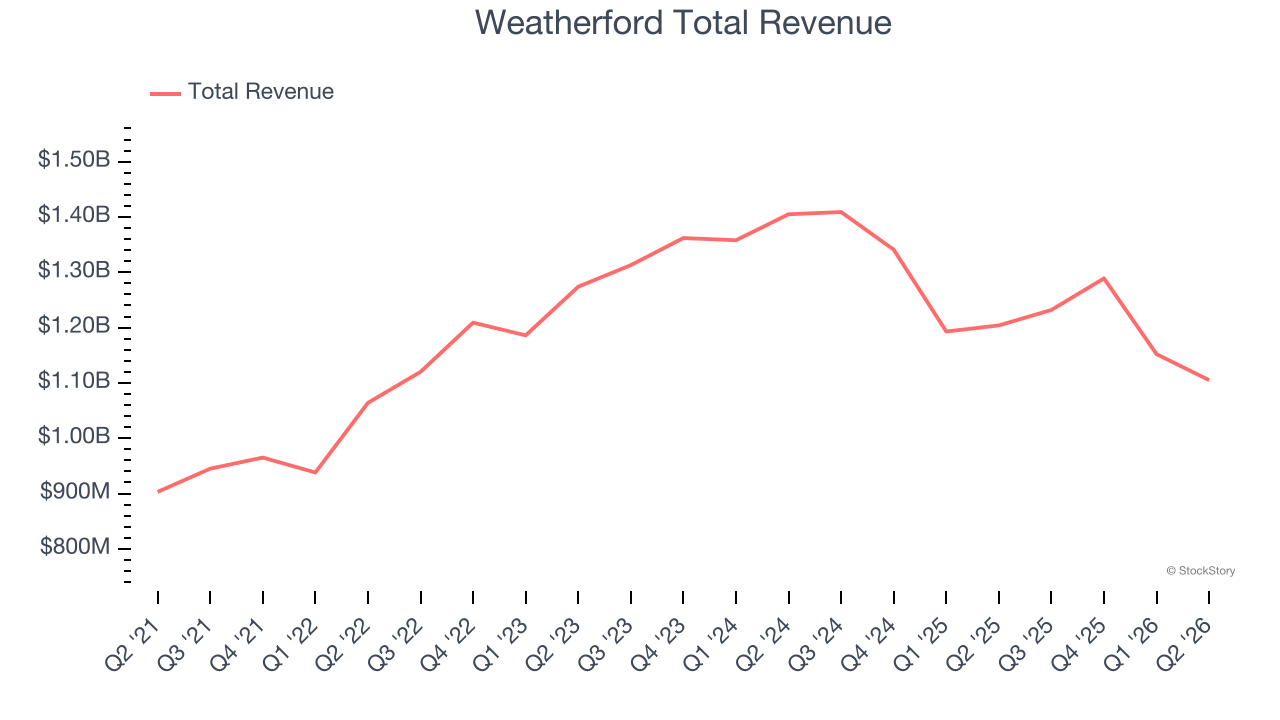
The market seems disappointed with the results as the stock is down 1.5% since reporting and currently trades at $82.04.
Read our full report on Weatherford here, it’s free.
Best Q2: Granite Ridge Resources (NYSE: GRNT)
Operating without drilling rigs or field crews of its own, Granite Ridge Resources (NYSE: GRNT) owns interests in oil and natural gas wells across six major US shale basins.
Granite Ridge Resources reported revenues of $149.3 million, up 36.7% year on year, outperforming analysts’ expectations by 5.7%. The business had an incredible quarter with a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
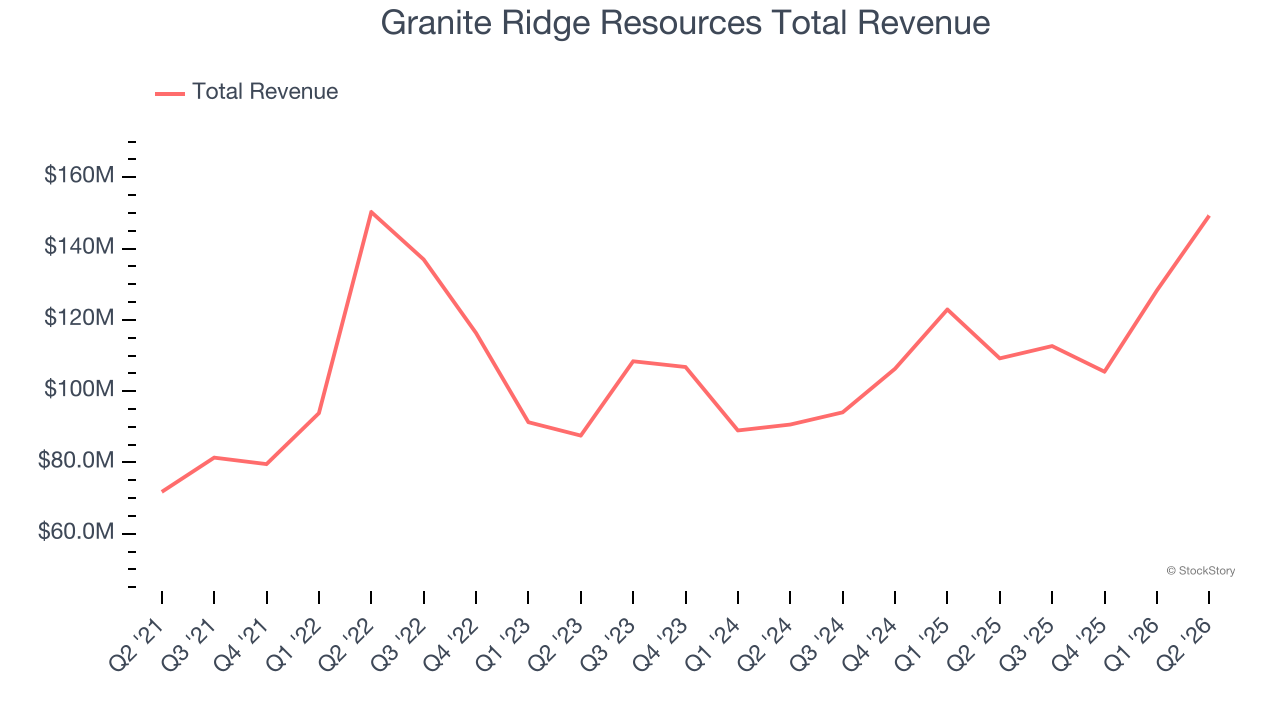
The market seems happy with the results as the stock is up 5.9% since reporting. It currently trades at $4.94.
Is now the time to buy Granite Ridge Resources? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Peabody Energy (NYSE: BTU)
Beginning with a single wagon hauling coal in Illinois back when Grover Cleveland was president, Peabody Energy (NYSE: BTU) mines coal used by electricity generators and steel manufacturers.
Peabody Energy reported revenues of $1.00 billion, up 12.7% year on year, in line with analysts’ expectations. It was a softer quarter as it posted a significant miss of analysts’ EPS estimates.
Interestingly, the stock is up 17.3% since the results and currently trades at $27.27.
Read our full analysis of Peabody Energy’s results here.
Tidewater (NYSE: TDW)
Operating one of the world's largest fleets with over 200 vessels spanning 30 countries, Tidewater (NYSE: TDW) operates offshore service vessels that transport supplies, equipment, and workers to oil rigs and platforms.
Tidewater reported revenues of $342.3 million, flat year on year. This print topped analysts’ expectations by 4.8%. It was a very strong quarter as it also logged a solid beat of analysts’ EBITDA estimates and a beat of analysts’ EPS estimates.
The stock is up 24.1% since reporting and currently trades at $88.74.
Read our full, actionable report on Tidewater here, it’s free.
Green Plains (NASDAQ: GPRE)
Operating one of North America's largest ethanol platforms with capacity to process 310 million bushels of corn annually, Green Plains (NASDAQ: GPRE) operates ten biorefineries that convert corn into ethanol for fuel, distillers grains for animal feed, and renewable corn oil.
Green Plains reported revenues of $446.2 million, down 19.3% year on year. This result lagged analysts’ expectations by 20.3%. Zooming out, it was actually a satisfactory quarter as it recorded a beat of analysts’ EPS estimates.
Green Plains had the weakest performance against analyst estimates in the group. The stock is down 8.6% since reporting and currently trades at $15.08.
Read our full, actionable report on Green Plains here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 6 Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.