
A company that generates cash isn’t automatically a winner. Some businesses stockpile cash but fail to reinvest wisely, limiting their ability to expand.
Luckily for you, we built StockStory to help you separate the good from the bad. That said, here is one cash-producing company that excels at turning cash into shareholder value and two best left off your watchlist.
Two Stocks to Sell:
UFP Technologies (UFPT)
Trailing 12-Month Free Cash Flow Margin: 9.7%
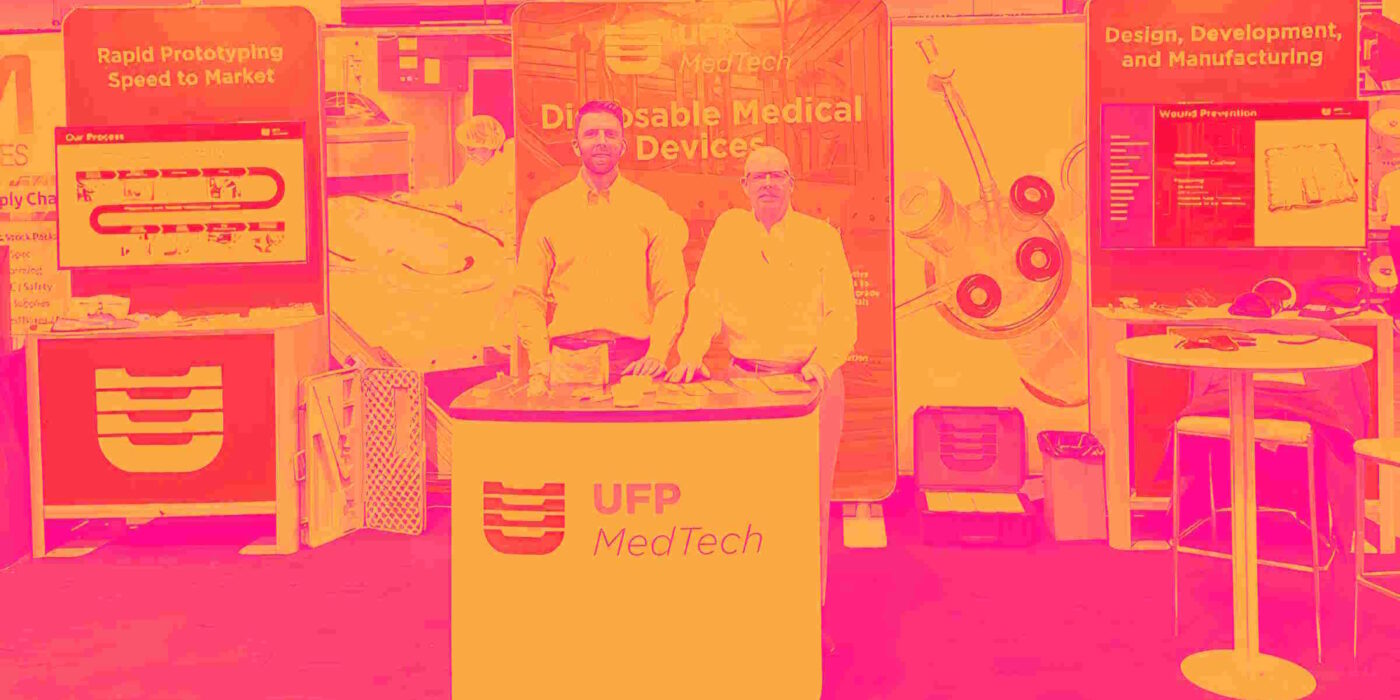
With expertise dating back to 1963 in specialized materials and precision manufacturing, UFP Technologies (NASDAQ: UFPT) designs and manufactures custom solutions for medical devices, sterile packaging, and other highly engineered products for healthcare and industrial applications.
Why Does UFPT Fall Short?
- Modest revenue base of $631.6 million gives it less fixed cost leverage and fewer distribution channels than larger companies
- Adjusted operating margin was unchanged over the last two years, suggesting it failed to gain leverage on its fixed costs
At $276.09 per share, UFP Technologies trades at 25.7x forward P/E. Dive into our free research report to see why there are better opportunities than UFPT.
Insight Enterprises (NSIT)
Trailing 12-Month Free Cash Flow Margin: 4.6%
With over 35 years of IT expertise and partnerships with more than 8,000 technology providers, Insight Enterprises (NASDAQ: NSIT) provides end-to-end digital transformation solutions that help businesses modernize their IT infrastructure and maximize the value of technology.
Why Does NSIT Worry Us?
- Sales stagnated over the last five years and signal the need for new growth strategies
- Lacking free cash flow generation means it has few chances to reinvest for growth, repurchase shares, or distribute capital
- Diminishing returns on capital suggest its earlier profit pools are drying up
Insight Enterprises’s stock price of $159.58 implies a valuation ratio of 13.1x forward P/E. Check out our free in-depth research report to learn more about why NSIT doesn’t pass our bar.
One Stock to Buy:
Cintas (CTAS)
Trailing 12-Month Free Cash Flow Margin: 16.7%
Starting as a family business collecting and cleaning shop rags in Cincinnati, Cintas (NASDAQ: CTAS) provides corporate identity uniforms, facility services, and safety products to over one million businesses across North America.
What Makes CTAS Stand Out?
- Impressive 9.6% annual revenue growth over the last five years indicates it’s winning market share this cycle
- Strong free cash flow margin of 16.4% enables it to reinvest or return capital consistently
- Market-beating returns on capital illustrate that management has a knack for investing in profitable ventures, and its returns are climbing as it finds even more attractive growth opportunities
Cintas is trading at $197.41 per share, or 36.3x forward P/E. Is now the time to initiate a position? Find out in our full research report, it’s free.
Stocks We Like Even More
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that made our list in 2020 include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.