Renewable energy and infrastructure solutions provider Gibraltar Industries (NASDAQ: ROCK) fell short of the market’s revenue expectations in Q3 2026, but revenue rose 54.2% year on year to $479.6 million. The company’s full-year revenue guidance of $1.65 billion at the midpoint came in 7.8% below analysts’ consensus estimates. Its non-GAAP profit of $1.01 per share was 16% below analysts’ consensus estimates.
For more on Gibraltar, read our free full research report.
Gibraltar (ROCK) Q3 2026 highlights:
- Revenue $479.6 million vs S&P analysts’ consensus estimates of $487.6 million (54.2% year-on-year growth, 1.6% miss)
- Adjusted EPS $1.01 vs S&P analysts’ consensus estimates of $1.20 (16% miss)
- Adjusted EBITDA $83.5 million vs analysts’ consensus estimates of $89.25 million (17.4% margin, 6.4% miss)
- Revenue guidance The company lowered its full-year revenue guidance to $1.65 billion at the midpoint from $1.80 billion, an 8.1% decrease
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $2.33 at the midpoint, a 39.6% decrease
- Operating margin 10.3%, down from 13.5% in the same quarter last year
- Free cash flow -$3.13 million, down from $64.77 million in the same quarter last year
- Market capitalization $1.29 billion
“Our residential business delivered solid revenue and margin performance in an end market that declined 13% in the quarter, slowing more than 2.5 times our expectation going into the quarter. Despite sector weakness, our Residential business generated organic growth of 3.1% and delivered 18.9% adjusted EBITDA margin. Sequentially, we held margin flat despite revenue decreasing 6.3% and the incremental inflation absorbed in the quarter across steel, logistics, and fuel. Our Agtech business was impacted by two large controlled environmental agriculture (CEA) project delays resulting in a significant shift of revenue and margin out of the quarter. One of these projects has recently received permitting approval and we expect the second project to receive approval in December,” stated Chairman and CEO Bill Bosway.
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Over the last five years, Gibraltar grew its revenue at a tepid 4.9% compounded annual growth rate, falling short of the industrials sector standard.
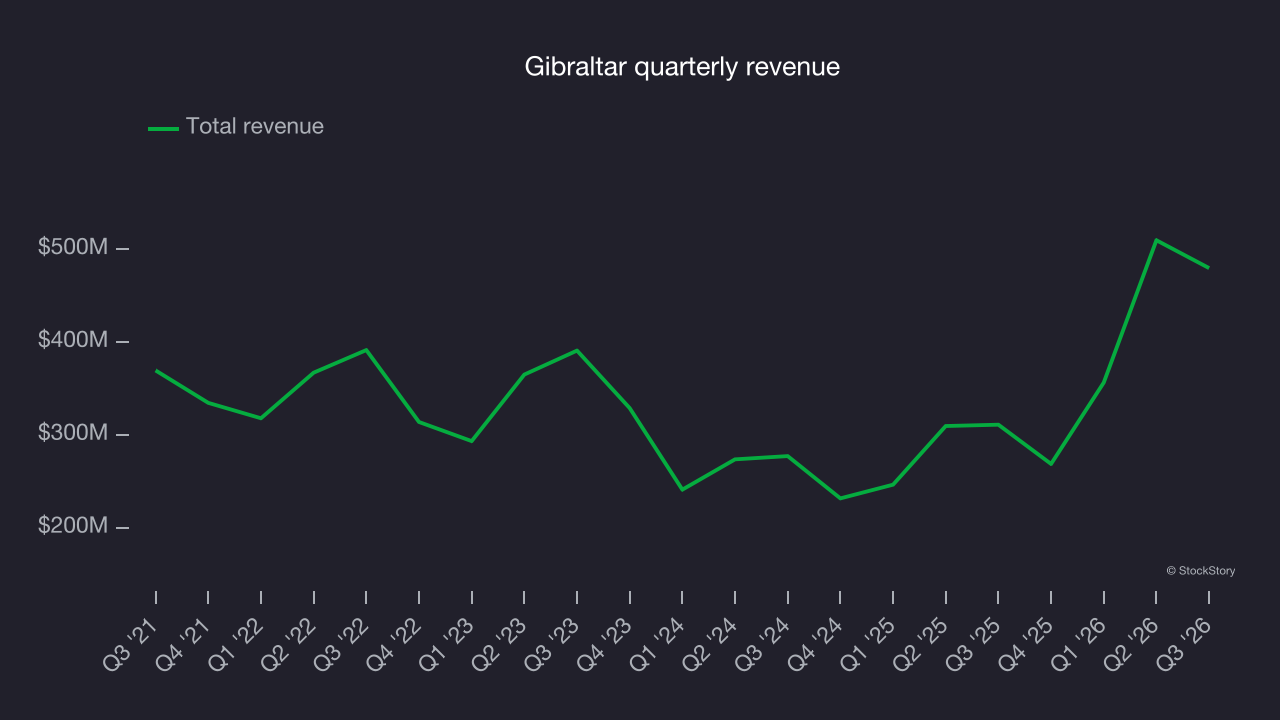
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Gibraltar’s annualized revenue growth of 20% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 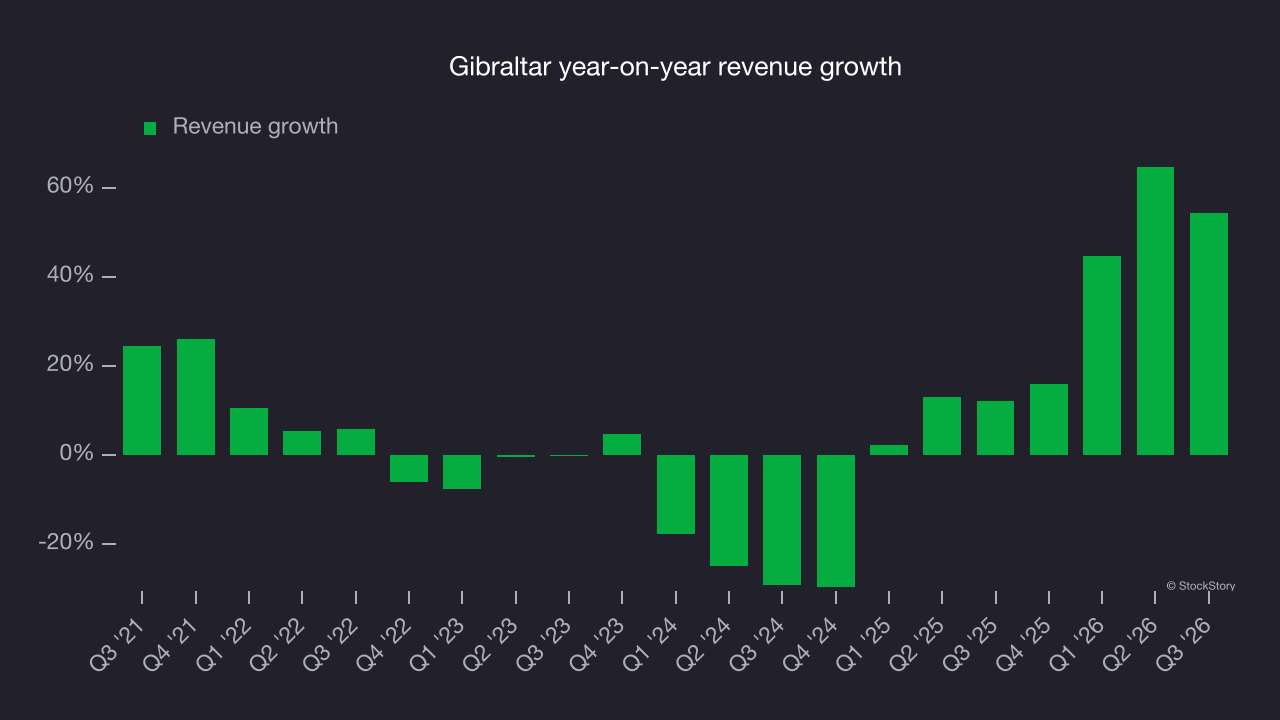
This quarter, Gibraltar’s revenue grew 54.2% year on year, but its $479.6 million in revenue fell short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 15.4% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, this projection is strong and suggests the market expects success for its products and services.
Operating margin
Gibraltar’s operating margin has generally stayed the same over the last 12 months, averaging 11.3% over the last five years. This profitability was solid for an industrials business and shows it’s an efficient company that manages its expenses well. This result was particularly notable given its low gross margin, which largely reflects what it sells and requires substantial shifts to change meaningfully. Companies have more control over their operating margins, and high operating margins alongside low gross margins point to well-managed operations.
Looking at the trend in its profitability, Gibraltar’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. Margin expansion would be preferable, but Gibraltar’s performance held up well considering most home construction materials companies saw their margins decline.
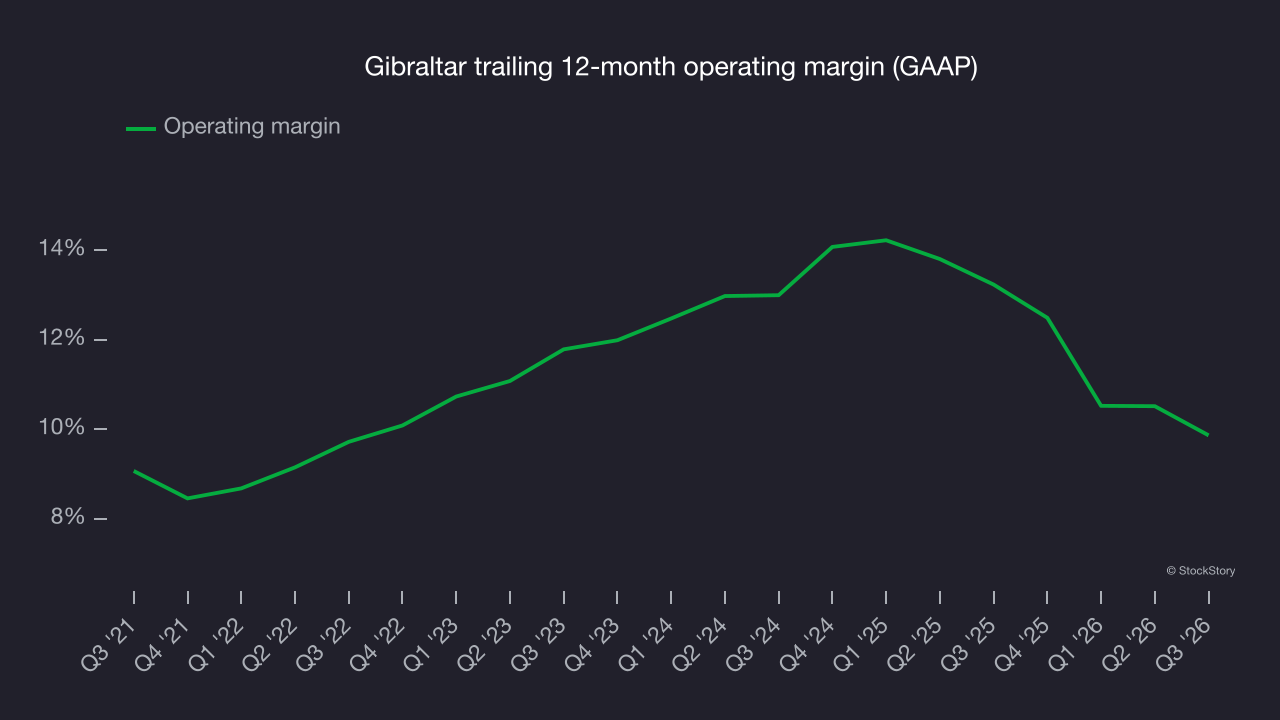
This quarter, Gibraltar generated an operating margin of 10.3%, down 3.2 percentage points year on year. Gibraltar’s operating margin decreased more than its gross margin, suggesting it was less efficient as expenses such as marketing, R&D and administrative overhead increased.
Earnings per share
Long-term changes in earnings per share, or EPS, matter for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Gibraltar’s weak 3.3% annual EPS growth over the last five years aligns with its revenue performance, indicating it maintained its per-share profitability as it expanded.
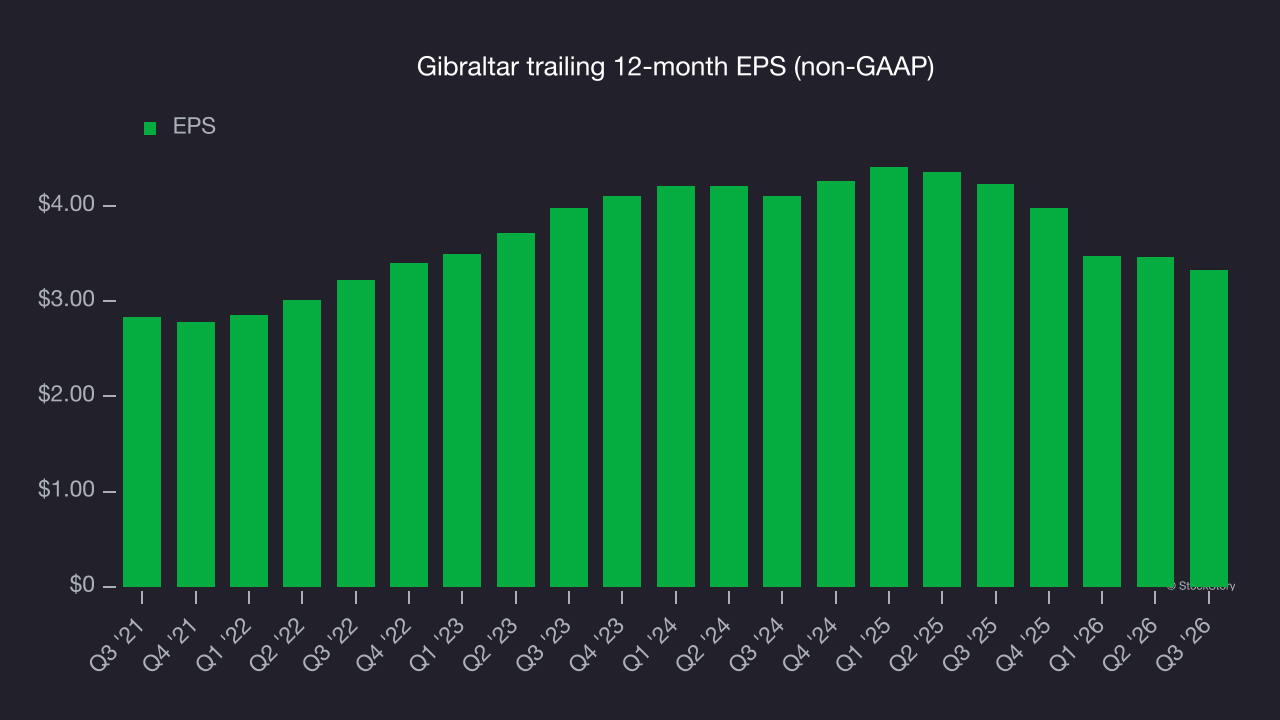
As with revenue, examining EPS over a shorter period can reveal changes in the business.
Gibraltar’s EPS declined 9.9% annually over the last two years, a poor result that trailed its 20% two-year revenue growth.
A closer look at Gibraltar’s earnings helps explain the drivers of its performance. Gibraltar’s operating margin has declined over the last two years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, Gibraltar reported adjusted EPS of $1.01, down from $1.14 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects Gibraltar’s full-year EPS to grow 35.5% from $3.33 to $4.51, according to S&P.
Key takeaways from Gibraltar’s Q3 results
Gibraltar’s full-year outlook fell short of Wall Street’s consensus estimates for both revenue and EPS, leaving few positives in a softer quarter. Shares plunged 23% to $33.56 immediately after the results.
Gibraltar’s latest quarter was underwhelming. One earnings report doesn’t define a company’s quality, though, so assessing the stock at its current price requires a broader view. That includes its valuation, business quality and latest quarterly results. For more on those factors, read our full research report here (it’s free).