Energy drink company Celsius (NASDAQ: CELH) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 16.8% year on year to $847.2 million. Its non-GAAP profit of $0.41 per share was 21.6% above analysts’ consensus estimates.
For more on Celsius, read the full research report for free.
Celsius (CELH) Q3 2026 highlights:
- Revenue $847.2 million vs S&P analysts’ consensus estimates of $795.5 million (16.8% year-on-year growth, 6.5% beat)
- Adjusted EPS $0.41 vs S&P analysts’ consensus estimates of $0.34 (21.6% beat)
- Adjusted EBITDA $198.6 million vs analysts’ consensus estimates of $168.6 million (23.4% margin, 17.8% beat)
- Operating margin 20.3%, up from -11% in the same quarter last year
- Market capitalization $7.78 billion
John Fieldly, Chairman and CEO of Celsius Holdings, said: “We delivered record quarterly revenue in the third quarter of 2026, reflecting the strength of our scaled, multi-brand Modern Energy platform and continued execution of our total energy portfolio strategy. We continued to make progress to improve CELSIUS brand performance, while advancing operational execution across the portfolio. With today’s brand-led leadership appointments, including welcoming Alex Zigliara to lead brand CELSIUS and appointing Rishi Daing to lead Rockstar Energy & Emerging Growth, we are further strengthening execution against our priorities: realizing the benefits of our integrated platform, improving margins through revenue growth management, supply chain and cost initiatives, and positioning each brand for sustainable growth.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can report a good quarter or two, but many enduring ones grow for years.
With $3.17 billion in revenue over the past 12 months, Celsius carries some recognizable products but is a mid-sized consumer staples company. Its size could bring disadvantages compared to larger competitors benefiting from better brand awareness and economies of scale. On the positive side, it can still achieve high growth rates because it’s working from a smaller revenue base.
Celsius grew its revenue at a strong 40.3% compounded annual growth rate over the last three years. This shows Celsius’s demand was higher than that of many consumer staples companies.
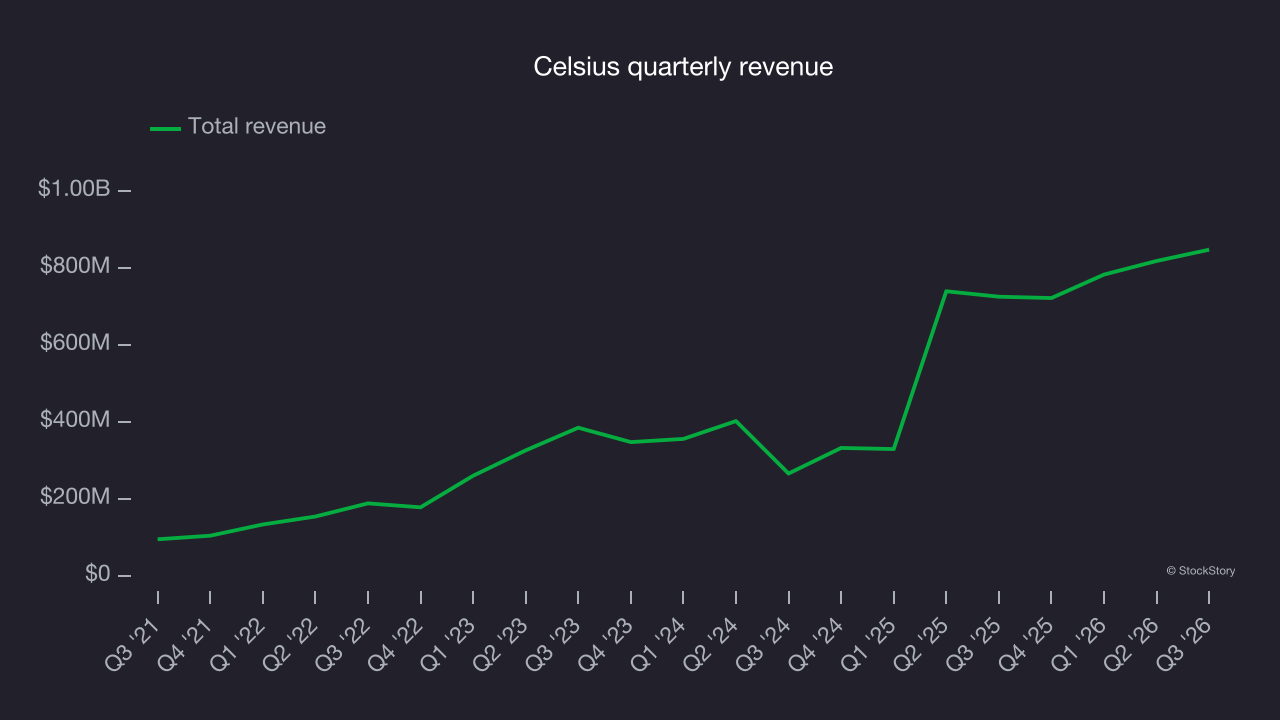
This quarter, Celsius reported year-on-year revenue growth of 16.8%, and its $847.2 million in revenue exceeded Wall Street’s consensus estimates by 6.5%.
Looking ahead, sell-side analysts expect revenue to grow 5.6% over the next 12 months, according to S&P, a deceleration versus the last three years. Despite the slowdown, this projection is above average for the sector and indicates the market is forecasting some success for its newer products.
Free cash flow
Free cash flow is a key measure because cash, not accounting profits, pays the bills.
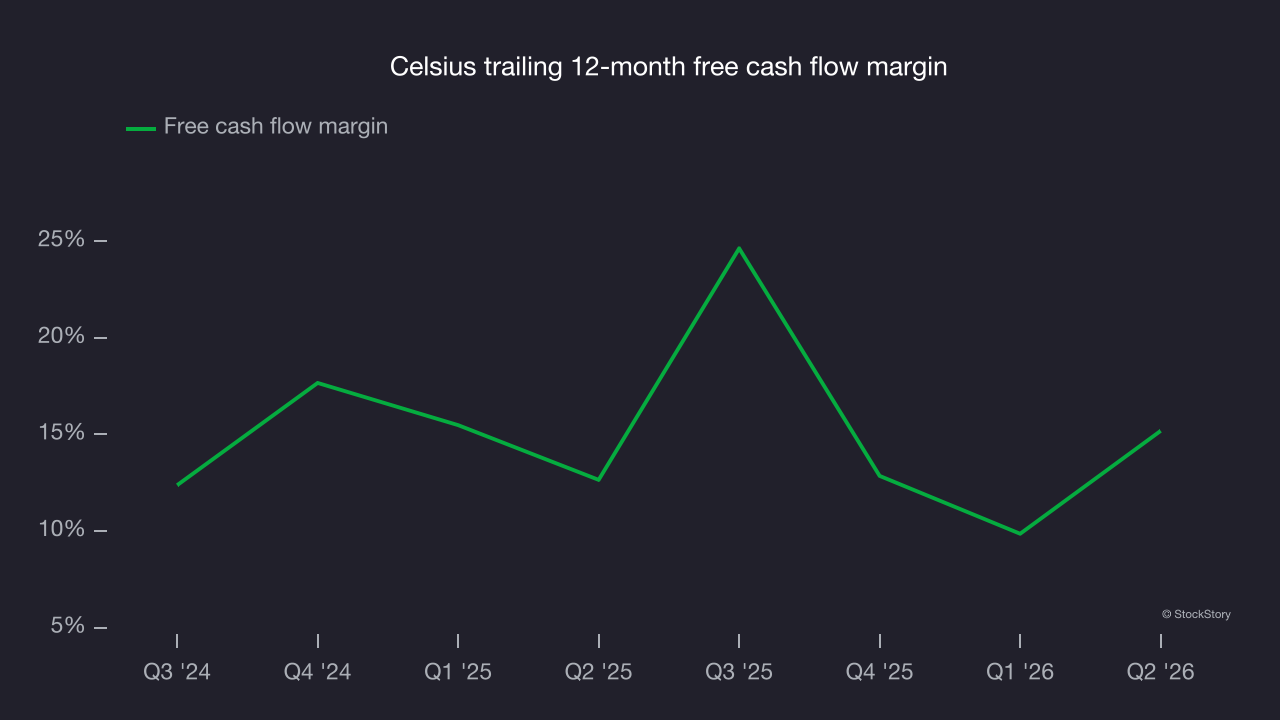
Celsius has shown strong cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors and stay ahead of the competition. The company’s free cash flow margin was among the best in the consumer staples sector, averaging 14.9% over the last two years.
Key takeaways from Celsius’s Q3 results
Celsius delivered sizable beats on both EBITDA and revenue versus Wall Street’s consensus estimates, but gross margin missed expectations. Those beats gave the quarter some important positives despite the margin shortfall. Shares surged 7.2% to $32.93 immediately after the report.
Celsius may have had a good quarter, but that alone doesn’t make the stock a buy. The latest quarter matters, but longer-term fundamentals and valuation are far more important when making that decision. For more on those factors, read our full research report here (it’s free).