Healthcare diagnostics company QuidelOrtho (NASDAQ: QDEL) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 11.6% year on year to $618.9 million. The company’s full-year revenue guidance of $2.53 billion at the midpoint came in 0.5% below analysts’ consensus estimates. Its non-GAAP profit of $0.31 per share was 73.8% above analysts’ consensus estimates.
For more on QuidelOrtho, read our free full research report.
QuidelOrtho (QDEL) Q3 2026 highlights:
- Revenue $618.9 million vs S&P analysts’ consensus estimates of $634.8 million (11.6% year-on-year decline, 2.5% miss)
- Adjusted EPS $0.31 vs S&P analysts’ consensus estimates of $0.18 (73.8% beat)
- Adjusted EBITDA $148 million vs analysts’ consensus estimates of $145.2 million (23.9% margin, 2% beat)
- Revenue guidance The company dropped its revenue guidance for the full year to $2.53 billion at the midpoint from $2.56 billion, a 1.2% decrease
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $0.68 at the midpoint, a 12.9% decrease
- EBITDA guidance $542.5 million at the midpoint for the full year, below analysts’ consensus estimates of $549.5 million
- Operating margin -1.2%, an increase from -101% in the same quarter last year
- Constant currency revenue fell 11.6% year on year (-4.6% in the same quarter last year)
- Market capitalization $962.1 million
"The underlying performance of our Labs and Immunohematology businesses remained solid in the third quarter, supported by the strength and durability of our customer relationships and our large global installed base," said Brian J. Blaser, President and Chief Executive Officer of QuidelOrtho. "While China and a softer respiratory season continue to pressure our results, we are taking decisive action to strengthen the Company through a new cost transformation and enterprise restructuring program. This program is designed to improve profitability and cash flow while evolving our operating model around the distinct needs of our customers and markets. We believe these actions will help mitigate near-term headwinds and position the Company for sustainable long-term growth."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. QuidelOrtho’s demand was weak over the last five years as its revenue fell at a 2.2% annual rate. That performance fell short of our standards and points to poor business quality.
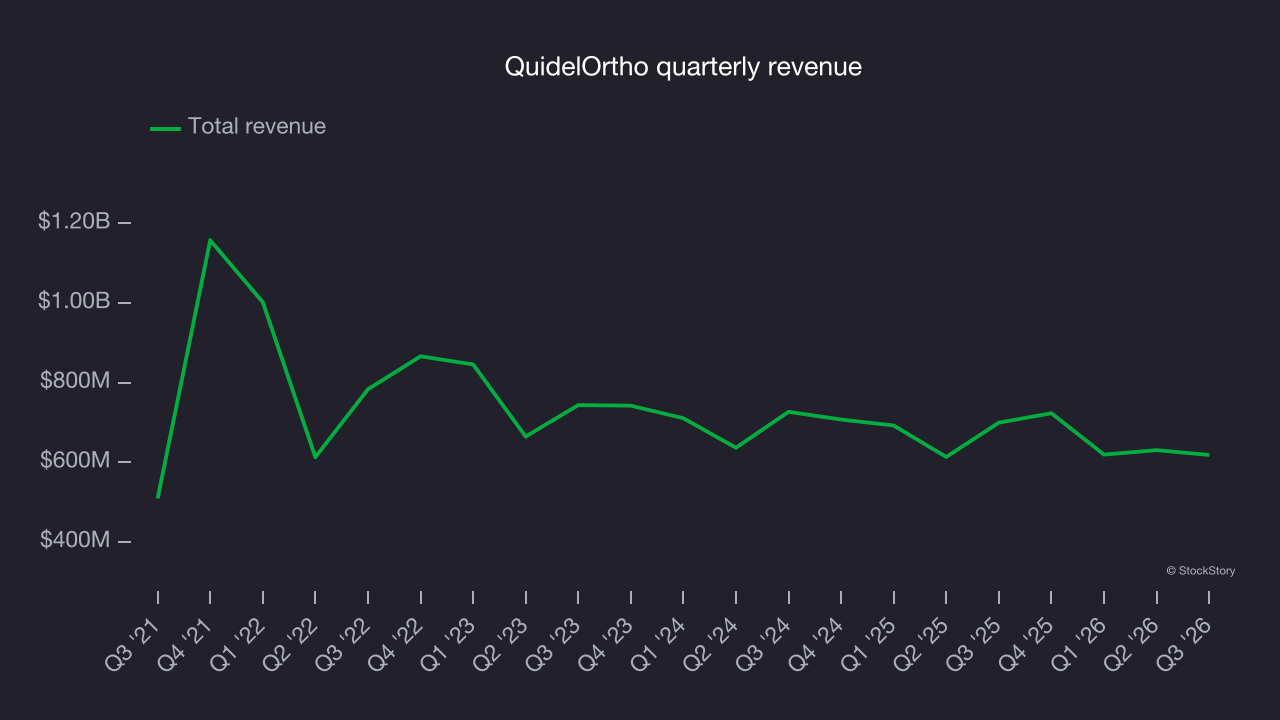
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. QuidelOrtho’s recent performance shows its demand remained suppressed as its revenue has declined by 4.1% annually over the last two years. 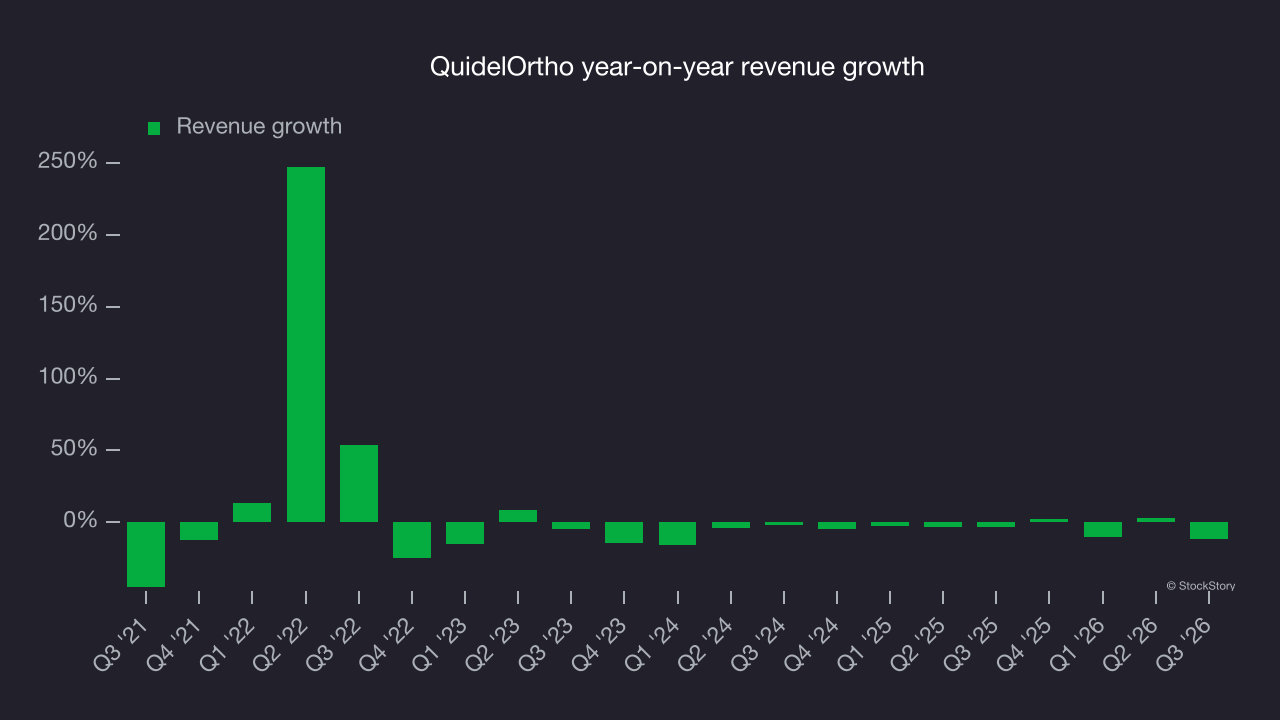
QuidelOrtho also reports revenue excluding currency movements, which are outside the company’s control and not indicative of demand. Over the last two years, its constant currency revenue averaged 4.2% year-on-year declines. This was in line with its reported revenue growth, indicating that foreign exchange has not had a meaningful impact on revenue. 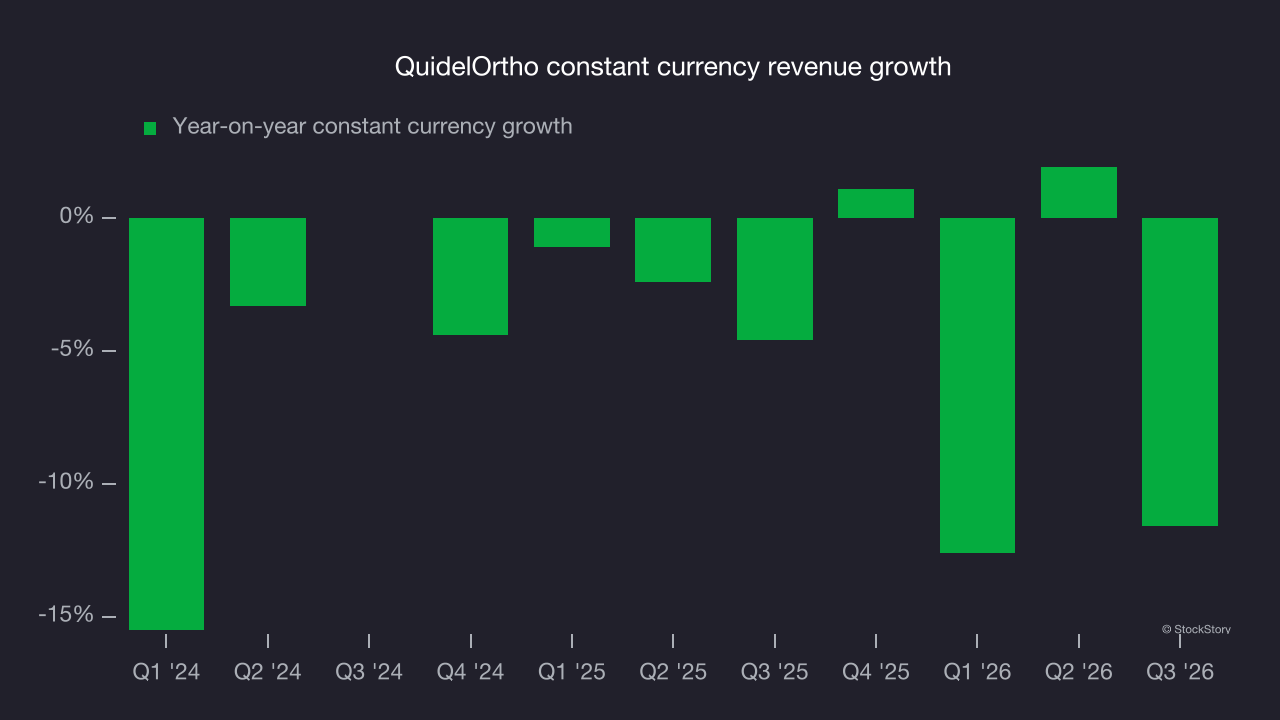
This quarter, QuidelOrtho missed Wall Street’s consensus estimates and reported an uninspiring 11.6% year-on-year revenue decline, generating $618.9 million of revenue.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P. Although this projection indicates its newer products and services will lead to better revenue performance, it is still below the sector average.
Adjusted operating margin
Adjusted operating margin is one of the best measures of profitability because it shows how much money a company retains after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to give a clearer picture of normalized profits.
QuidelOrtho has been an efficient company over the last five years. It was one of the more profitable businesses in the healthcare sector, with an average adjusted operating margin of 21%.
QuidelOrtho’s adjusted operating margin decreased by 37.9 percentage points over the last five years. The company’s two-year trajectory also shows it failed to return to peak profitability, as its margin fell by 6 percentage points. This poor performance shows its expenses were rising and it couldn’t pass those costs on to its customers.
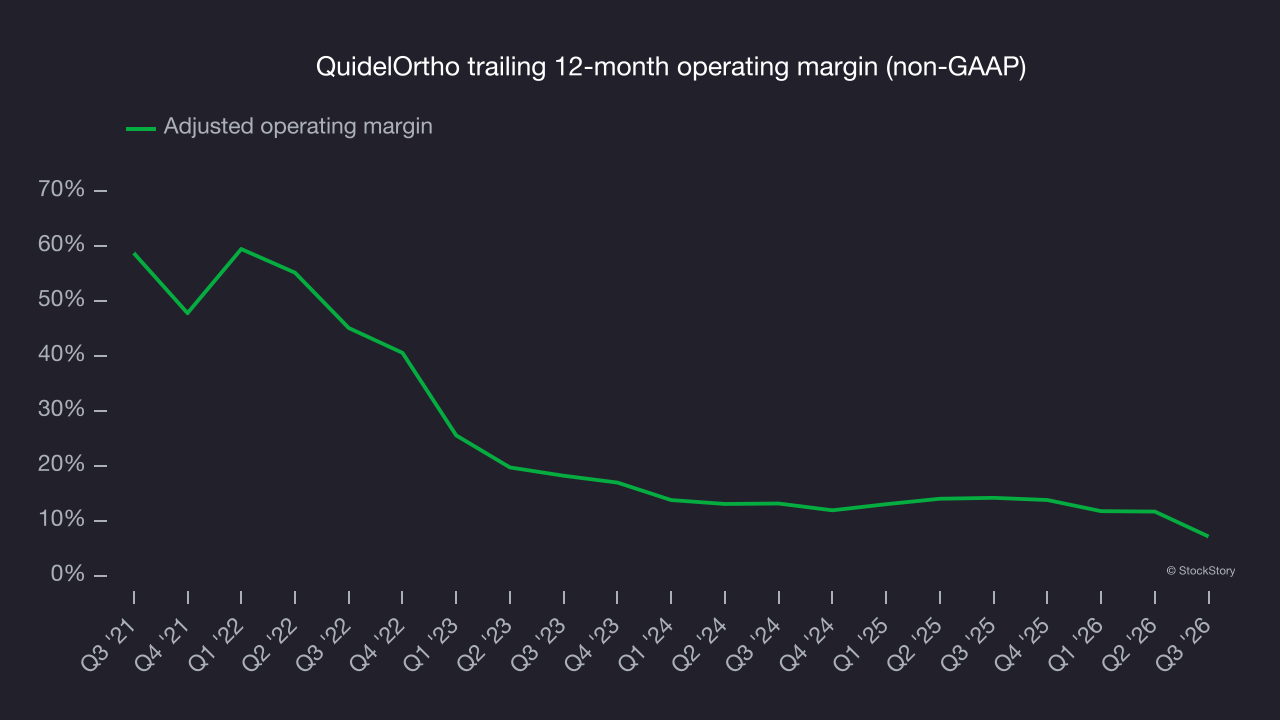
This quarter, QuidelOrtho generated an adjusted operating margin of negative 1.2%, down 18.3 percentage points year on year. This contraction shows it was less efficient because its expenses increased relative to its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
QuidelOrtho’s EPS declined by 47.5% annually over the last five years, more than its revenue. This indicates the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
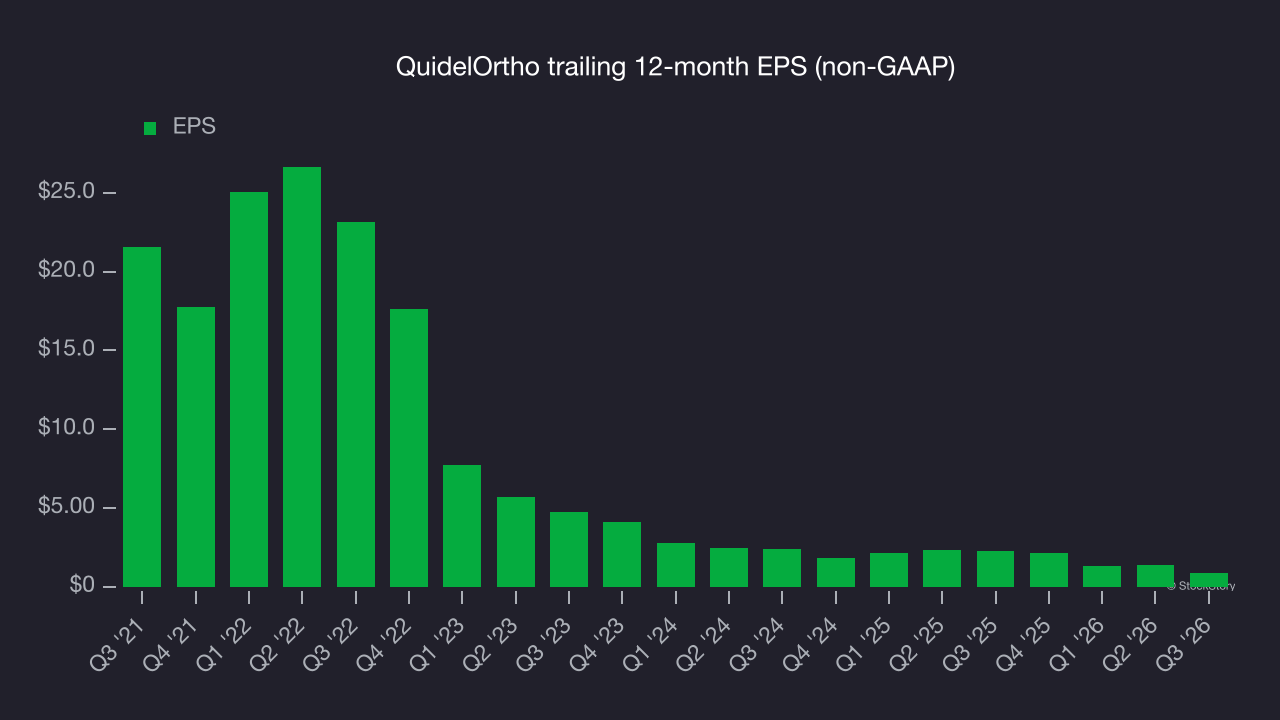
A closer look at QuidelOrtho’s earnings helps explain its performance. As noted earlier, QuidelOrtho’s adjusted operating margin declined by 37.9 percentage points over the last five years. Its share count also grew by 61.6%, meaning the company not only became less efficient with its operating expenses but also diluted its shareholders. 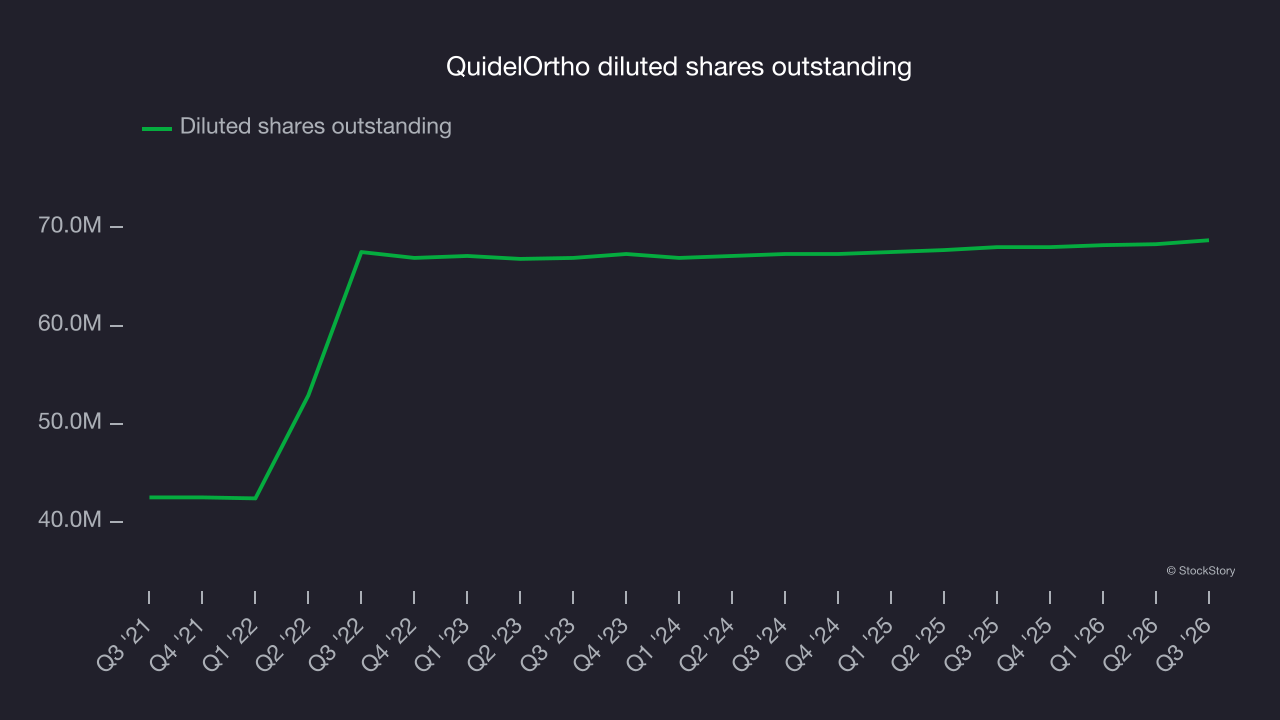
In Q3, QuidelOrtho reported adjusted EPS of $0.31, down from $0.80 in the same quarter last year. Despite falling year on year, the result easily cleared analysts’ consensus estimates. There is insufficient data to analyze expected EPS growth based on Wall Street analysts’ consensus projections.
Key takeaways from QuidelOrtho’s Q3 results
QuidelOrtho’s EPS beat analysts’ consensus estimates, but revenue fell short of Wall Street’s consensus and full-year EPS guidance missed expectations. The earnings beat was a positive in a quarter that otherwise could have been better. Shares plunged 10.6% to $12.63 immediately after the results.
QuidelOrtho underperformed this quarter, but that alone doesn’t determine its investment appeal. The latest quarter matters when deciding whether to invest in the stock, but not as much as longer-term business quality and valuation. For more on QuidelOrtho, read our full research report here (it’s free).