Home healthcare provider Addus HomeCare (NASDAQ: ADUS) met Wall Street’s revenue expectations in Q3 2026, with revenue up 7% year on year to $387.7 million. Its non-GAAP profit of $1.83 per share was 2.1% above analysts’ consensus estimates.
For more on Addus HomeCare, read our free full research report.
Addus HomeCare (ADUS) Q3 2026 highlights:
- Revenue $387.7 million vs S&P analysts’ consensus estimates of $388.7 million (7% year-on-year growth, in line)
- Adjusted EPS $1.83 vs S&P analysts’ consensus estimates of $1.79 (2.1% beat)
- Adjusted EBITDA $51.25 million vs analysts’ consensus estimates of $50.34 million (13.2% margin, 1.8% beat)
- Operating margin 10.3%, up from 9.1% in the same quarter last year
- Sales volumes were flat year on year (33.9% in the same quarter last year)
- Market capitalization $2.3 billion
Allison added, “Our business generated $40.9 million in operating cash flow during the third quarter, further bolstering our strong balance sheet. With low leverage and substantial availability under our revolving credit facility, we maintain significant liquidity and financial capacity to fund strategic growth investments, which includes the pending AccentCare personal care division acquisition. As we expand our multi-state footprint, we remain disciplined in identifying complementary opportunities that build market density and enhance operational scale.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Addus HomeCare’s revenue grew at a solid 12.4% compounded annual growth rate over the last five years. Its growth beat the average healthcare company and shows its offerings resonate with customers.
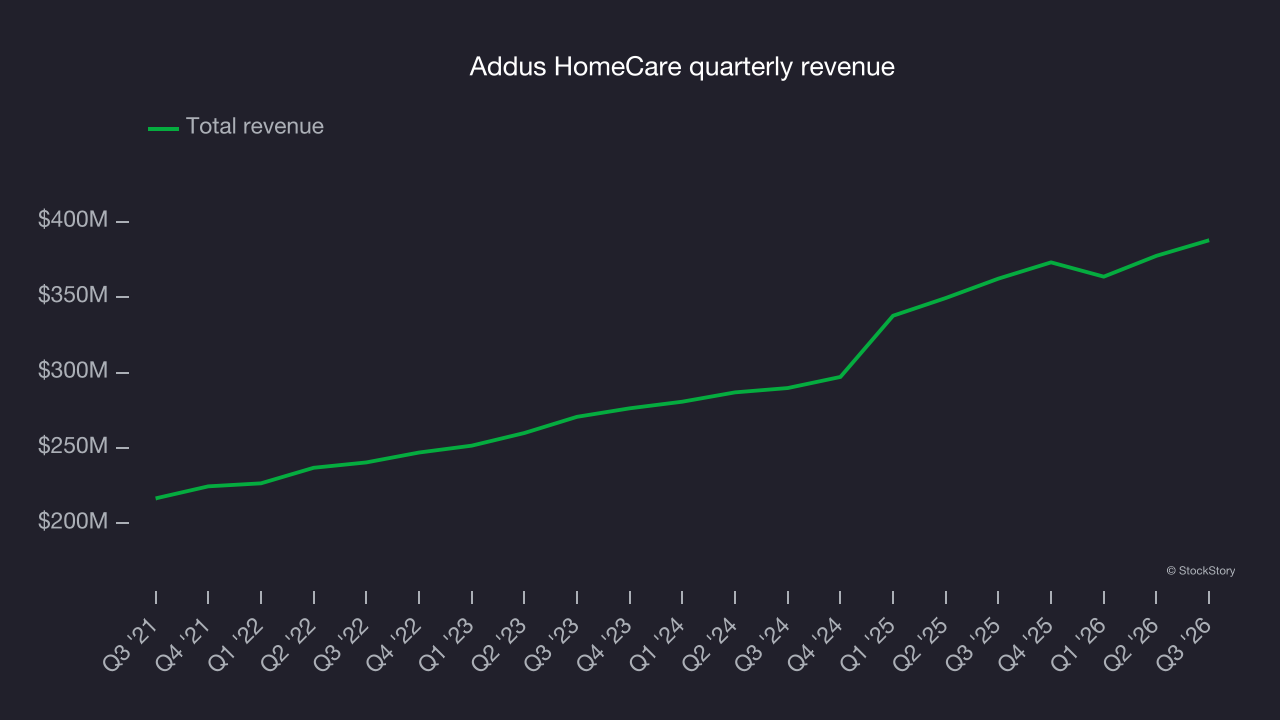
Long-term growth matters the most, but within healthcare, a half-decade historical view may miss recent innovations or disruptive industry trends. Addus HomeCare’s annualized revenue growth of 15.1% over the last two years is above its five-year trend, suggesting demand was strong and recently accelerated. 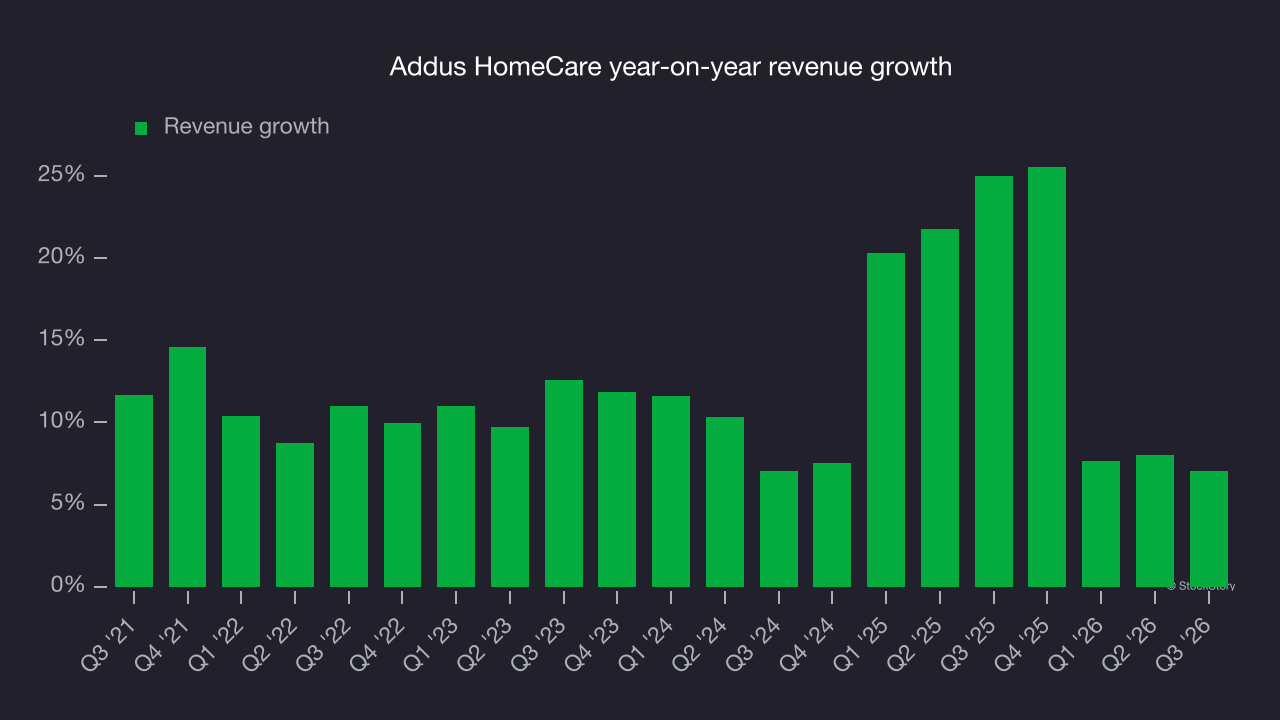
The company’s average billable patient count offers a closer look at its revenue dynamics and reached 50,948 in the latest quarter. Over the last two years, Addus HomeCare’s average billable patient count grew an average of 17% year on year. This outpaced revenue growth, indicating that the company’s average selling price decreased. 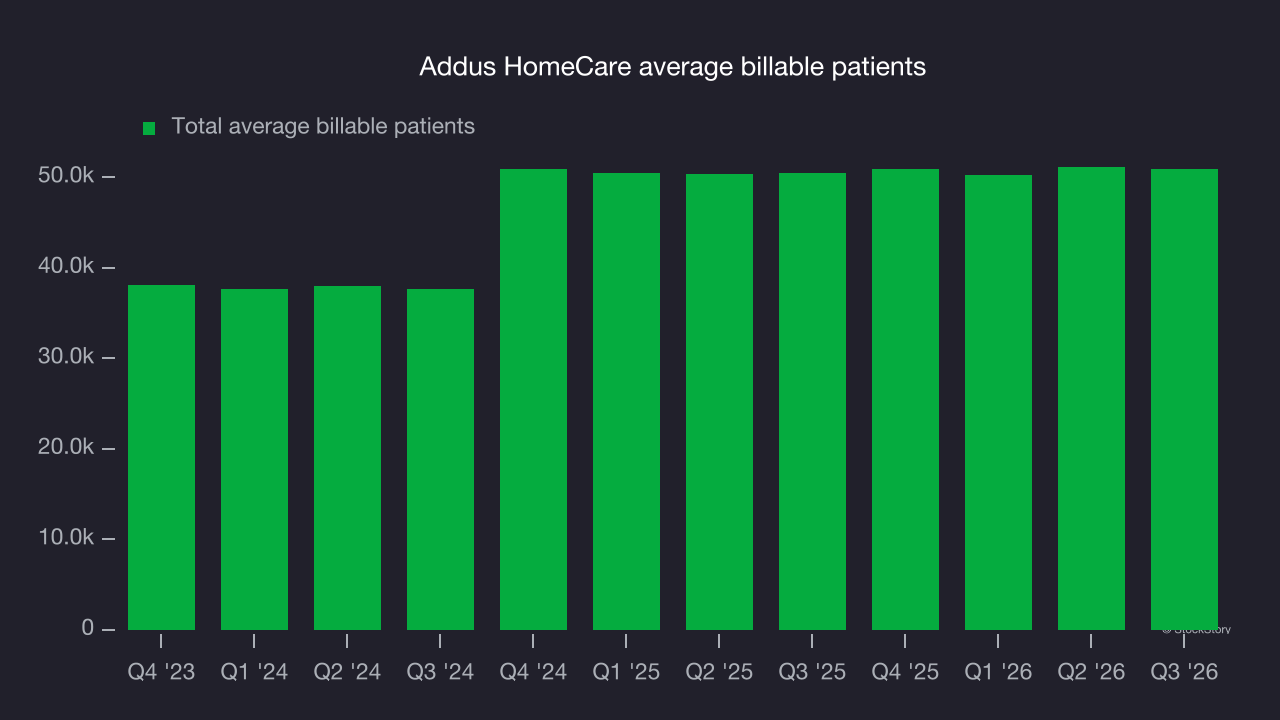
This quarter, Addus HomeCare grew its revenue by 7% year on year, and its $387.7 million in revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 6.1% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, this projection is above average for the sector and indicates the market expects some success from its newer products and services.
Adjusted operating margin
Addus HomeCare has managed its cost base reasonably well over the last five years. The company has produced an average adjusted operating margin of 10.7%, higher than the broader healthcare sector.
Looking at the trend in its profitability, Addus HomeCare’s adjusted operating margin rose by 2.4 percentage points over the last five years, as its revenue growth gave it operating leverage.
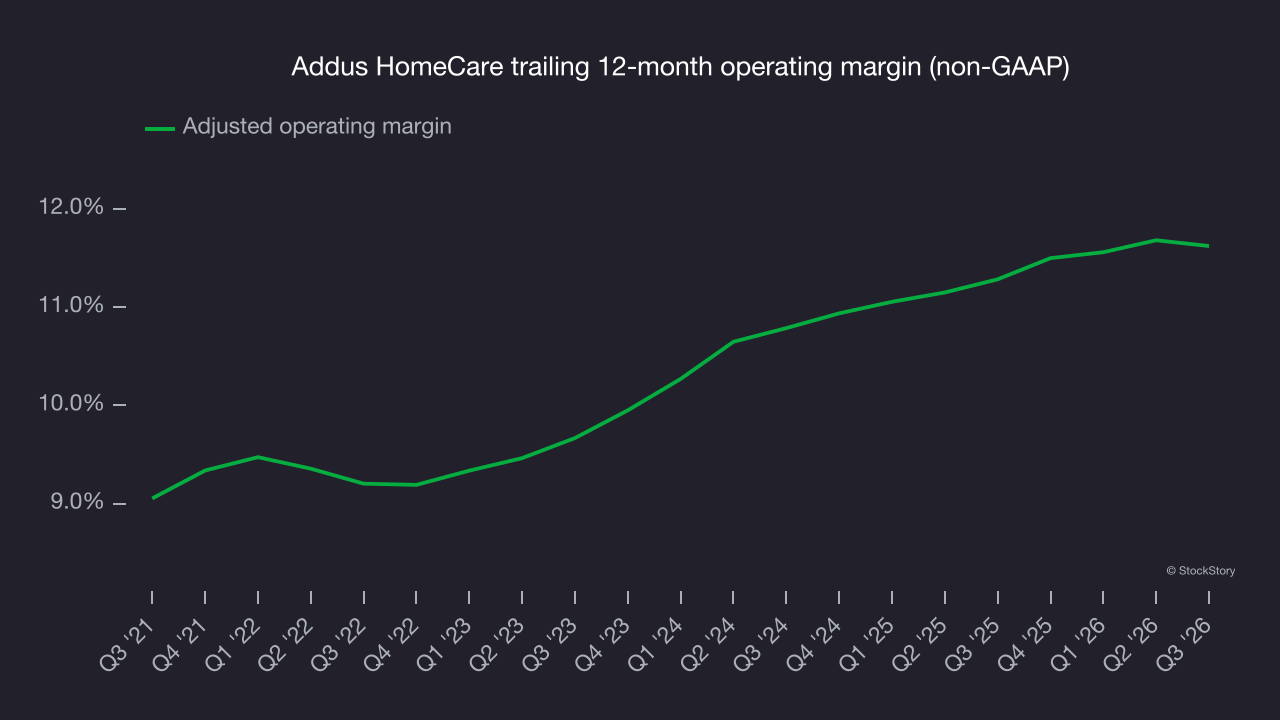
In Q3, Addus HomeCare generated an adjusted operating margin of 11%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Addus HomeCare’s EPS grew at a 15.6% compounded annual growth rate over the last five years, higher than its 12.4% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
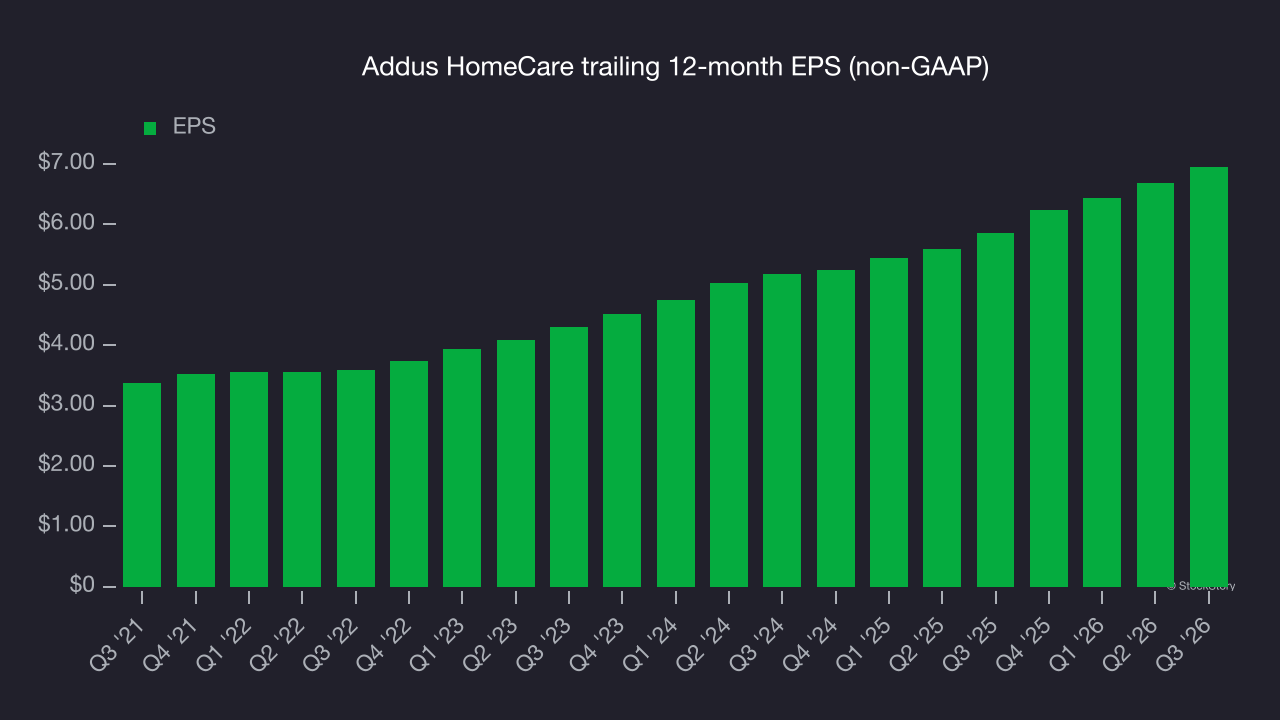
Examining Addus HomeCare’s earnings quality helps explain its performance. As we mentioned earlier, Addus HomeCare’s adjusted operating margin was flat this quarter but expanded by 2.4 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, Addus HomeCare reported adjusted EPS of $1.83, up from $1.56 in the same quarter last year. This result beat analysts’ consensus estimates by 2.1%. Over the next 12 months, Wall Street expects Addus HomeCare’s full-year EPS to grow 5.3% from $6.95 to $7.32, according to S&P.
Key takeaways from Addus HomeCare’s Q3 results
Addus HomeCare delivered a lackluster quarter with few positives. Shares remained flat at $126.38 immediately after the results.
Is Addus HomeCare a buy? Consider valuation, business quality and the latest earnings when making that decision. For more, read our full research report here (it’s free).