Healthcare products company West Pharmaceutical Services (NYSE: WST) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 8.7% year on year to $874.5 million. The company’s full-year revenue guidance of $3.42 billion at the midpoint came in 1.2% above analysts’ consensus estimates. Its non-GAAP profit of $2.66 per share was 21.1% above analysts’ consensus estimates.
For more on West Pharmaceutical Services, read the full research report for free.
West Pharmaceutical Services (WST) Q3 2026 highlights:
- Revenue $874.5 million vs S&P analysts’ consensus estimates of $827.1 million (8.7% year-on-year growth, 5.7% beat)
- Adjusted EPS $2.66 vs S&P analysts’ consensus estimates of $2.20 (21.1% beat)
- Revenue guidance The company lifted its revenue guidance for the full year to $3.42 billion at the midpoint from $3.36 billion, a 1.6% increase
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $9.43 at the midpoint, a 5.4% increase
- Operating margin 30.6%, up from 20.8% in the same quarter last year
- Free cash flow margin 17.2%, similar to the same quarter last year
- Market capitalization $28.41 billion
Michel Lagarde, President and Chief Executive Officer, commented: "I am pleased to report strong third-quarter 2026 results, with net sales and adjusted EPS exceeding our expectations. Our results were again led by our High-Value Product (HVP) Components business. The robust sales performance drove strong operating income margin expansion and EPS growth. As a result of our team's strong execution in the third quarter, we are increasing our full-year 2026 guidance."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a poor business can perform well for one or two quarters, but a high-quality one grows for years. West Pharmaceutical Services’s revenue grew at a mediocre 4.8% compounded annual growth rate over the last five years, falling short of the healthcare sector standard.
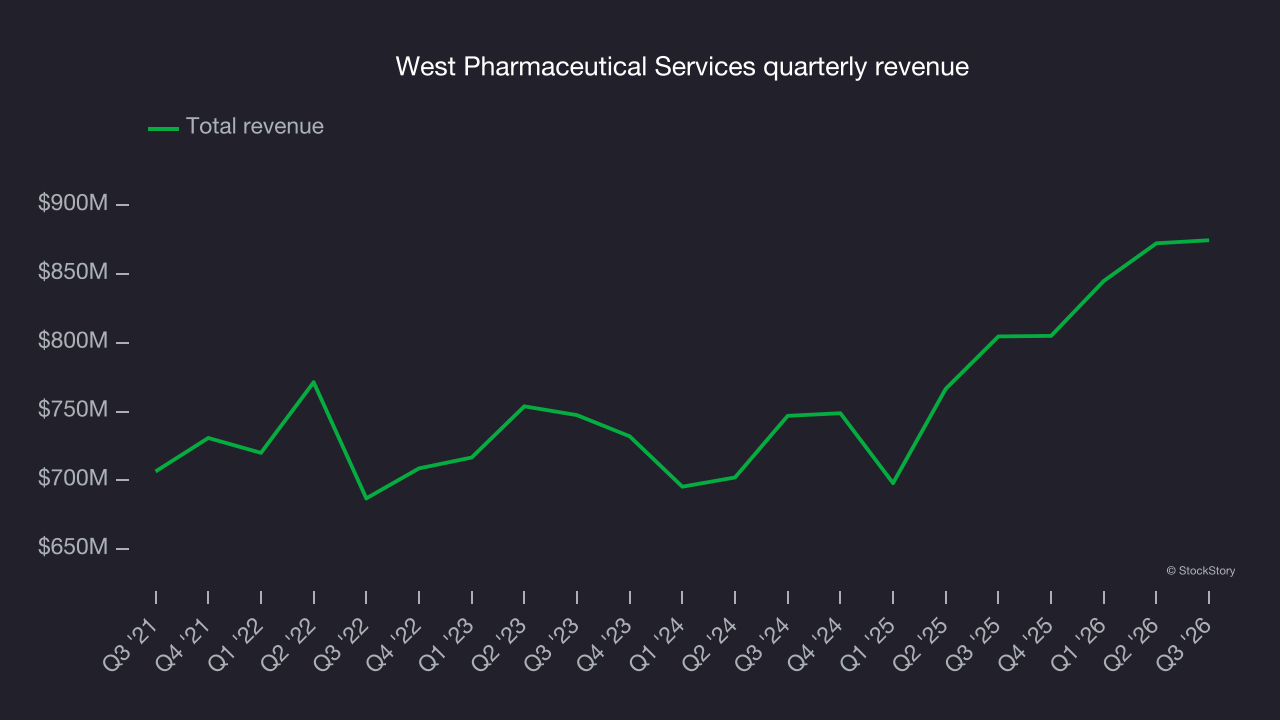
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. West Pharmaceutical Services’s annualized revenue growth of 8.7% over the last two years is above its five-year trend, suggesting some bright spots. 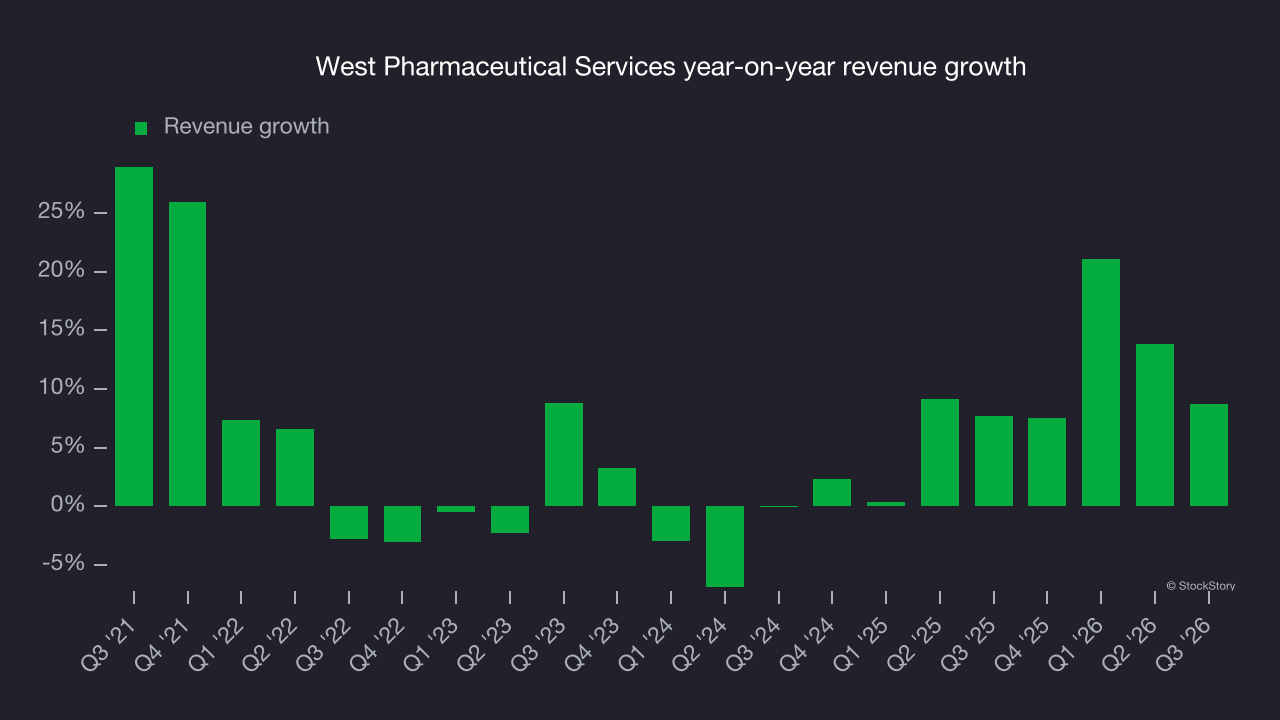
This quarter, West Pharmaceutical Services reported year-on-year revenue growth of 8.7%, and its $874.5 million of revenue exceeded Wall Street’s consensus estimates by 5.7%.
Looking ahead, sell-side analysts expect revenue to grow 2.8% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and suggests its products and services will face some demand challenges.
Adjusted operating margin
West Pharmaceutical Services has been an efficient company over the last five years. It was one of the more profitable businesses in the healthcare sector, with an average adjusted operating margin of 23.1%.
Looking at the trend in its profitability, West Pharmaceutical Services’s adjusted operating margin decreased by 3 percentage points over the last five years, but it rose by 4.4 percentage points on a two-year basis. Still, shareholders will want to see West Pharmaceutical Services become more profitable in the future.
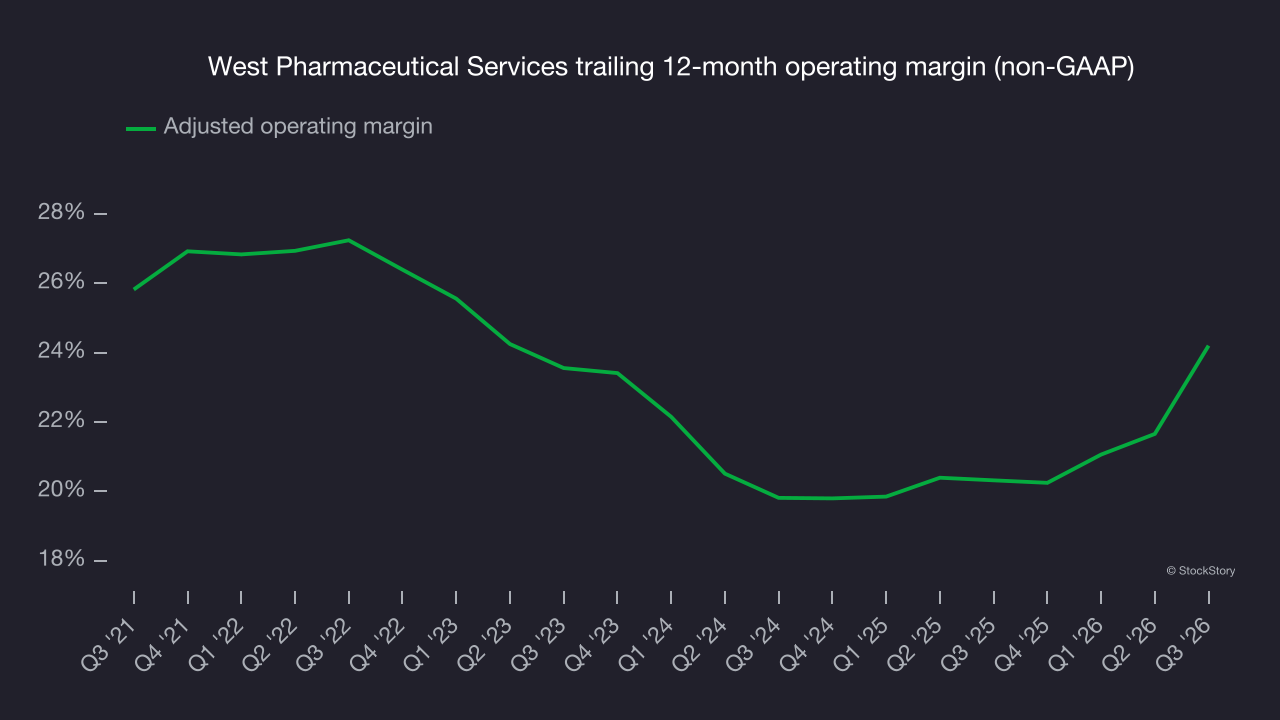
In Q3, West Pharmaceutical Services generated an adjusted operating margin of 31.1%, up 9.9 percentage points year on year. This was a positive development, showing improved efficiency.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
West Pharmaceutical Services’s unimpressive 3.1% annual EPS growth over the last five years aligns with its revenue performance. On the positive side, this indicates its incremental revenue was profitable.
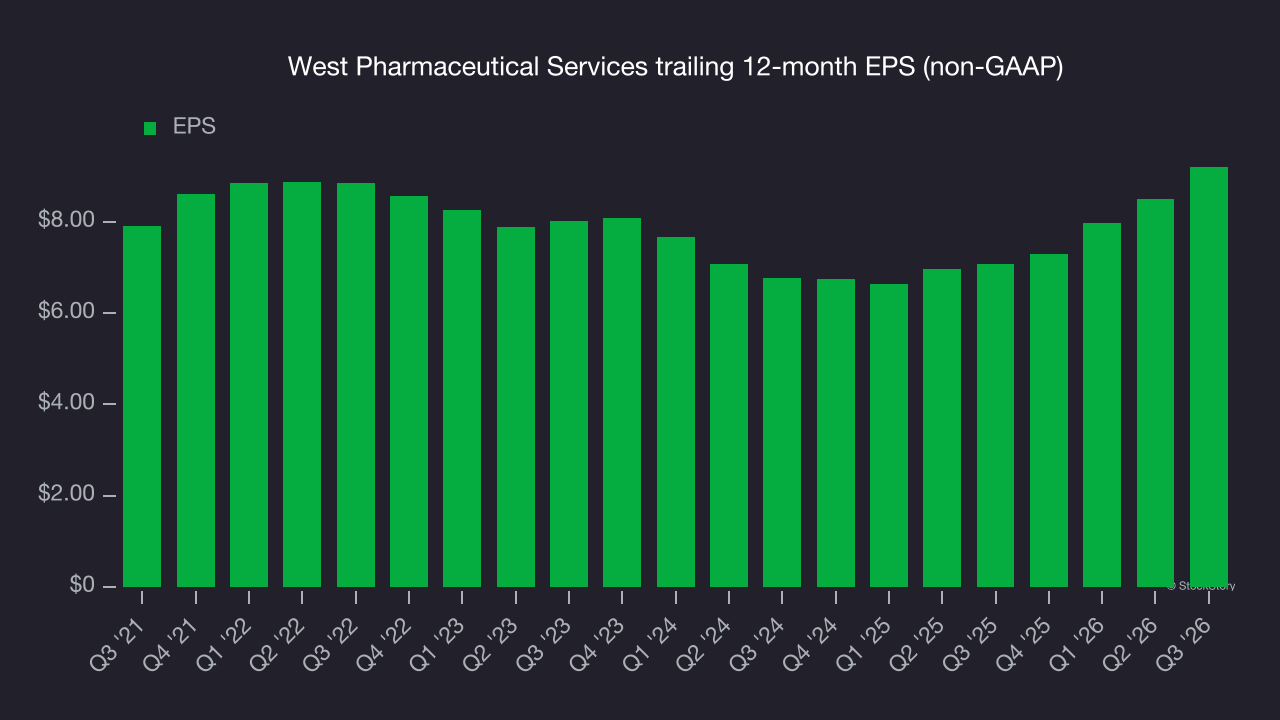
In Q3, West Pharmaceutical Services reported adjusted EPS of $2.66, up from $1.96 in the same quarter last year. This result came in well above analysts’ consensus estimates. Over the next 12 months, Wall Street expects West Pharmaceutical Services’s full-year EPS to grow 4.3% from $9.20 to $9.59, according to S&P.
Key takeaways from West Pharmaceutical Services’s Q3 results
Revenue well above analysts’ consensus estimates and full-year EPS guidance that topped Wall Street’s consensus by a wide margin made this a solid quarter for West Pharmaceutical Services. Shares rose 2.5% to $414.53 immediately after the results.
West Pharmaceutical Services reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. The latest quarter matters, but longer-term fundamentals and valuation matter much more when making that decision. For more on West Pharmaceutical Services, read the full research report here (it’s free).