Real estate services firm Newmark (NASDAQ: NMRK) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 12.7% year on year to $973.2 million. On the other hand, the company’s full-year revenue guidance of $3.75 billion at the midpoint came in 0.9% below analysts’ consensus estimates. Its non-GAAP profit of $0.48 per share was in line with analysts’ consensus estimates.
For more on Newmark, read our free full research report.
Newmark (NMRK) Q3 2026 highlights:
- Revenue $973.2 million vs S&P analysts’ consensus estimates of $952.7 million (12.7% year-on-year growth, 2.2% beat)
- Adjusted EPS $0.48 vs S&P analysts’ consensus estimates of $0.47 (in line)
- Adjusted EBITDA $166.4 million vs analysts’ consensus estimates of $164.4 million (17.1% margin, 1.2% beat)
- Revenue guidance The company lowered its full-year revenue guidance to $3.75 billion at the midpoint from $3.83 billion, a 2% decrease
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $1.85 at the midpoint, a 3.9% decrease
- EBITDA guidance $648 million at the midpoint for the full year, below analysts’ consensus estimates of $662.8 million
- Operating margin 8.8%, up from 5% in the same quarter last year
- Free cash flow -$303.5 million, down from $104.9 million in the same quarter last year
- Market capitalization $2.19 billion
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Newmark’s revenue grew at a weak 8% compounded annual growth rate over the last five years, falling short of our standard for the consumer discretionary sector.
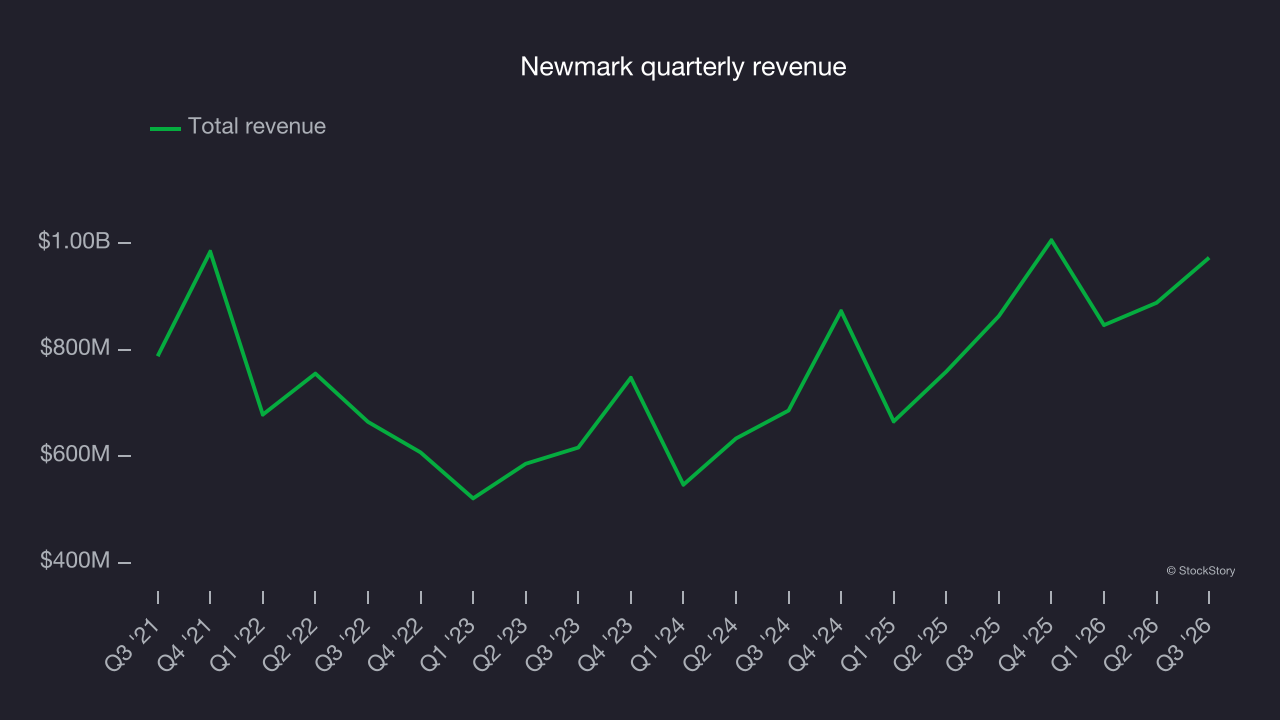
Long-term growth matters most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new product or trend. Newmark’s annualized revenue growth of 19.2% over the last two years is above its five-year trend, a positive sign. 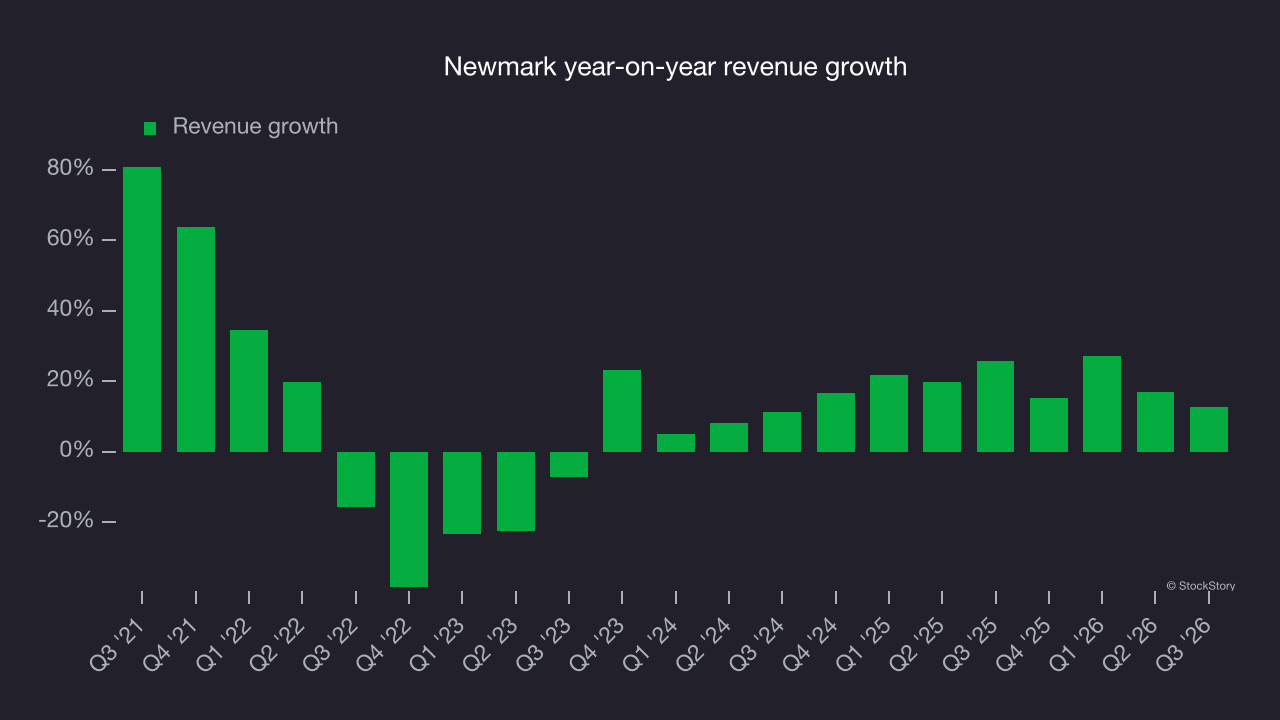
This quarter, Newmark reported year-on-year revenue growth of 12.7%, and its $973.2 million of revenue exceeded Wall Street’s consensus estimates by 2.2%.
Looking ahead, sell-side analysts expect revenue to grow 5.3% over the next 12 months, according to S&P, a deceleration versus the last two years. This uninspiring projection implies its products and services will face some demand headwinds.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Newmark’s operating margin has risen over the last 12 months and averaged 6.3% over the last two years. The company’s higher efficiency is a positive, but its suboptimal cost structure means profitability remains inadequate for a consumer discretionary business.
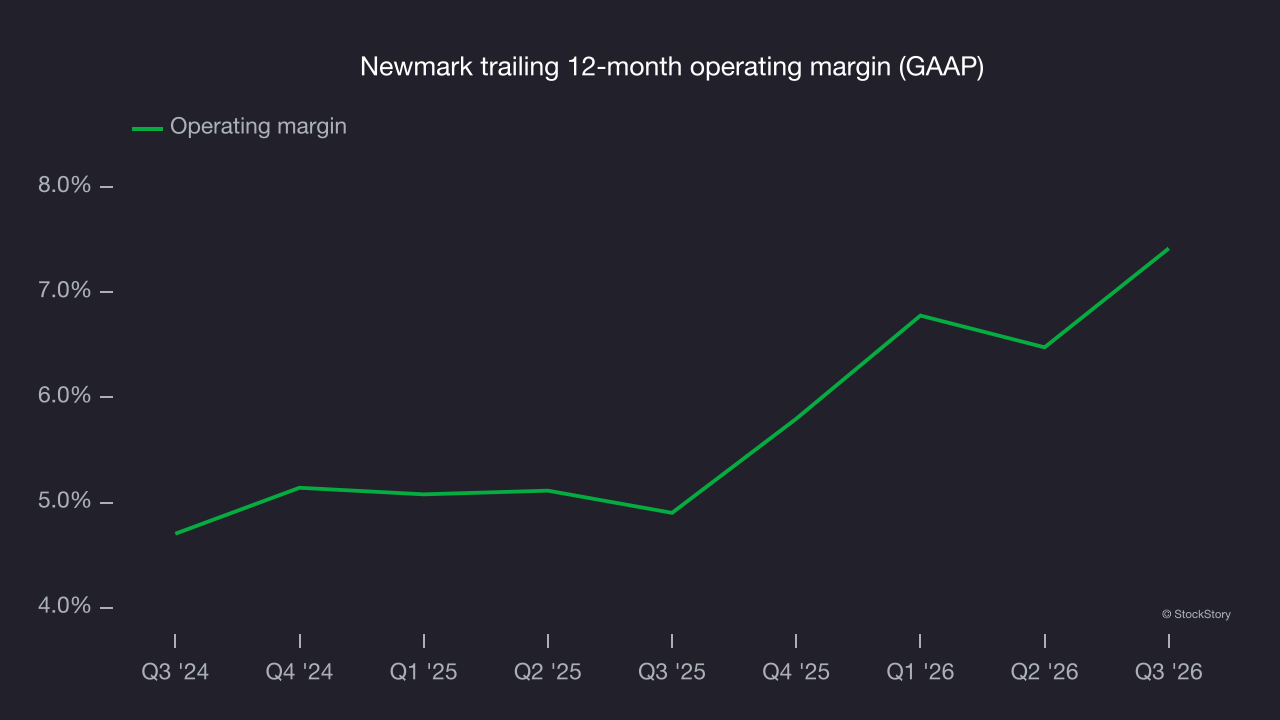
This quarter, Newmark generated an operating margin of 8.8%, up 3.8 percentage points year on year. The increase was a positive sign of improved efficiency.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Newmark’s weak 7.5% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
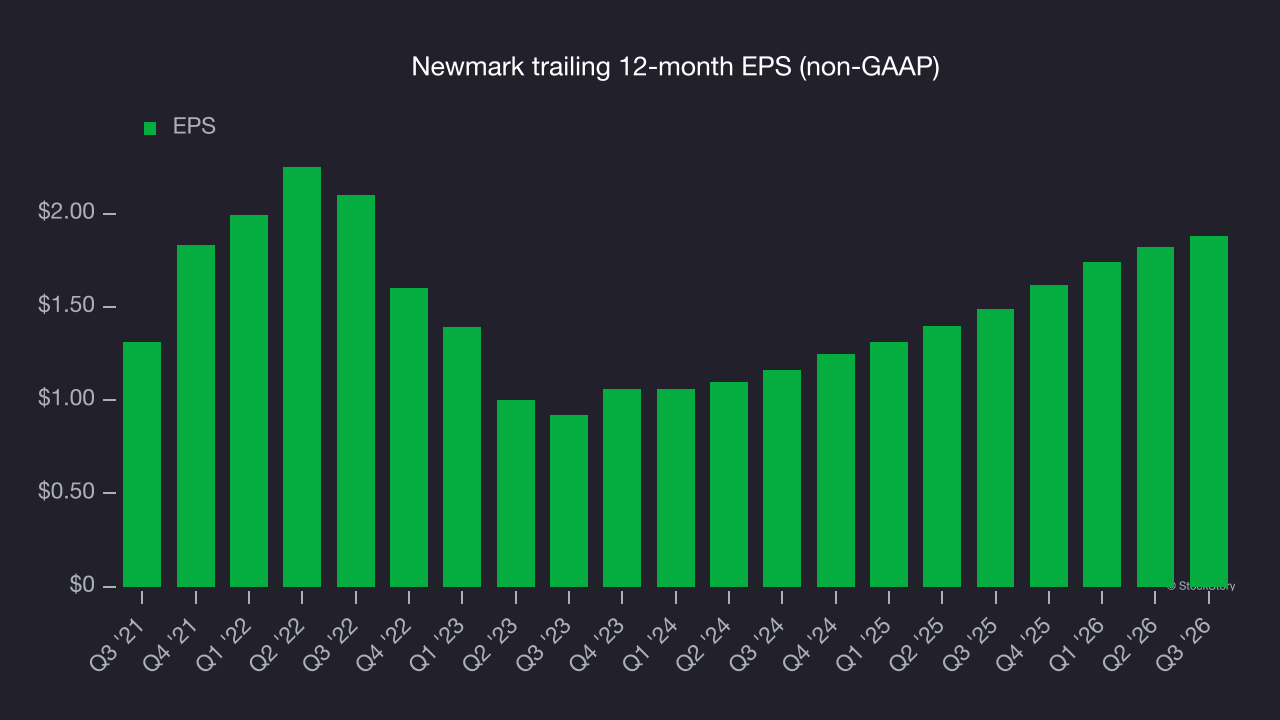
In Q3, Newmark reported adjusted EPS of $0.48, up from $0.42 in the same quarter last year. This result beat analysts’ consensus estimates by 1.9%. Over the next 12 months, Wall Street expects Newmark’s full-year EPS to grow 8.2% from $1.88 to $2.03, according to S&P.
Key takeaways from Newmark’s Q3 results
Newmark’s full-year outlook was the weak spot in a softer quarter overall: revenue guidance slightly missed expectations, and EBITDA guidance fell short of Wall Street’s consensus. Quarterly revenue, by contrast, beat analysts’ consensus estimates. Shares tumbled 7.2% to $11.20 immediately after the release.
Newmark’s latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when deciding whether to buy the stock at its current price. For more on Newmark, read the full research report here (it’s free).