Global payments technology company Mastercard (NYSE: MA) announced better-than-expected revenue in Q3 2026, with revenue up 14% year on year to $9.81 billion. Its non-GAAP profit of $5.31 per share was 2.7% above analysts’ consensus estimates.
For more on Mastercard, read the full research report for free.
Mastercard (MA) Q3 2026 highlights:
- Revenue $9.81 billion vs S&P analysts’ consensus estimates of $9.67 billion (14% year-on-year growth, 1.4% beat)
- Pre-tax profit $5.74 billion (58.5% margin)
- Adjusted EPS $5.31 vs S&P analysts’ consensus estimates of $5.17 (2.7% beat)
- Market capitalization $534.6 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Mastercard’s 15.3% annualized revenue growth over the last five years was impressive. Its growth surpassed the average financials company and shows its offerings resonate with customers.
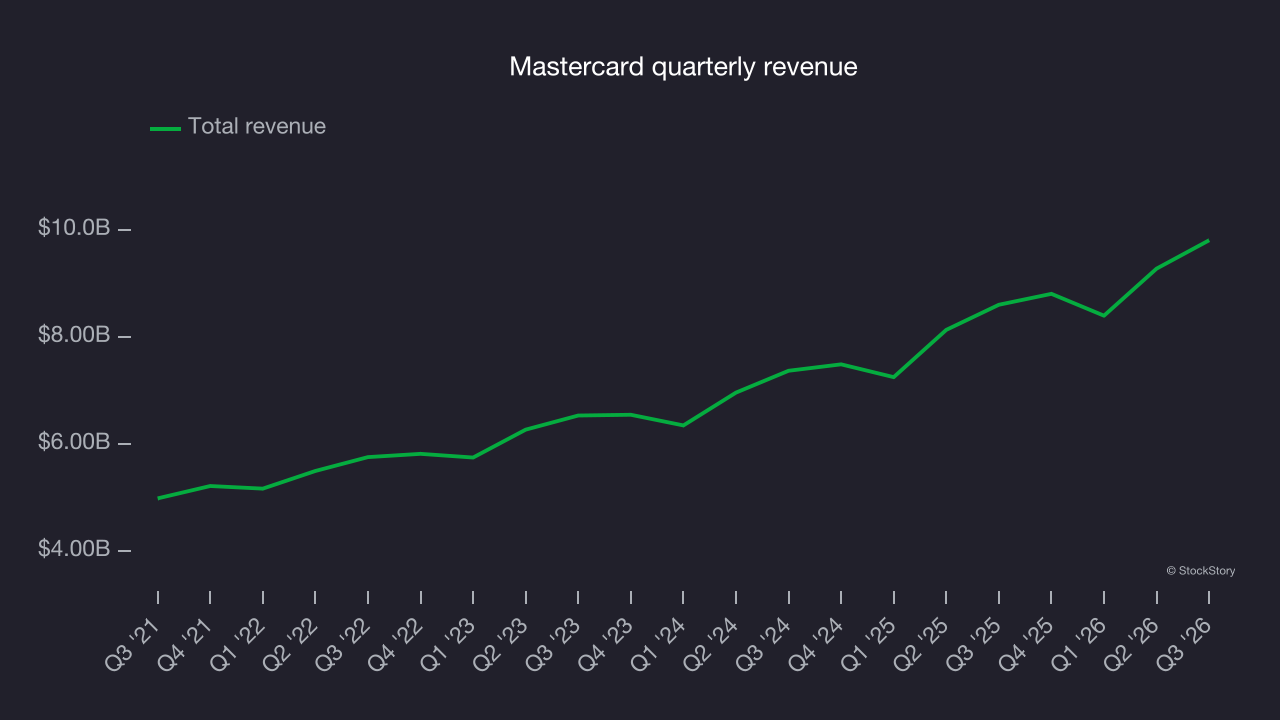
Long-term growth matters most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. Mastercard’s annualized revenue growth of 15.5% over the last two years aligns with its five-year trend, suggesting its demand was predictably strong. 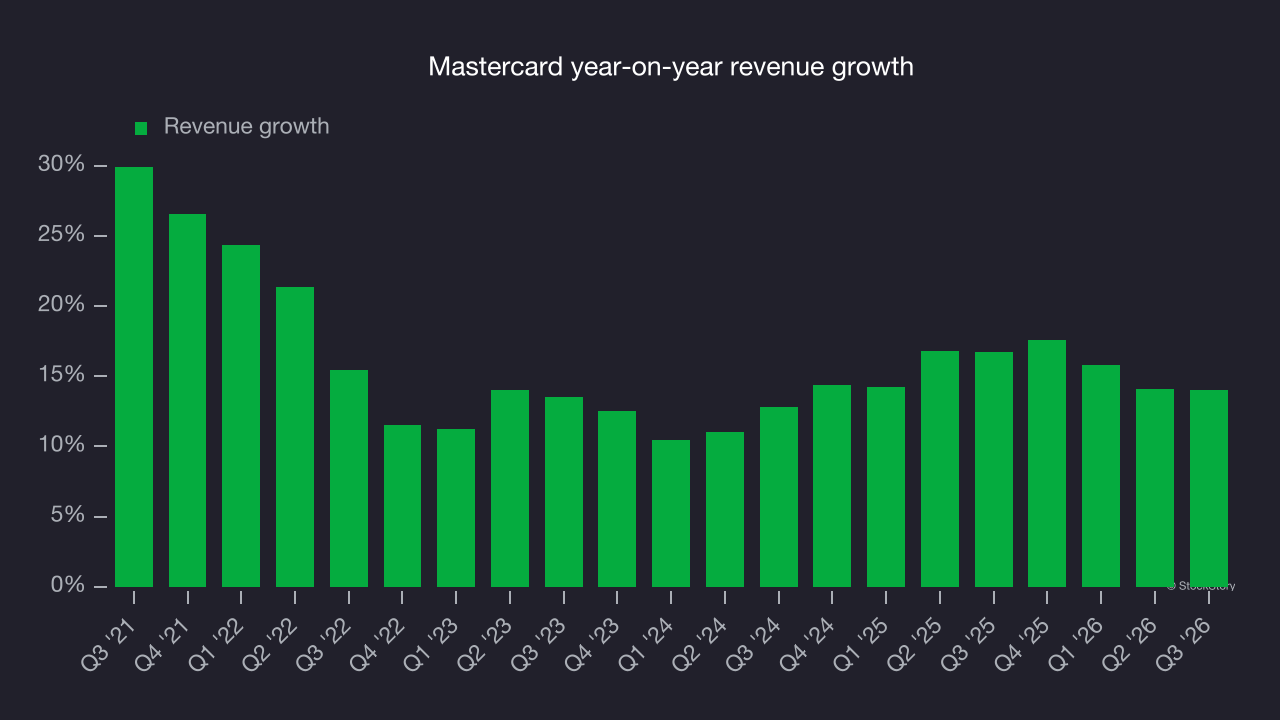
This quarter, Mastercard reported year-on-year revenue growth of 14%, and its $9.81 billion of revenue exceeded Wall Street’s consensus estimates by 1.4%.
Key takeaways from Mastercard’s Q3 results
Mastercard’s Q3 revenue narrowly topped analysts’ consensus estimates, and EPS also beat Wall Street’s expectations, making this a solid quarter with clear positives. Shares rose 3.1% to $629.48 immediately after the results.
Is Mastercard a buy at the current price? When making that decision, it’s important to consider its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).