Aerospace and defense company Huntington Ingalls (NYSE: HII) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue rising 10.8% year on year to $3.54 billion. Its GAAP profit of $5.48 per share was 23.7% above analysts’ consensus estimates.
For more on Huntington Ingalls, read the full research report, available free.
Huntington Ingalls (HII) Q3 2026 highlights:
- Revenue $3.54 billion vs S&P analysts’ consensus estimates of $3.36 billion (10.8% year-on-year growth, 5.3% beat)
- EPS (GAAP) $5.48 vs analysts’ consensus estimates of $4.43 (23.7% beat)
- Operating margin 7%, up from 5% in the same quarter last year
- Free cash flow margin 12.1%, up from 0.5% in the same quarter last year
- Market capitalization $11 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Over the last five years, Huntington Ingalls grew its revenue at a mediocre 7.1% compounded annual growth rate, falling short of our standard for the industrials sector.
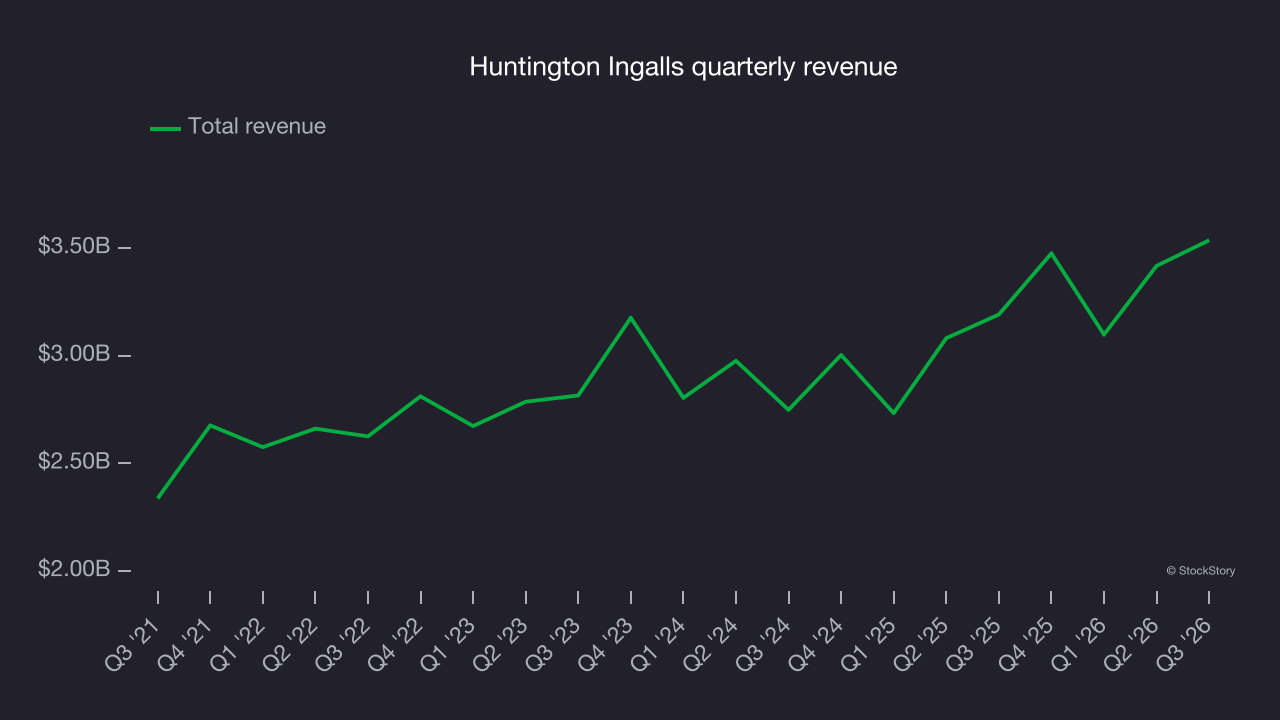
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Huntington Ingalls’s annualized revenue growth of 7.5% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 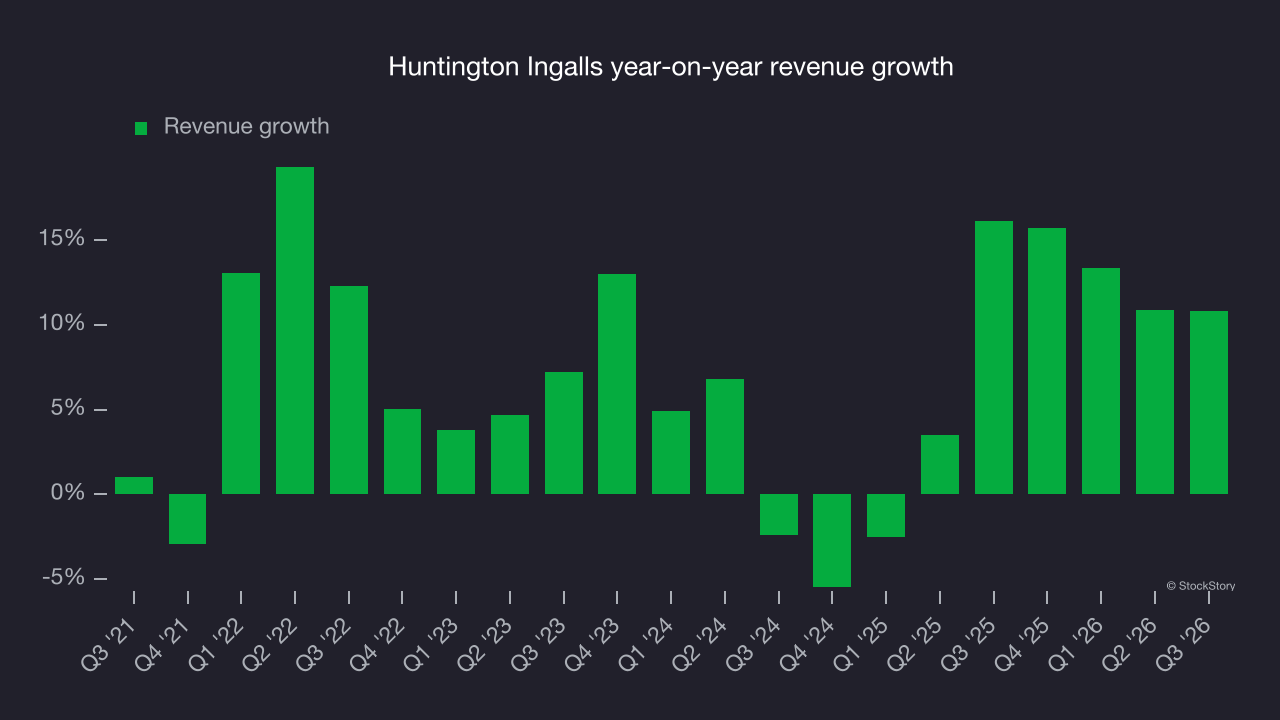
This quarter, Huntington Ingalls reported year-on-year revenue growth of 10.8%, and its $3.54 billion of revenue exceeded Wall Street’s consensus estimates by 5.3%.
Looking ahead, sell-side analysts expect revenue to grow 4% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and indicates its products and services will face some demand challenges.
Operating margin
Huntington Ingalls’s operating margin has generally stayed the same over the last 12 months, averaging 5.6% over the last five years. This profitability was poor for an industrials business due to its suboptimal cost structure.
Looking at the trend in its profitability, Huntington Ingalls’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
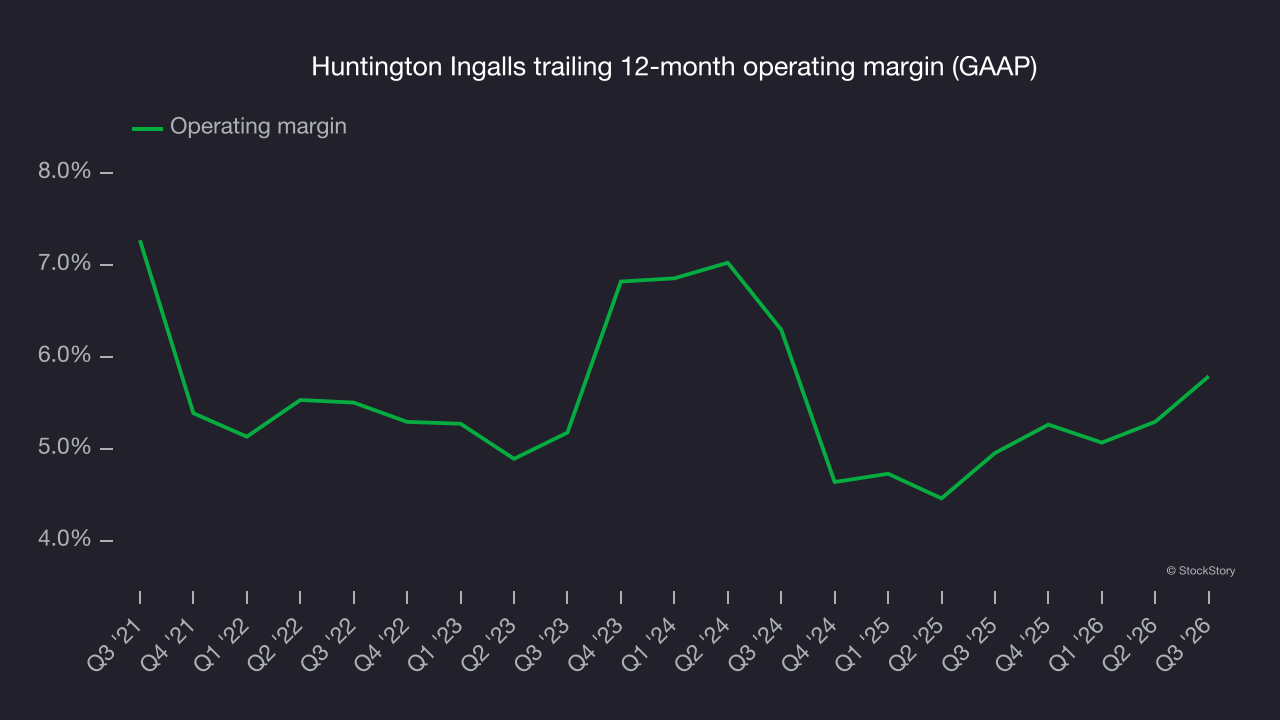
In Q3, Huntington Ingalls generated an operating margin of 7%, up 1.9 percentage points year on year. The increase was a positive sign of improved efficiency.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Huntington Ingalls’s EPS grew at a weak 2.2% compounded annual growth rate over the last five years, lower than its 7.1% annualized revenue growth. The difference stemmed from higher interest expenses or taxes, as the company improved its operating margin and repurchased its shares during this time.
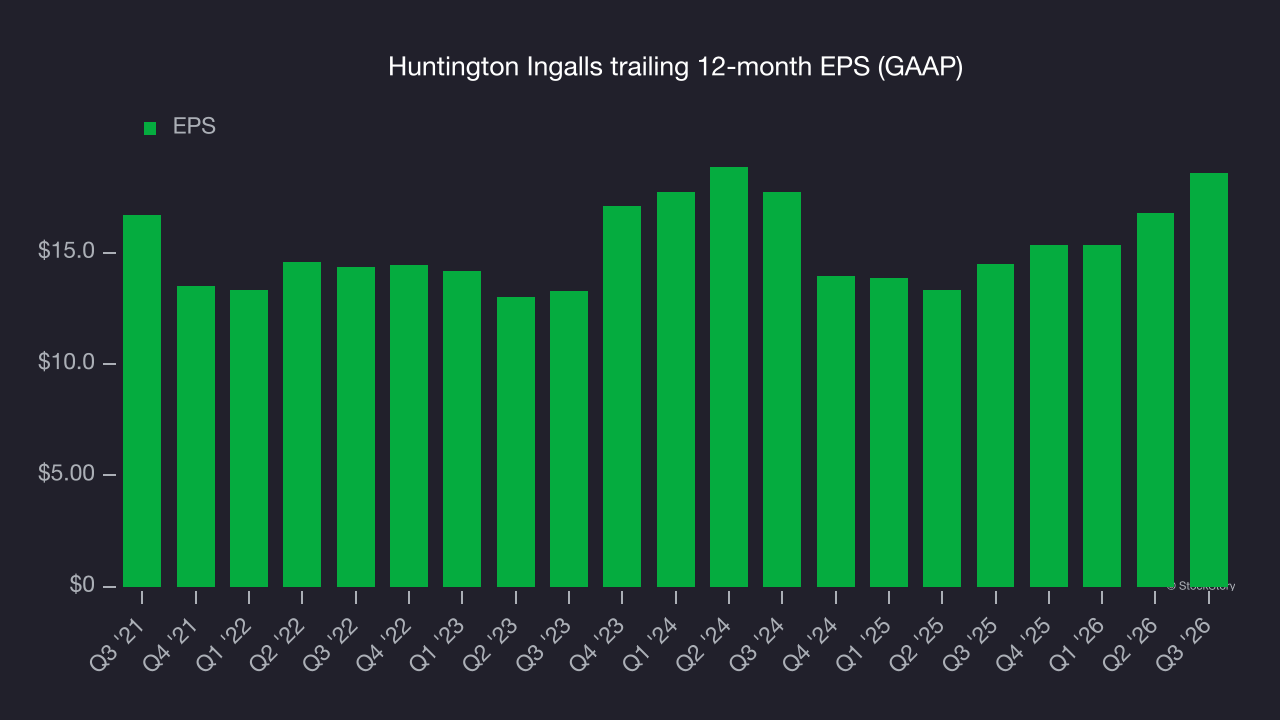
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Huntington Ingalls, its two-year annual EPS growth of 2.4% is similar to its five-year trend, implying stable earnings.
In Q3, Huntington Ingalls reported EPS of $5.48, up from $3.68 in the same quarter last year. This result was well above analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects Huntington Ingalls’s full-year EPS to grow 10.6% from $18.57 to $20.54, according to S&P.
Key takeaways from Huntington Ingalls’s Q3 results
Huntington Ingalls delivered a strong quarter, with revenue well ahead of analysts’ consensus estimates and EPS also topping Wall Street’s estimates. Shares surged 6.1% to $296.30 immediately after the results.
Huntington Ingalls may have had a good quarter, but does that make the stock a good investment now? The latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in the stock. For more on those factors, read the full research report here (it’s free).