Residential lot developer Forestar Group (NYSE: FOR) fell short of the market’s revenue expectations in calendar Q3 2026 (fiscal Q4 2026), with revenue falling 13.4% year on year to $580.8 million. The company’s full-year revenue guidance of $1.45 billion at the midpoint came in 13.5% below analysts’ consensus estimates. Its GAAP profit of $1.15 per share was 8.2% below analysts’ consensus estimates.
For more on Forestar Group, read our free full research report.
Forestar Group (FOR) Q3 CY2026 highlights:
- Revenue $580.8 million vs S&P analysts’ consensus estimates of $609.6 million (13.4% year-on-year decline, 4.7% miss)
- EPS (GAAP) $1.15 vs analysts’ consensus estimates of $1.25 (8.2% miss)
- Operating margin 11.1%, down from 16.6% in the same quarter last year
- Sales volumes rose 2.3% year on year (-67.5% in the same quarter last year)
- Market capitalization $1.32 billion
Tomnitz concluded, “Our strong balance sheet, experienced teams and broad platform provide us with significant financial and operational flexibility to navigate changing market conditions and capitalize on opportunities for growth. These strengths, combined with our strategic relationship with D.R. Horton and $2.2 billion of contracted future revenue, position us well to continue supplying homebuilders with finished lots and capturing market share. We remain focused on disciplined capital allocation while positioning Forestar for growth and long-term shareholder value.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years. Over the last five years, Forestar Group grew its revenue at a weak 4.3% compounded annual growth rate, falling short of the consumer discretionary sector benchmark.
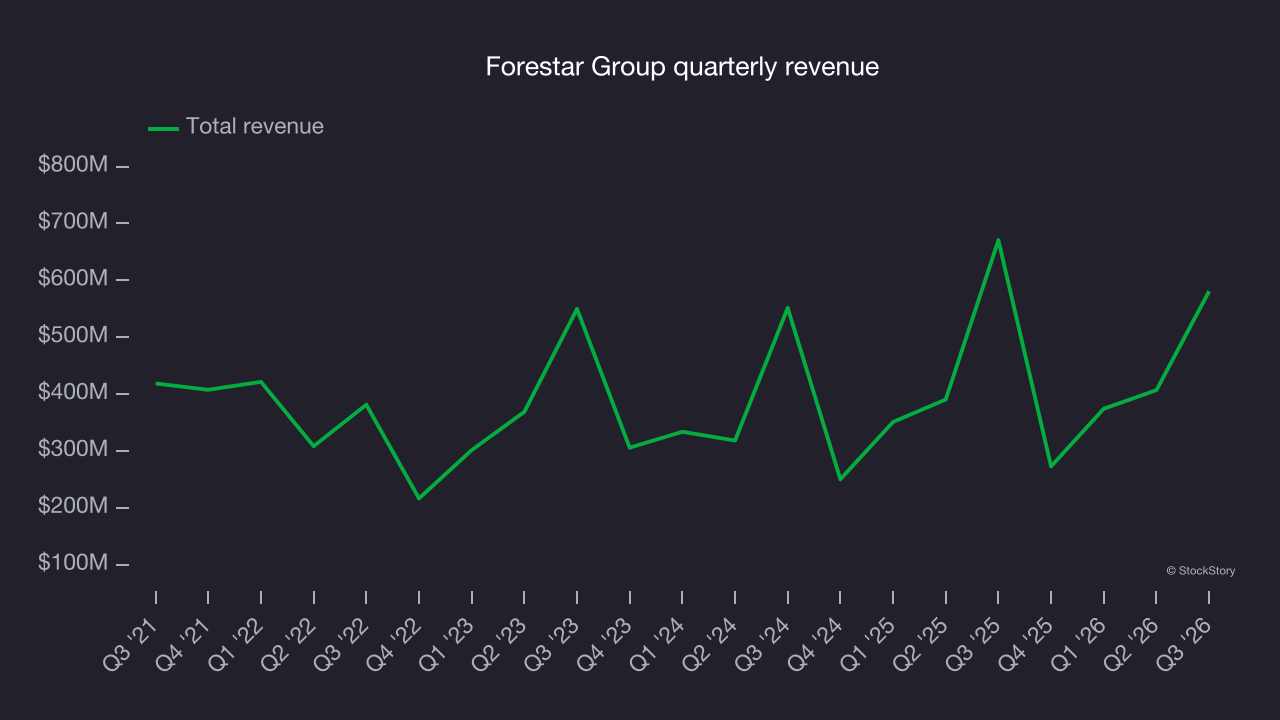
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. Forestar Group’s annualized revenue growth of 4.1% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 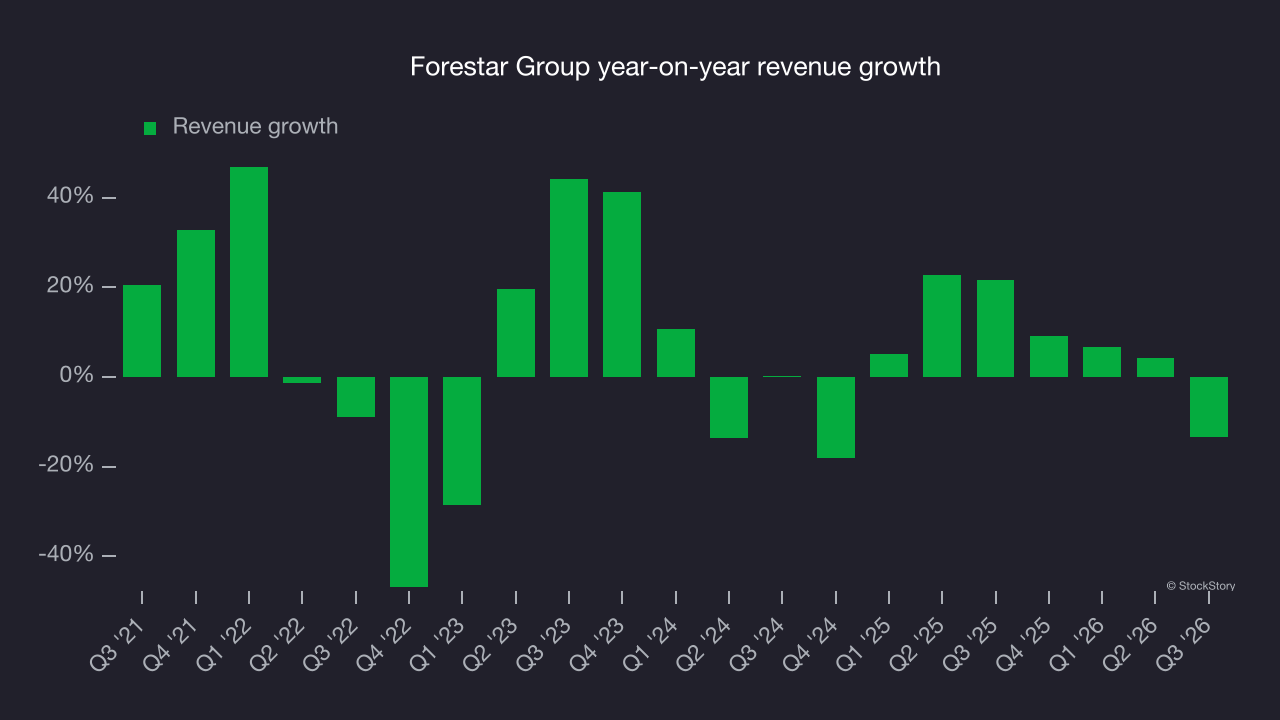
Forestar Group also reports its number of lots sold, which reached 5,004 in the latest quarter. Over the last two years, Forestar Group’s number of lots sold declined by an average of 15.1% year on year. Revenue growth outpaced this metric, indicating that the company benefited from price increases. 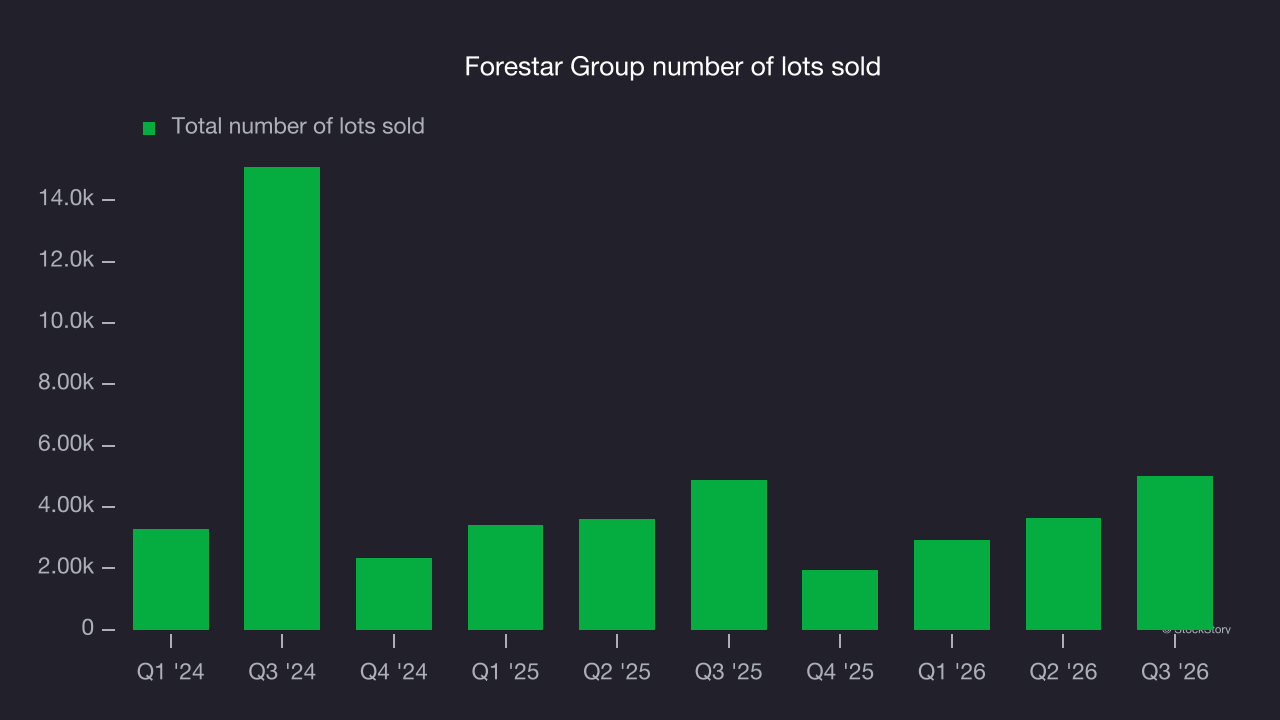
This quarter, Forestar Group missed Wall Street’s consensus estimates and reported an uninspiring 13.4% year-on-year revenue decline, generating $580.8 million of revenue.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P, a deceleration versus the last two years. That underwhelming outlook implies its products and services will face some demand challenges.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income, the bottom line, excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Forestar Group’s operating margin has been trending down over the last 12 months and averaged 11.7% over the last two years. The company’s profitability was mediocre for a consumer discretionary business and shows it couldn’t pass its higher operating expenses onto its customers.
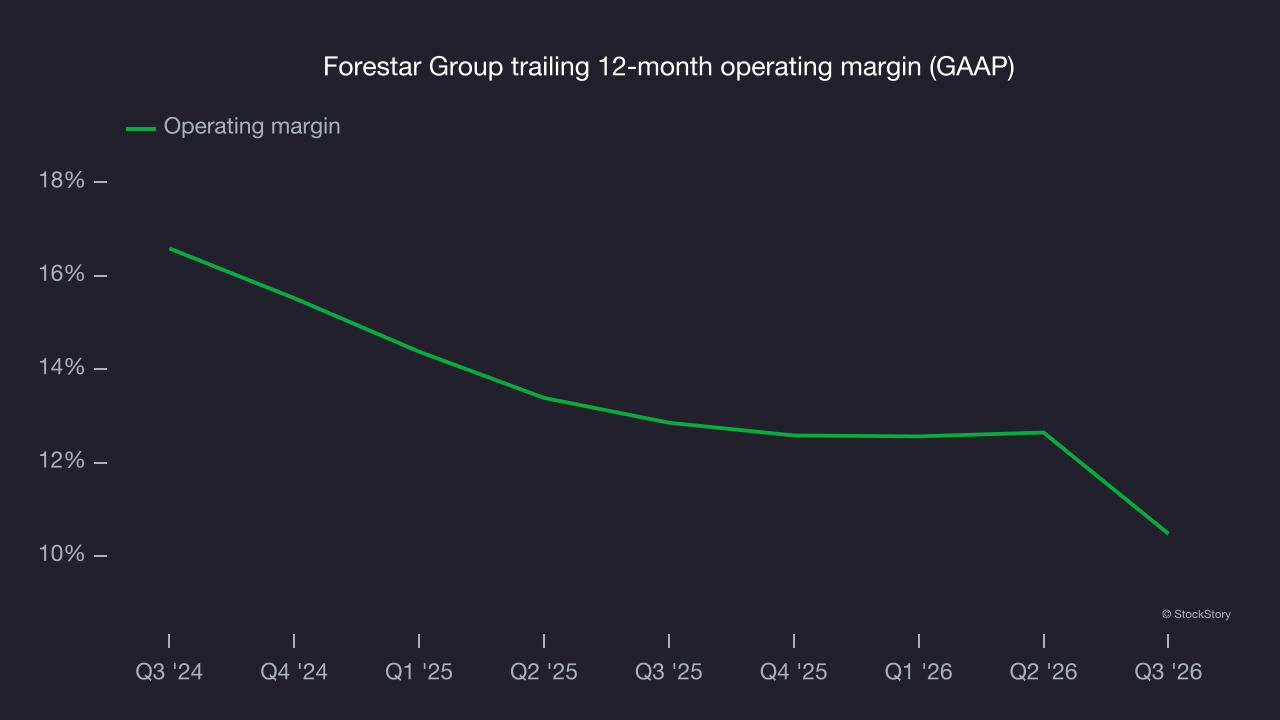
This quarter, Forestar Group generated an operating margin of 11.1%, down 5.5 percentage points year on year. This contraction shows it was less efficient because its expenses increased relative to its revenue.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Forestar Group’s weak 4.2% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
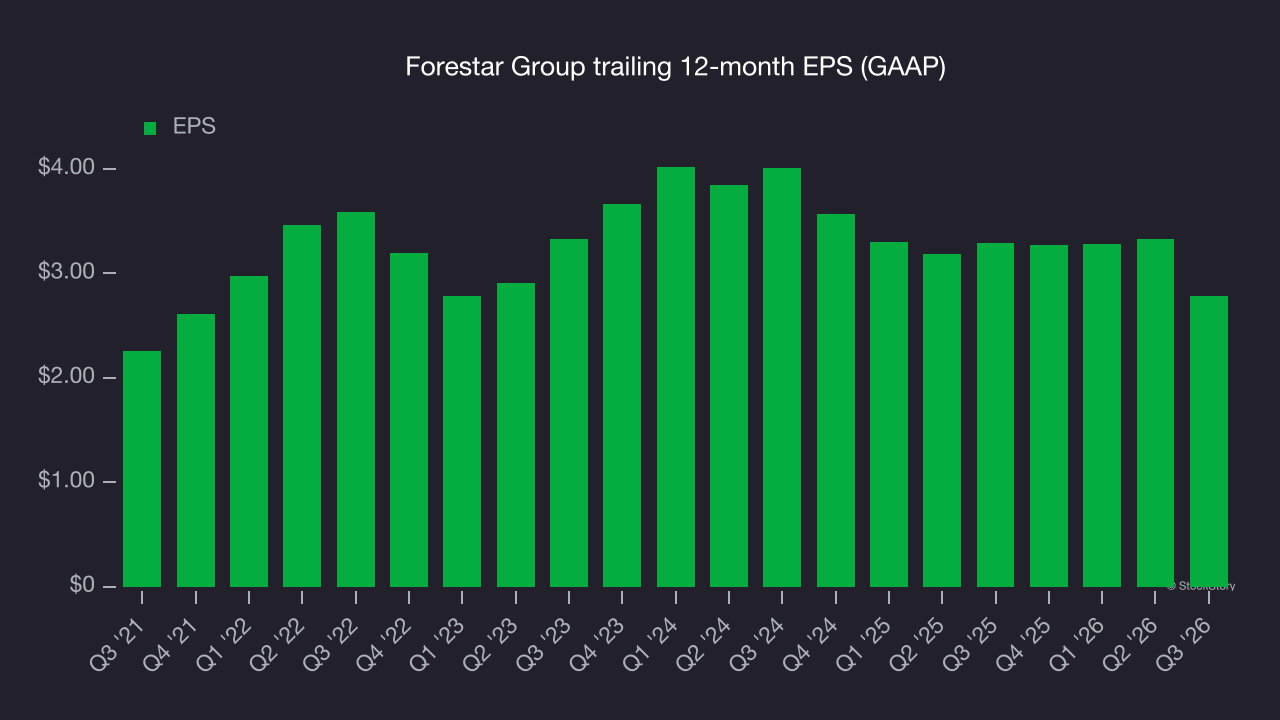
In Q3, Forestar Group reported EPS of $1.15, down from $1.70 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects Forestar Group’s full-year EPS to grow 2.6% from $2.78 to $2.85, according to S&P.
Key takeaways from Forestar Group’s Q3 results
Forestar Group’s revenue fell short of Wall Street’s consensus estimates, and its full-year revenue guidance also missed expectations. Those shortfalls left few positives in a weaker quarter. Shares tumbled 8.6% to $23.69 immediately after the report.
Forestar Group’s latest earnings report disappointed. One quarter doesn’t define a company’s quality, so assessing whether the stock is a buy at the current price requires a broader view. The latest quarter matters, but longer-term fundamentals and valuation matter more when making that decision. For more on Forestar Group, read the full research report here (it’s free).