On-demand food delivery service DoorDash (NASDAQ: DASH) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue rising 34% year on year to $4.62 billion. Its GAAP profit of $1.06 per share was 31.4% above analysts’ consensus estimates.
For more on DoorDash, read our free full research report.
DoorDash (DASH) Q3 2026 highlights:
- Revenue $4.62 billion vs S&P analysts’ consensus estimates of $4.57 billion (34% year-on-year growth, 1.1% beat)
- EPS (GAAP) $1.06 vs analysts’ consensus estimates of $0.81 (31.4% beat)
- Adjusted EBITDA $1.06 billion vs analysts’ consensus estimates of $1.03 billion (23% margin, 2.7% beat)
- EBITDA guidance $1 billion at the midpoint for Q4 2026, below analysts’ consensus estimates of $1.05 billion
- Operating margin 9.6%, up from 7.5% in the same quarter last year
- Free cash flow margin 17%, similar to the previous quarter
- Orders 993 million, up 217 million year on year
- Market capitalization $73.44 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last three years, DoorDash grew its revenue at a strong 27.9% compounded annual growth rate. Its growth surpassed the average consumer internet company and shows its offerings resonate with customers.
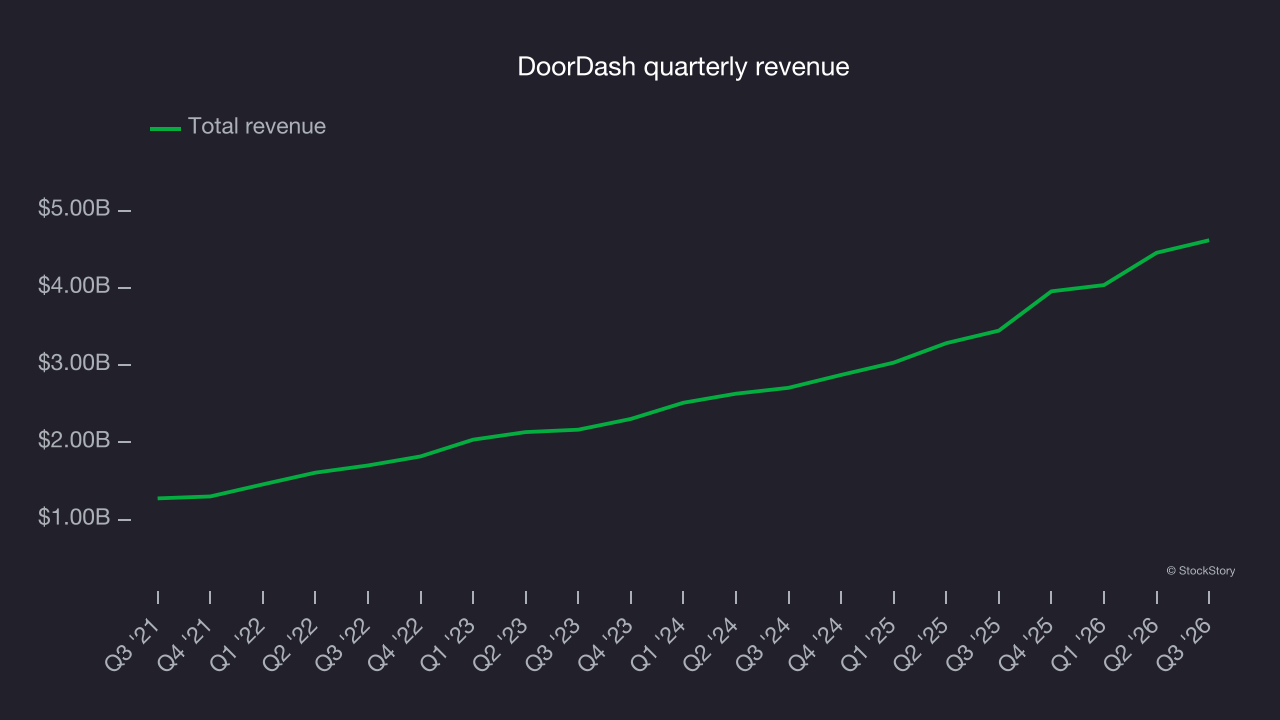
This quarter, DoorDash reported year-on-year revenue growth of 34%, and its $4.62 billion of revenue exceeded Wall Street’s consensus estimates by 1.1%.
Looking ahead, sell-side analysts expect revenue to grow 20.8% over the next 12 months, according to S&P, a deceleration versus the last three years. Its growth trajectory remains attractive given its scale and suggests the market is forecasting success for its products and services.
Orders
Request growth
As a gig economy marketplace, DoorDash generates revenue growth by expanding the number of services on its platform (e.g. rides, deliveries and freelance jobs) and raising the commission fee from each service provided.
Over the last two years, DoorDash’s orders, a key performance metric for the company, increased by 24.1% annually to 993 million in the latest quarter. This growth rate is among the fastest of any consumer internet business and indicates its offerings have significant traction.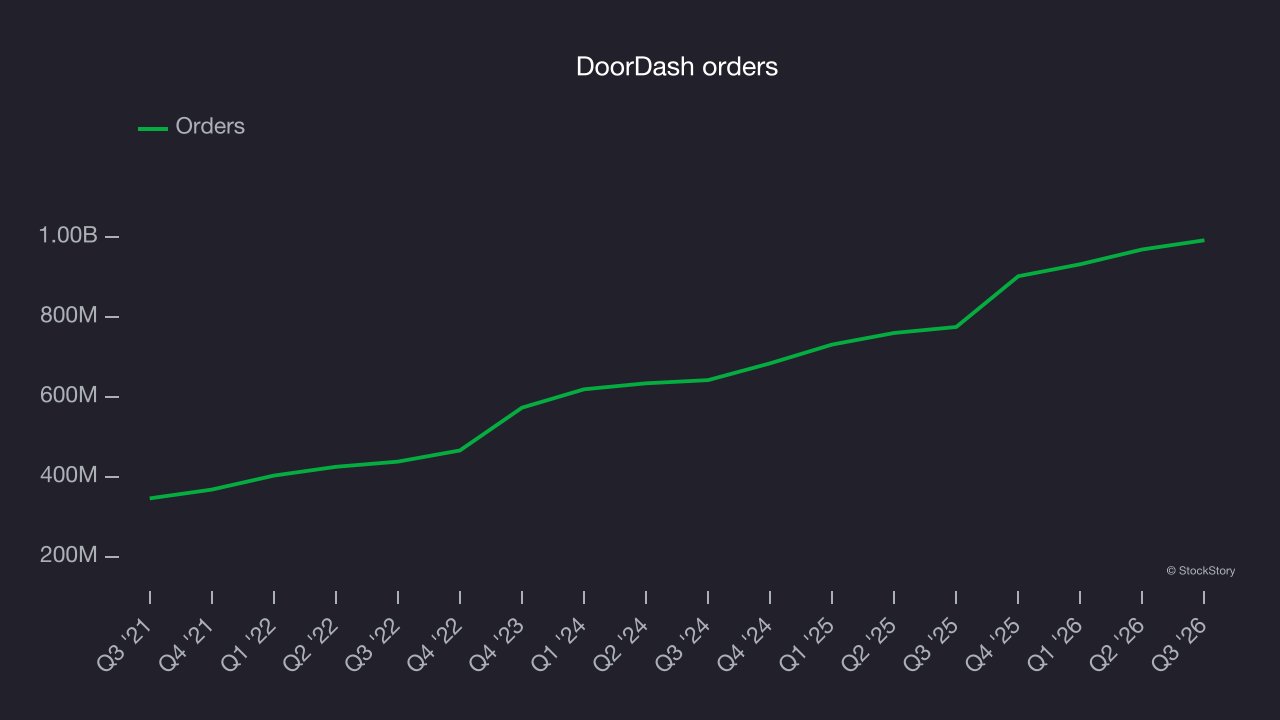
In Q3, DoorDash added 217 million orders, leading to 28% year-on-year growth. The quarterly growth rate was higher than its two-year pace, suggesting its new initiatives are accelerating request growth.
Revenue per request
Average revenue per request (ARPR) is a critical metric to track because it measures how much the company earns in transaction fees from each request. This number also provides insight into DoorDash’s take rate, which represents its pricing leverage over the ecosystem, or “cut” from each transaction.
DoorDash’s ARPR growth has been mediocre over the last two years, averaging 4.5%, but the increase in orders is more relevant for assessing long-term business potential. If DoorDash tries boosting ARPR by taking a more aggressive approach to monetization, it’s unclear whether requests can continue growing at the current pace.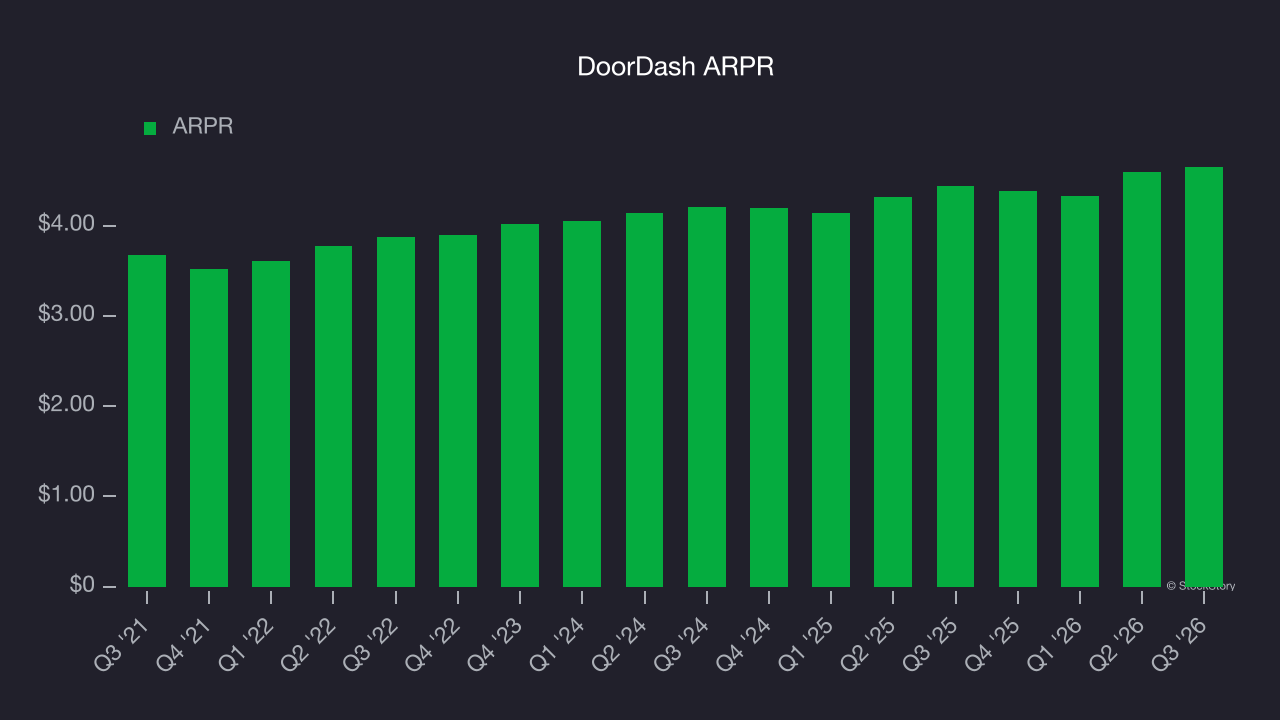
This quarter, DoorDash’s ARPR was $4.65. It grew by 4.7% year on year, slower than its request growth.
Key takeaways from DoorDash’s Q3 results
We enjoyed seeing DoorDash increase its number of requests this quarter, leading to a revenue beat. We were also happy its EBITDA outperformed Wall Street’s estimates. Overall, this quarter was solid. The stock traded up 6.9% to $181.18 immediately following the results.
DoorDash’s latest quarter matters, but longer-term fundamentals and valuation are more important when deciding whether to buy the stock. Read the full research report here (it’s free).