Financial regulatory software provider Donnelley Financial Solutions (NYSE: DFIN) announced better-than-expected revenue in Q3 2026, with revenue up 5.5% year on year to $185 million. In addition, next quarter’s revenue guidance ($177.5 million at the midpoint) was unexpectedly strong, coming in 3.9% above analysts’ consensus estimates. Its non-GAAP profit of $1.07 per share was 26.9% above analysts’ consensus estimates.
For more on Donnelley Financial Solutions, read our free full research report.
Donnelley Financial Solutions (DFIN) Q3 2026 highlights:
- Revenue $185 million vs S&P analysts’ consensus estimates of $179.9 million (5.5% year-on-year growth, 2.8% beat)
- Pre-tax profit $29.8 million (16.1% margin)
- Adjusted EPS $1.07 vs S&P analysts’ consensus estimates of $0.84 (26.9% beat)
- Revenue guidance $177.5 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $170.9 million
- Market capitalization $1.31 billion
Revenue growth
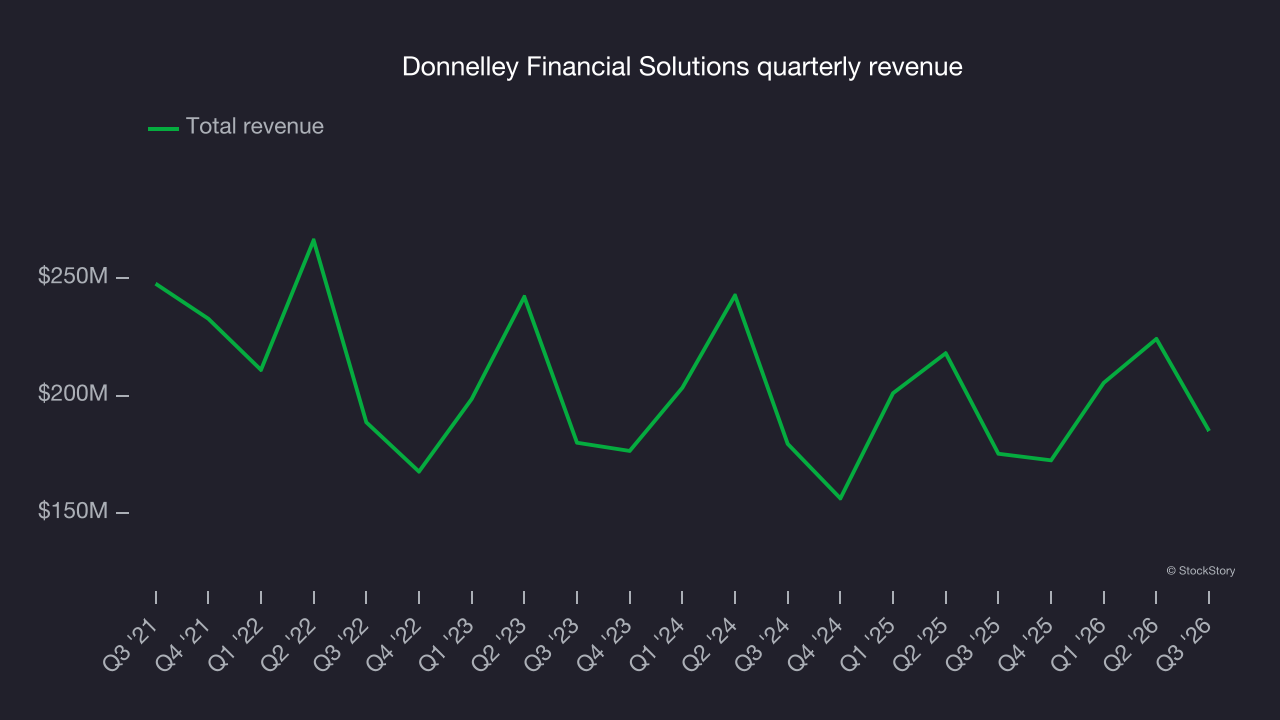
A company’s long-term revenue performance is one signal of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last five years, Donnelley Financial Solutions’s demand was weak and its revenue declined by 4.1% per year. That underwhelming result points to poor business quality.
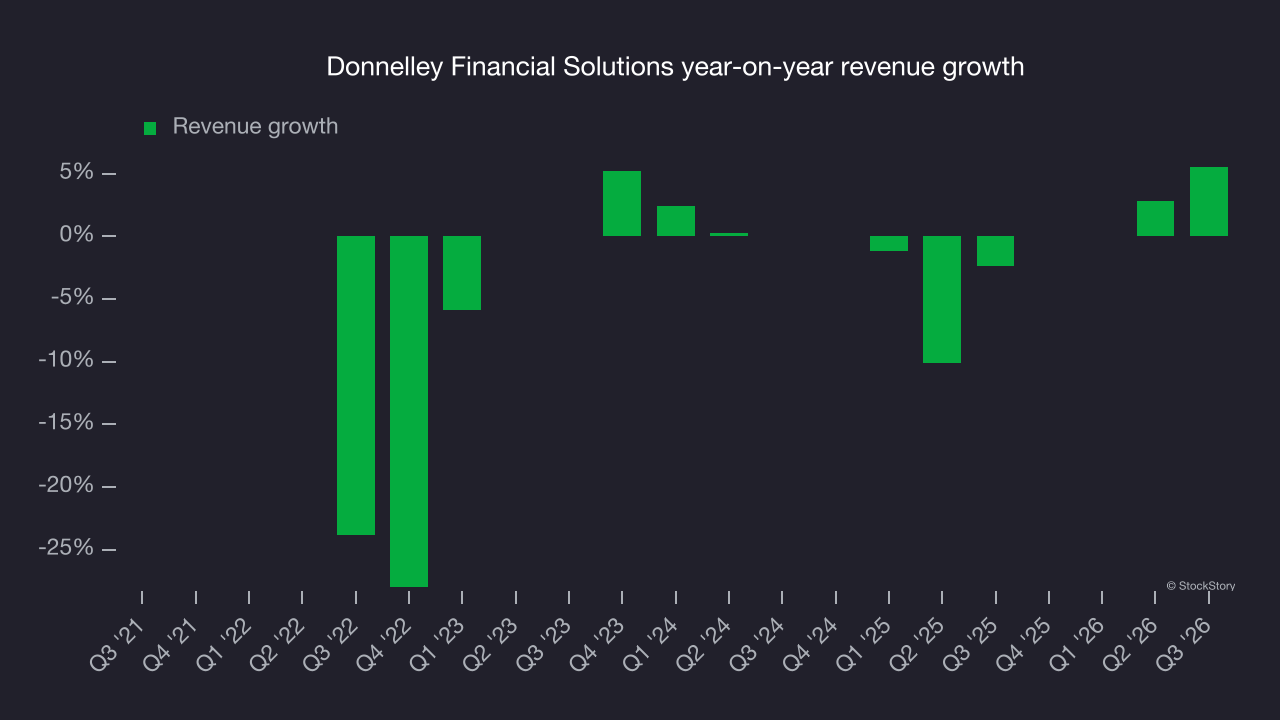
This quarter, Donnelley Financial Solutions reported year-on-year revenue growth of 5.5%, and its $185 million of revenue exceeded Wall Street’s consensus estimates by 2.8%. Company management is currently guiding for a 2.9% year-on-year increase in revenue next quarter.
Key takeaways from Donnelley Financial Solutions’s Q3 results
Donnelley Financial Solutions topped analysts’ consensus estimates for EPS and revenue in Q3, but EBITDA missed. We thought this was a good quarter, and shares rose 3.3% to $54.89 immediately after the results.
Donnelley Financial Solutions had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. When assessing whether it is a good investment, it’s important to consider its valuation and business quality, as well as what has happened in the latest quarter. For more on that, read our full research report here (it’s free).