Natural gas producer CNX Resources (NYSE: CNX) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 29.3% year on year to $580 million. Its GAAP profit of $1.12 per share was 70.1% above analysts’ consensus estimates.
For more on CNX Resources, read our free full research report.
CNX Resources (CNX) Q3 2026 highlights:
- Revenue $580 million vs S&P analysts’ consensus estimates of $471.1 million (29.3% year-on-year growth, 23.1% beat)
- EPS (GAAP) $1.12 vs analysts’ consensus estimates of $0.66 (70.1% beat)
- Operating margin 44.5%, down from 54.2% in the same quarter last year
- Free cash flow margin 19.7%, down from 35.3% in the same quarter last year
- Market capitalization $5.63 billion
Revenue growth
Cyclical industries such as energy can make mediocre companies look strong for a time, but a long-term view reveals which businesses can withstand and adapt to changing conditions. Over the last five years, CNX Resources grew its revenue at a weak 3.7% compounded annual growth rate. This was an underwhelming result compared to the rest of the energy upstream and integrated energy sector, but there are still things to like about CNX Resources.
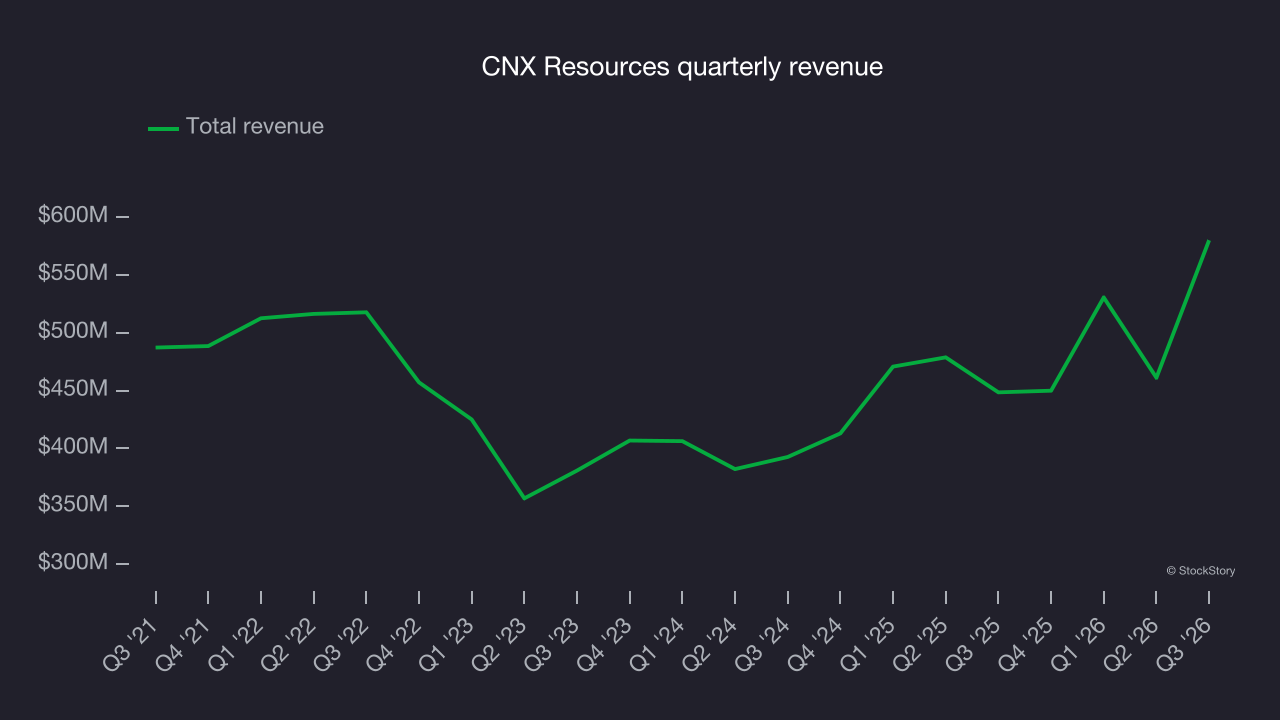
Even a long stretch in energy can be shaped by a single commodity cycle, so extending the view to ten years adds another perspective and reveals which companies are built to grow regardless of the pricing regime. CNX Resources’s annualized revenue growth of 3.4% over the last ten years aligns with its five-year trend, suggesting its demand was stable.
This quarter, CNX Resources reported strong year-on-year revenue growth of 29.3%, and its $580 million of revenue topped Wall Street’s consensus estimates by 23.1%.
Adjusted EBITDA margin
Adjusted EBITDA margin strips out accounting distortions tied to depletion and historical drilling spend, providing a clearer view of the cash-generating power of the underlying asset base before financing and reinvestment decisions.
CNX Resources has performed well over the last five years. It demonstrated strong profitability for an upstream and integrated energy business, with an average EBITDA margin of 64.2%.
Looking at the trend in its profitability, CNX Resources’s EBITDA margin rose by 3 percentage points over the last year, as its revenue growth gave it operating leverage.
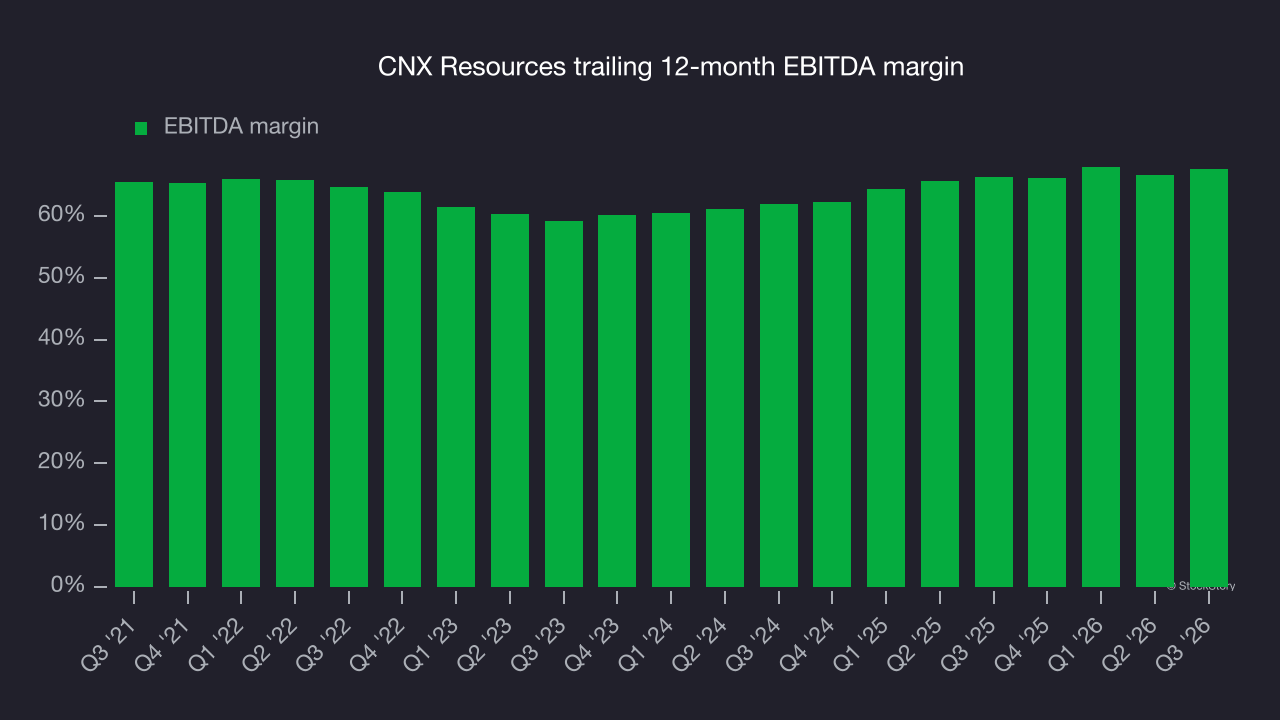
This quarter, CNX Resources reported an EBITDA margin of 68.9%, up 3.9 percentage points year on year. This increase was a positive development and shows it was more efficient. Its adjusted EBITDA beat Wall Street’s consensus estimates by 41.7%.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing wells are before financing and reinvestment decisions, but free cash flow shows how much value remains after paying the cost of replacing those wells. In upstream energy, production naturally declines over time, so companies must continuously reinvest just to stand still. A producer can report strong EBITDA margins yet generate little or no free cash flow if its wells decline quickly or if new drilling is expensive. Free cash flow therefore captures not only how efficiently a company produces hydrocarbons today, but also how costly it is to sustain that production into the future.
CNX Resources has shown strong cash profitability, driven by its profitable business model that enables it to reinvest, return capital to investors and stay ahead of the competition. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging 23.2% over the last five years.
While the level of free cash flow margins is important, their consistency matters just as much.
CNX Resources’s ratio of quarterly free cash flow volatility to Henry Hub gas-price volatility over the past five years was 1.5 (lower is better), indicating strong insulation from commodity swings. This stability supports superior capital access in downturns and positions CNX Resources to act as a consolidator when weaker peers are forced to retrench.
Why assess stability against commodity prices at the free cash flow level rather than compare revenue or EBITDA with Henry Hub natural gas prices for CNX Resources? What ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
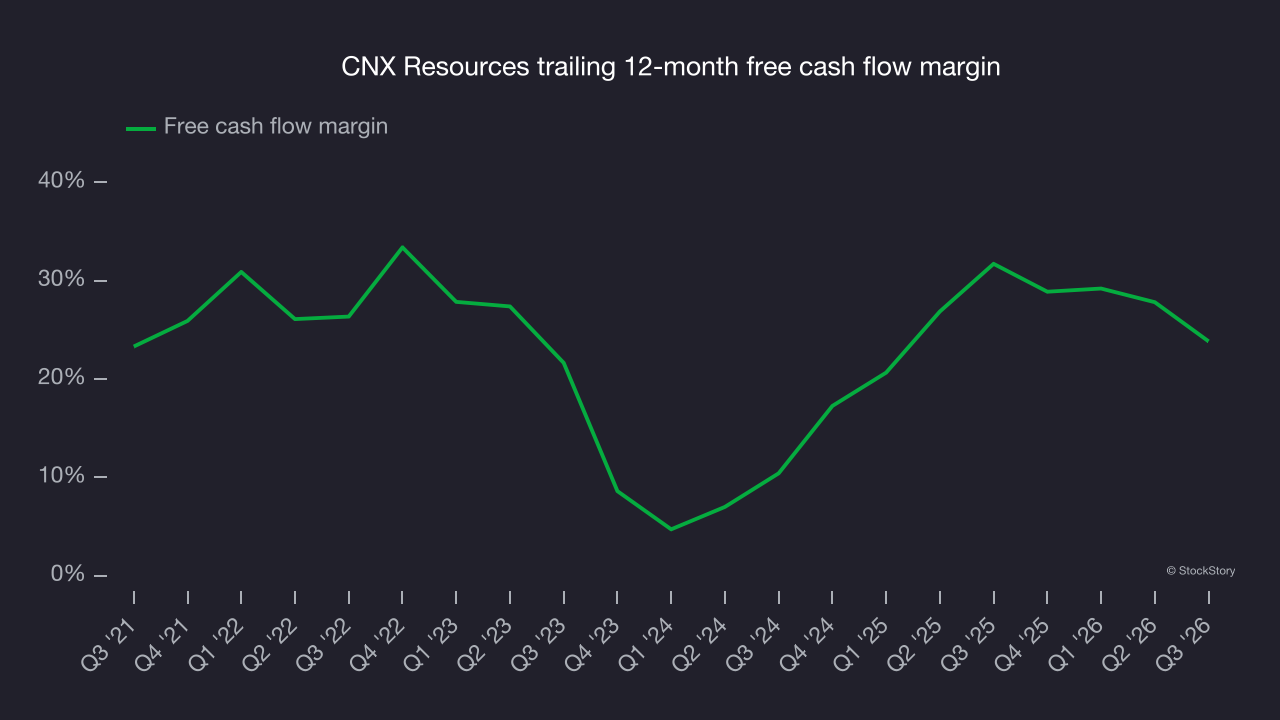
CNX Resources’s free cash flow totaled $114.4 million in Q3, equivalent to a 19.7% margin. The company’s cash profitability declined, with its margin 15.6 percentage points lower than in the same quarter last year, an unfavorable result considering its longer-term trend.
Key takeaways from CNX Resources’s Q3 results
CNX Resources delivered a solid quarter, with revenue beating Wall Street’s consensus estimates by a wide margin and EPS also topping analysts’ consensus estimates. Shares remained flat at $38.33 immediately after the results.
CNX Resources may have had a good quarter, but that alone doesn’t determine whether the stock is a buy. That decision calls for a broader look at valuation, business quality and the latest earnings. For more on CNX Resources, read our free full research report here.