Safety and specialty services provider APi (NYSE: APG) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 22.5% year on year to $2.55 billion. The company’s full-year revenue guidance of $9.23 billion at the midpoint came in 2.6% above analysts’ consensus estimates. Its non-GAAP profit of $0.50 per share was 6.3% above analysts’ consensus estimates.
For more on APi, read our free full research report.
APi (APG) Q3 2026 highlights:
- Revenue $2.55 billion vs S&P analysts’ consensus estimates of $2.40 billion (22.5% year-on-year growth, 6.3% beat)
- Adjusted EPS $0.50 vs S&P analysts’ consensus estimates of $0.47 (6.3% beat)
- Adjusted EBITDA $350 million vs analysts’ consensus estimates of $332.7 million (13.7% margin, 5.2% beat)
- Revenue guidance The company lifted its revenue guidance for the full year to $9.23 billion at the midpoint from $8.95 billion, a 3.1% increase
- EBITDA guidance $1.25 billion at the midpoint for the full year, above analysts’ consensus estimates of $1.23 billion
- Operating margin 7.9%, in line with the same quarter last year
- Free cash flow margin 7.8%, down from 9.6% in the same quarter last year
- Organic revenue rose 15.7% year on year (beat)
- Market capitalization $17.87 billion
NEW BRIGHTON, Minn.--(BUSINESS WIRE)--APi Group Corporation (NYSE: APG) (“APi” or the “Company”) today reported its financial results for the three and nine months ended September 30, 2026.
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. APi’s revenue grew at a strong 19.2% compounded annual growth rate over the last five years. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
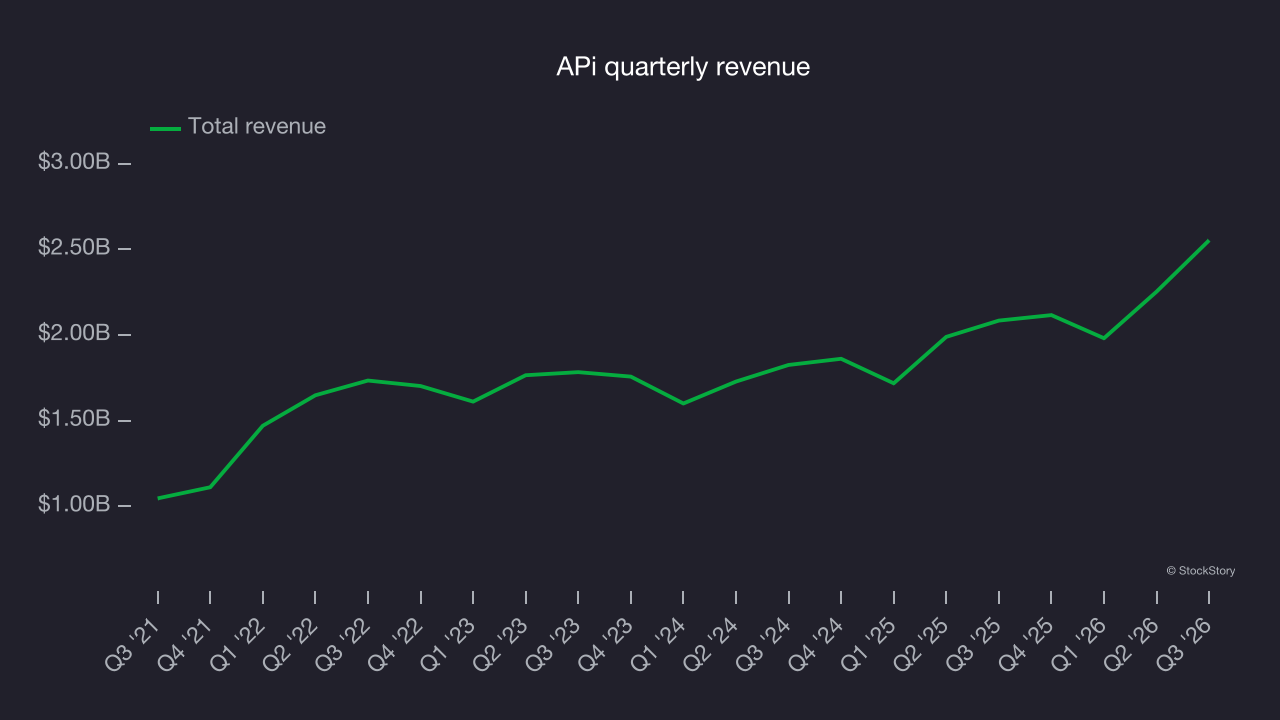
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. APi’s annualized revenue growth of 13.5% over the last two years is below its five-year trend, but the results still suggest healthy demand. 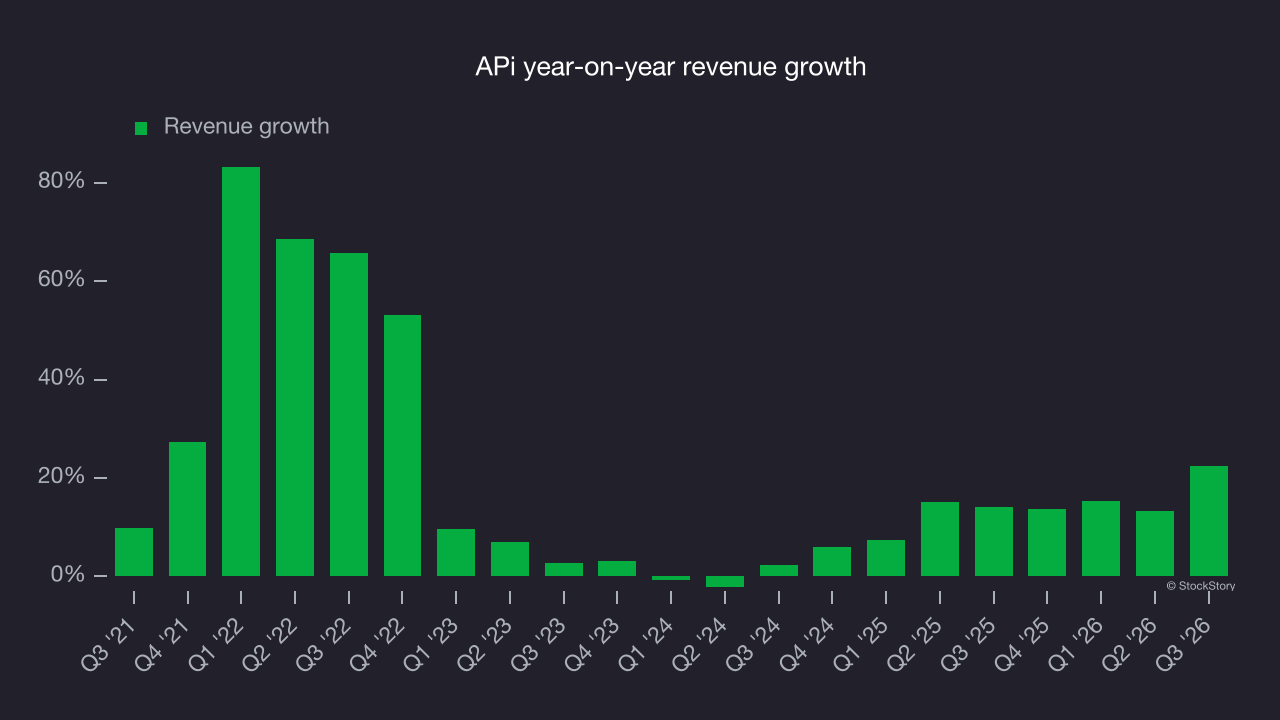
A closer look at the company’s revenue dynamics comes from analyzing its organic revenue, which strips out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, APi’s organic revenue averaged 8.6% year-on-year growth. Total revenue growth outpaced organic growth over that period, indicating that some combination of acquisitions and foreign exchange rates boosted its headline results. 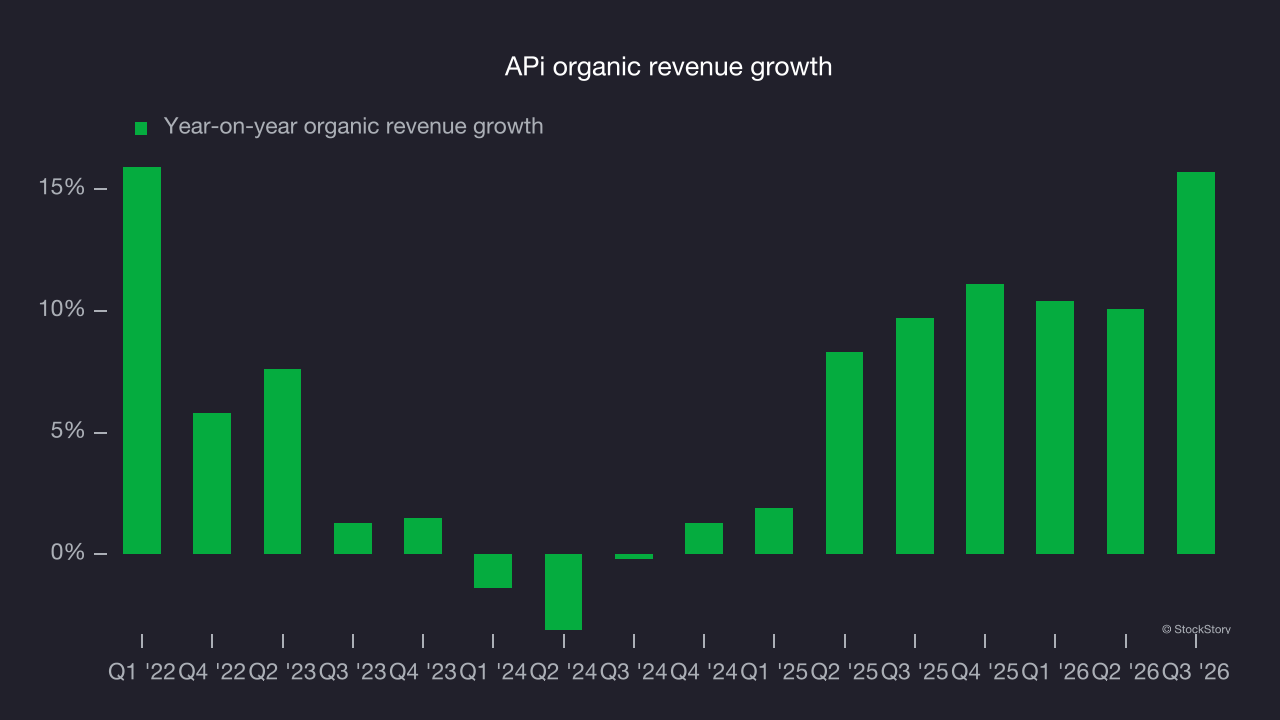
This quarter, APi reported year-on-year revenue growth of 22.5%, and its $2.55 billion of revenue topped Wall Street’s consensus estimates by 6.3%.
Looking ahead, sell-side analysts expect revenue to grow 7.1% over the next 12 months, according to S&P, a deceleration versus the last two years. This underwhelming projection implies its products and services will face some demand challenges. Still, the company is performing well on other measures of financial health.
Operating margin
APi was profitable over the last five years but held back by its large cost base. Its average operating margin of 5.7% was weak for an industrials business. That outcome is unsurprising given its low gross margin baseline.
On the positive side, APi’s operating margin rose by 4.5 percentage points over the last five years, as its revenue growth provided operating leverage.
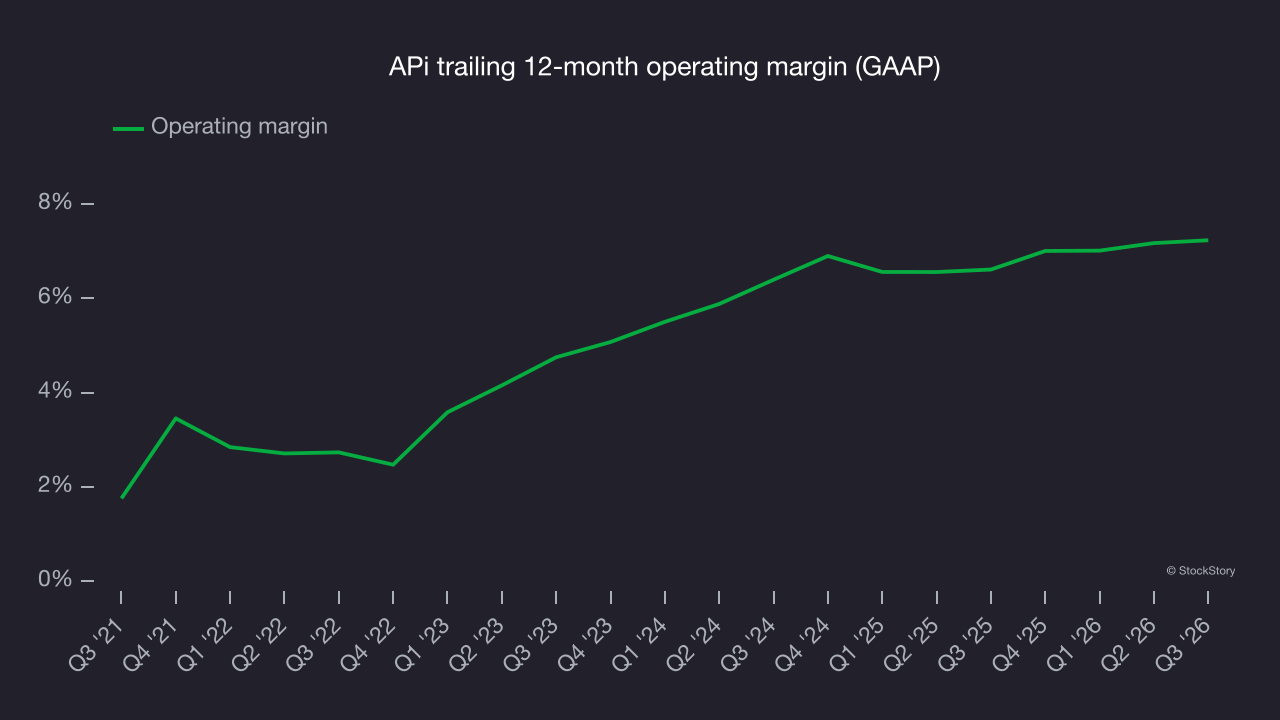
In Q3, APi generated an operating margin of 7.9%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
APi’s strong 17.9% annual EPS growth over the last five years aligns with its revenue performance. This indicates its incremental revenue was profitable.
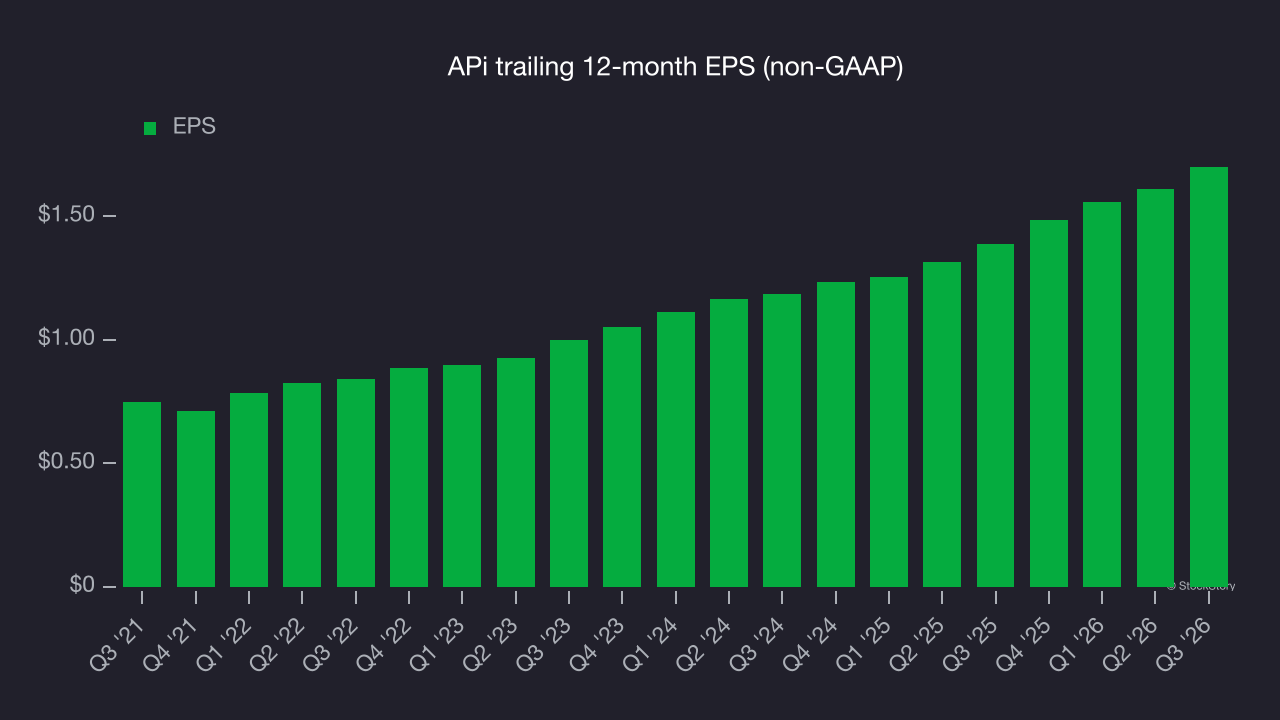
As with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For APi, its two-year annual EPS growth of 19.7% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high base.
In Q3, APi reported adjusted EPS of $0.50, up from $0.41 in the same quarter last year. This result beat analysts’ consensus estimates by 6.3%. Over the next 12 months, Wall Street expects APi’s full-year EPS to grow 12.5% from $1.70 to $1.91, according to S&P.
Key takeaways from APi’s Q3 results
APi delivered a solid quarter, with organic revenue well above analysts’ consensus estimates and next-quarter EBITDA guidance ahead of Wall Street’s consensus. Those were key positives in the report. Shares rose 4.3% to $43.15 immediately after the release.
APi had a solid quarter, but the broader investment case matters too. When deciding whether to invest, the latest quarter matters, but not as much as longer-term business quality and valuation. For more on APi, read the full research report here (it’s free).