

Financial services company Bread Financial (NYSE: BFH) met Wall Street’s revenue expectations in Q3 2026, with sales up 4.7% year on year to $1.02 billion. Its non-GAAP profit of $3.84 per share was 18.8% above analysts’ consensus estimates.
Is now the time to buy Bread Financial? Find out by accessing our full research report, it’s free.
Bread Financial (BFH) Q3 2026 highlights:
- Net Interest Income: $1.10 billion vs analyst estimates of $1.09 billion
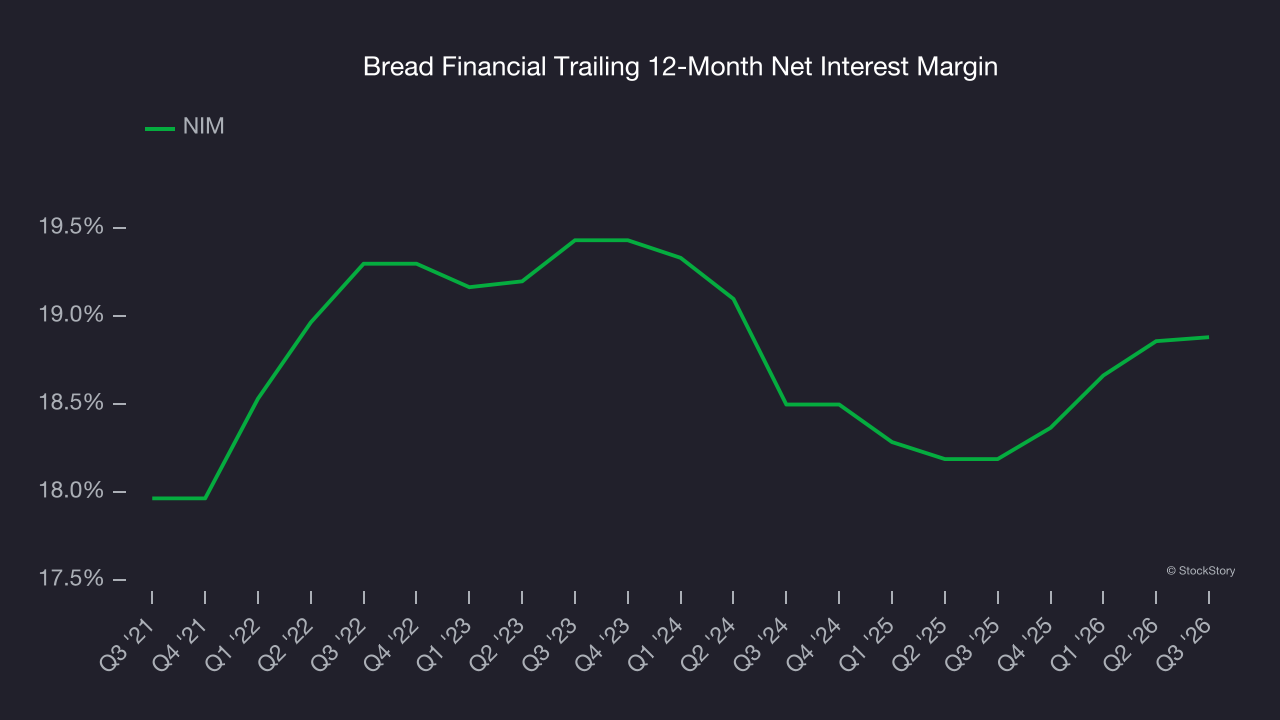
- Net Interest Margin: 18.9% vs analyst estimates of 19.1% (17 basis point miss)
- Revenue: $1.02 billion vs analyst estimates of $1.01 billion (4.7% year-on-year growth, in line)
- Efficiency Ratio: 47.9% vs analyst estimates of 49.2% (127 basis point beat)
- Adjusted EPS: $3.84 vs analyst estimates of $3.23 (18.8% beat)
- Market Capitalization: $4.17 billion
Company overview
Formerly known as Alliance Data Systems until its 2022 rebranding, Bread Financial (NYSE: BFH) provides credit cards, installment loans, and savings products to consumers while powering branded payment solutions for retailers and merchants.
Revenue growth
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Bread Financial grew its revenue at a tepid 4.7% compounded annual growth rate. This fell short of our benchmark for the financials sector and is a poor baseline for our analysis.
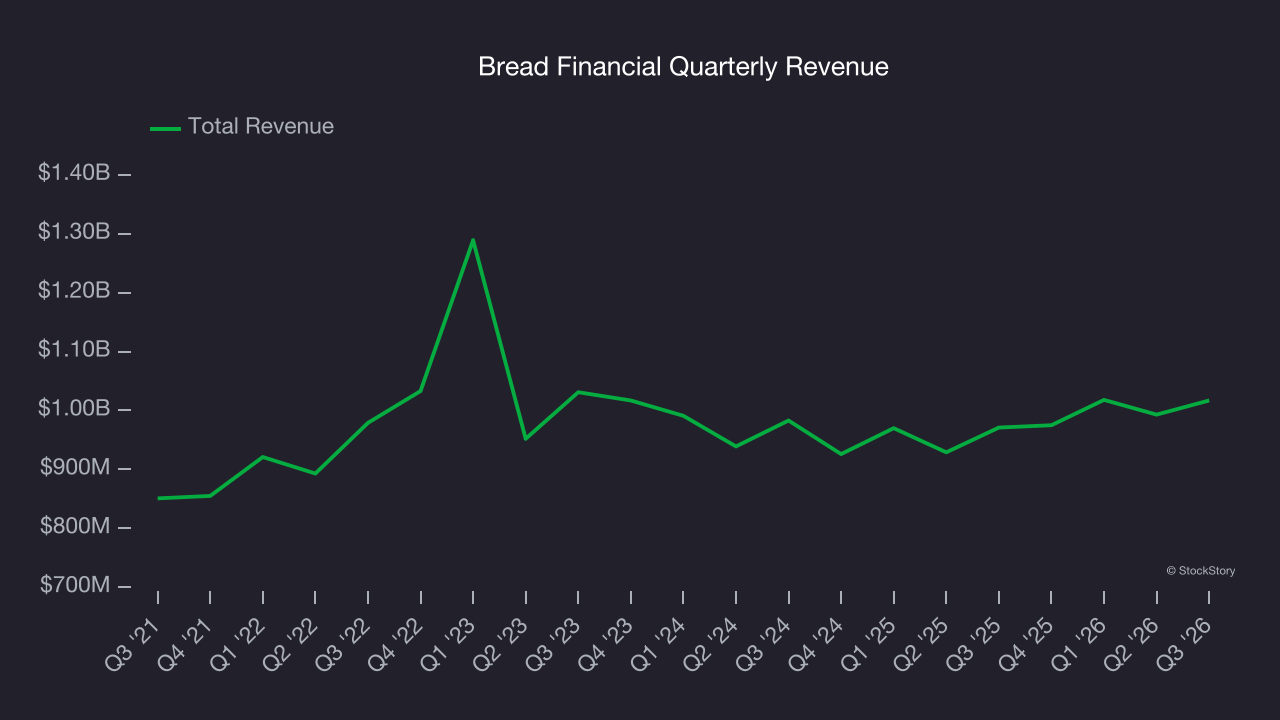
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Bread Financial’s recent performance shows its demand has slowed as its revenue was flat over the last two years. 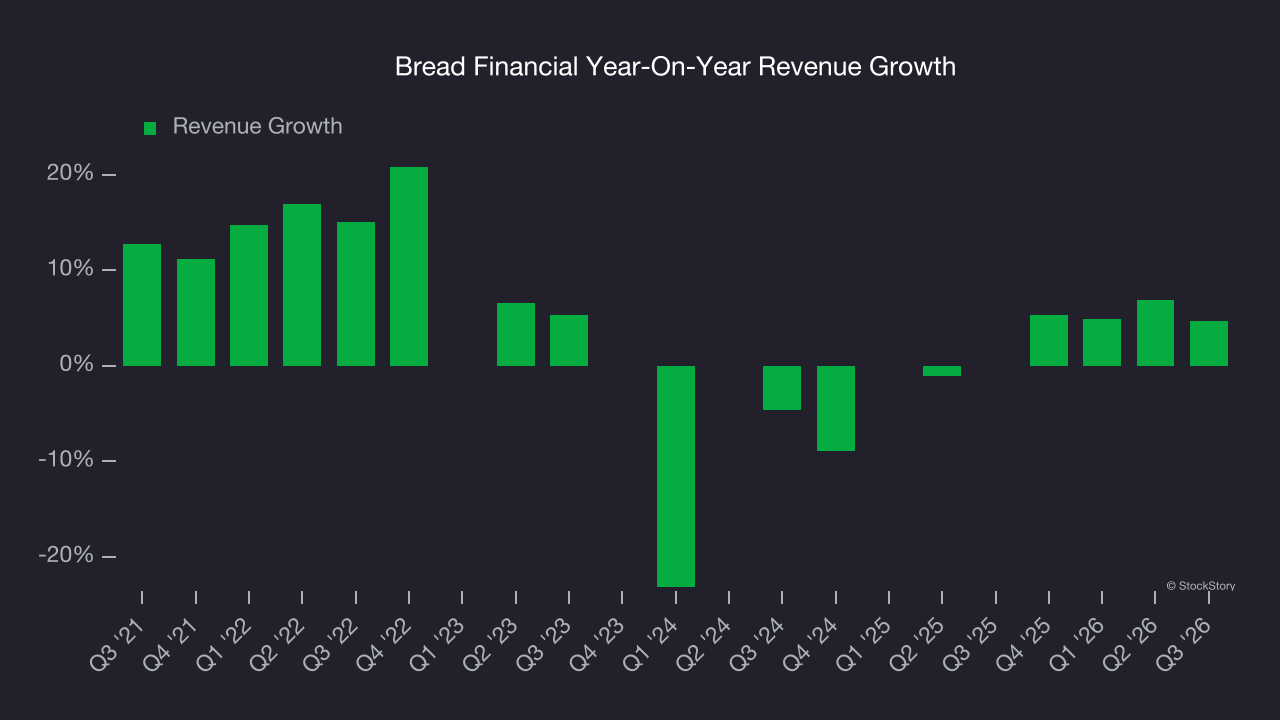 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Bread Financial grew its revenue by 4.7% year on year, and its $1.02 billion of revenue was in line with Wall Street’s estimates.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Net interest margin
Net interest margin (NIM) represents the unit economics of a financial institution by measuring the profitability of its interest-bearing assets relative to its interest-bearing liabilities. It’s a fundamental metric that investors use to assess lending premiums and returns.
Bread Financial’s net interest margin has increased by 91.6 and 38.3 basis points (100 basis points = 1 percentage point) over the last five and two years, respectively. These rates of change were better than the broader financials industry. The firm’s NIM for the trailing 12 months was 18.9%.
Key takeaways from Bread Financial’s Q3 results
It was good to see Bread Financial beat analysts’ EPS expectations this quarter. We were also happy its net interest income narrowly outperformed Wall Street’s estimates. On the other hand, its net interest margin missed and its efficiency ratio fell short of Wall Street’s estimates. Overall, we think this was still a solid quarter with some key areas of upside. The stock remained flat at $108.47 immediately after reporting.
Bread Financial put up rock-solid earnings, but one quarter doesn’t necessarily make the stock a buy. Let’s see if this is a good investment. When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).