

Hotel franchising company Wyndham (NYSE: WH) met Wall Street’s revenue expectations in Q3 2026, with sales up 7.3% year on year to $410 million. The company’s full-year revenue guidance of $1.49 billion at the midpoint came in 0.5% above analysts’ estimates. Its non-GAAP profit of $1.43 per share was 8.5% above analysts’ consensus estimates.
Is now the time to buy Wyndham? Find out by accessing our full research report, it’s free.
Wyndham (WH) Q3 2026 highlights:
- Revenue: $410 million vs analyst estimates of $410.2 million (7.3% year-on-year growth, in line)
- Adjusted EPS: $1.43 vs analyst estimates of $1.32 (8.5% beat)
- Adjusted EBITDA: $207 million vs analyst estimates of $199.2 million (50.5% margin, 3.9% beat)
- The company reconfirmed its revenue guidance for the full year of $1.49 billion at the midpoint
- Management raised its full-year Adjusted EPS guidance to $4.88 at the midpoint, a 2.3% increase
- EBITDA guidance for the full year is $742.5 million at the midpoint, in line with analyst expectations
- Operating Margin: 42%, down from 46.6% in the same quarter last year
- Free Cash Flow Margin: 24.4%, up from 19.6% in the same quarter last year
- RevPAR: $51.13 at quarter end, up 2.2% year on year
- Market Capitalization: $5.74 billion
"Our third quarter results demonstrate our team's continued execution and the strength of Wyndham's asset-light, highly cash-generative business model," said Geoff Ballotti, President and Chief Executive Officer. "We delivered broad-based U.S. RevPAR growth outperforming our initial expectations, as well as market share gains. Additionally, we grew our system and development pipeline each by 4% and increased royalties and franchise fees by 6%, as we continued to invest in industry-leading technology, loyalty and distribution initiatives that support franchisee profitability and customer satisfaction. Our strong balance sheet and cash flow generation capabilities provide significant opportunities to continue enhancing returns to our shareholders over both the short and long-term, as evidenced by our Board of Directors' approval of a $400 million increase in our share repurchase authorization."
Company overview
Established in 1981, Wyndham (NYSE: WH) is a global hotel franchising company with over 9,000 hotels across nearly 95 countries on six continents.
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Unfortunately, Wyndham struggled to consistently increase demand as its $1.45 billion of sales for the trailing 12 months was close to its revenue five years ago. This was below our standards and suggests it’s a low quality business.
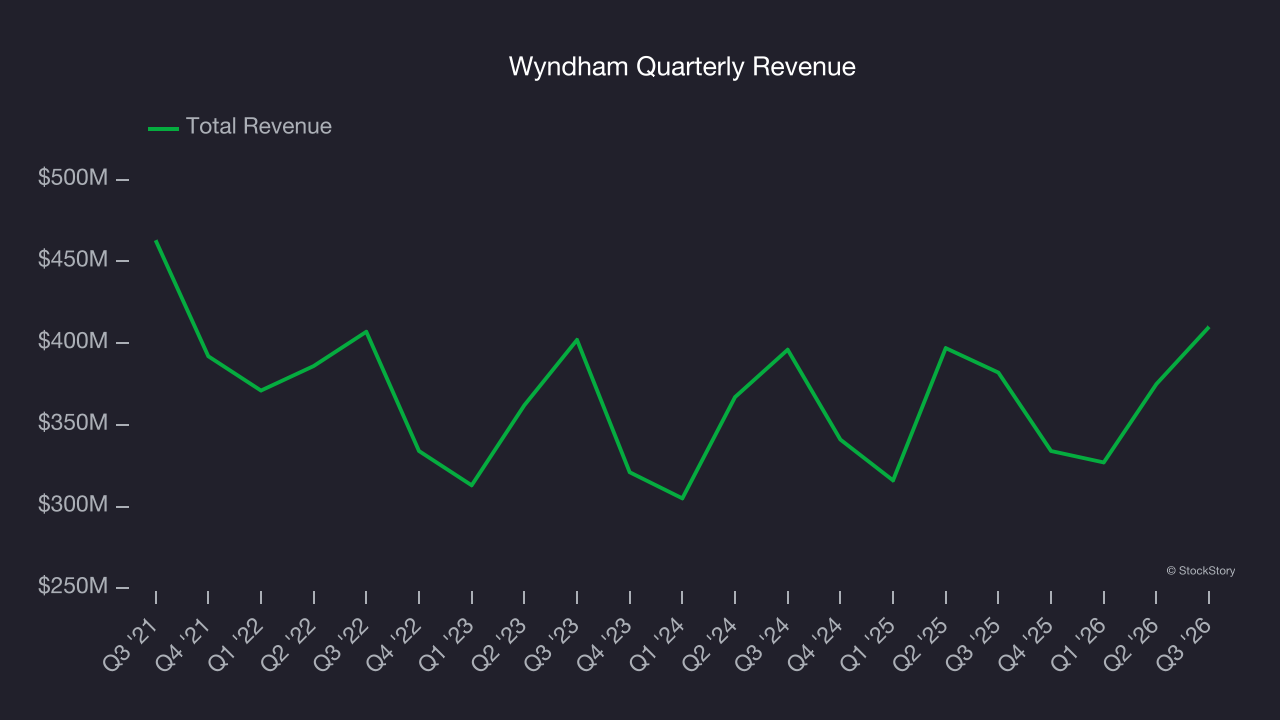
We at StockStory place the most emphasis on long-term growth, but within consumer discretionary, a stretched historical view may miss a company riding a successful new property or trend. Wyndham’s annualized revenue growth of 2% over the last two years is above its five-year trend, which is encouraging. 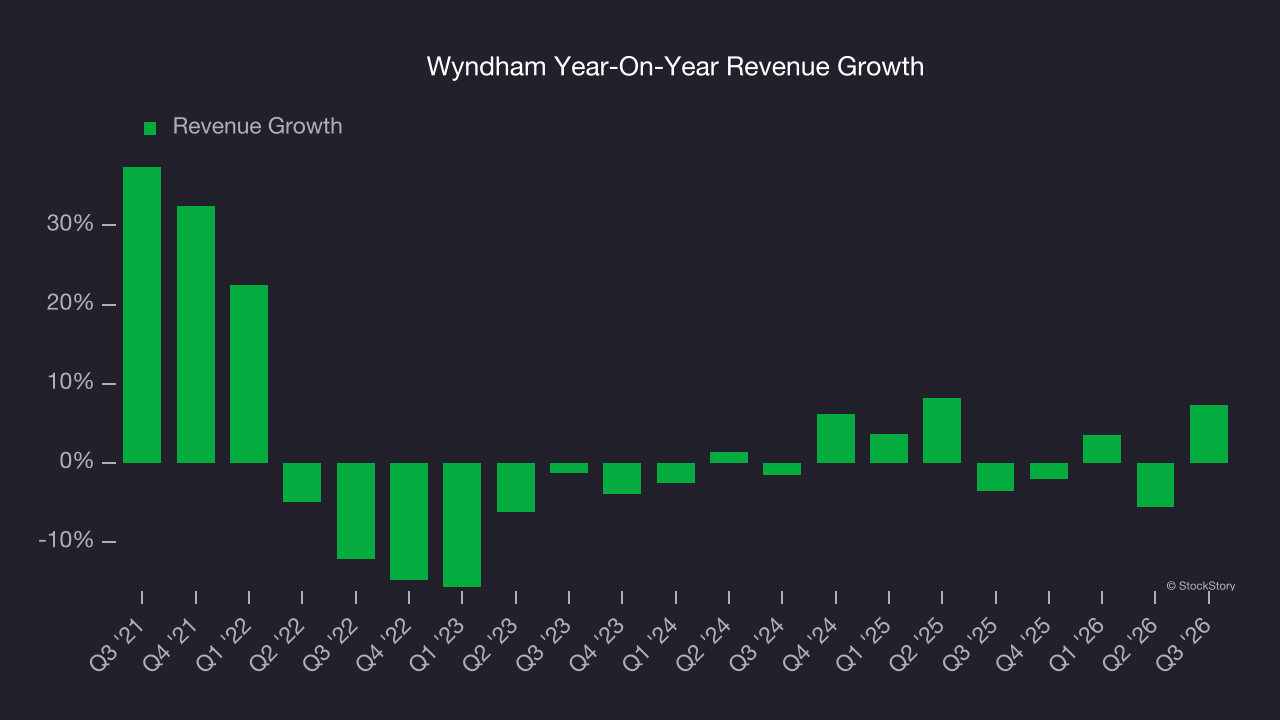
Wyndham also reports revenue per available room, which clocked in at $51.13 this quarter and is a key metric accounting for daily rates and occupancy levels. Over the last two years, Wyndham’s revenue per room averaged 2.8% year-on-year growth, which is quite underwhelming. This number doesn’t surprise us as it’s in line with its revenue growth. It is sometimes the strategy of hotels to grow ancillary revenues because they are price takers in room revenues. 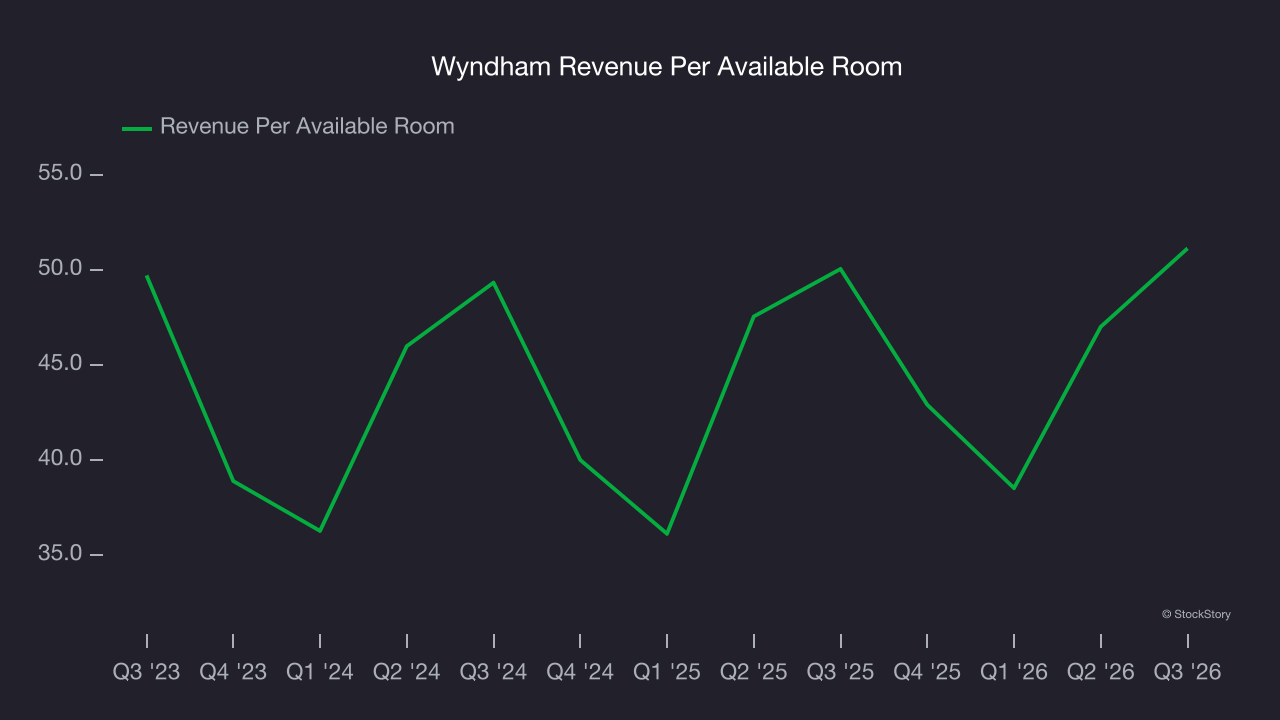
This quarter, Wyndham grew its revenue by 7.3% year on year, and its $410 million of revenue was in line with Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 7.4% over the next 12 months. Although this projection indicates its newer products and services will catalyze better top-line performance, it is still below average for the sector.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Operating margin
Wyndham’s operating margin has been trending down over the last 12 months and averaged 34.5% over the last two years. The company’s profitability was mediocre for a consumer discretionary business and shows it couldn’t pass its higher operating expenses onto its customers.
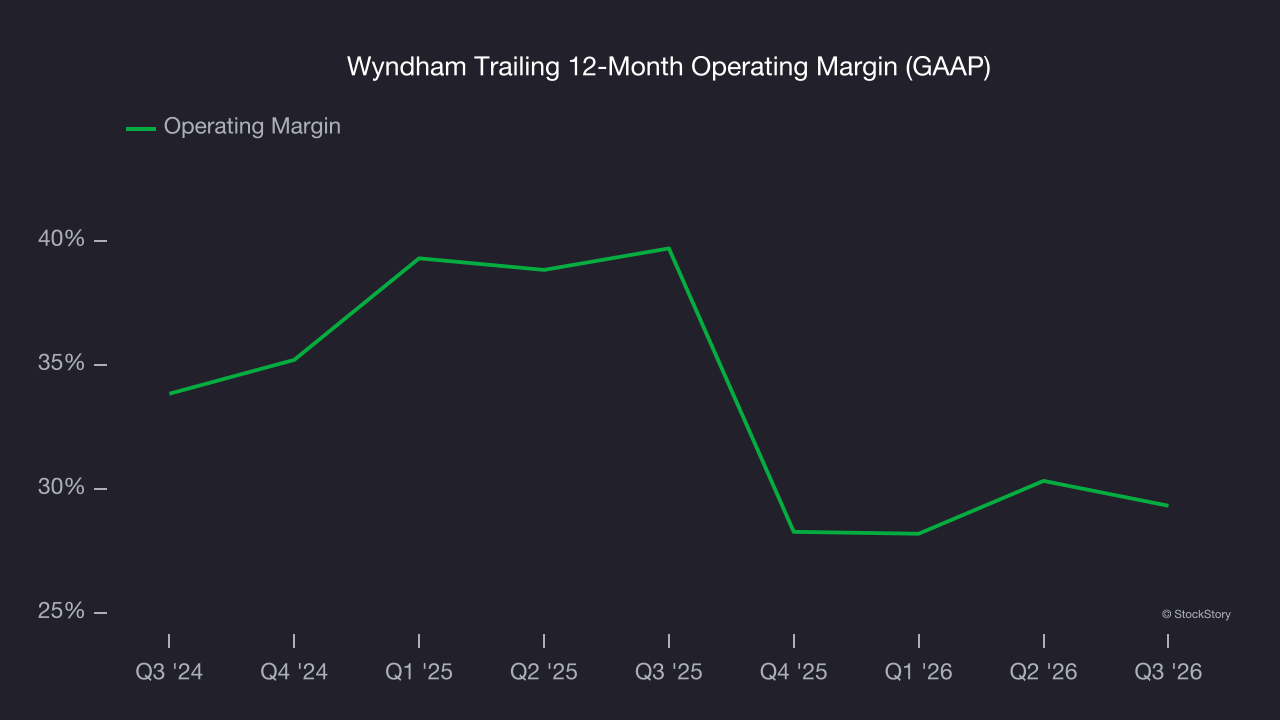
In Q3, Wyndham generated an operating margin profit margin of 42%, down 4.6 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Wyndham’s EPS grew at 13.6% compounded annual growth rate over the last five years. On the bright side, this performance was better than its flat revenue and tells us management responded to softer demand by adapting its cost structure.
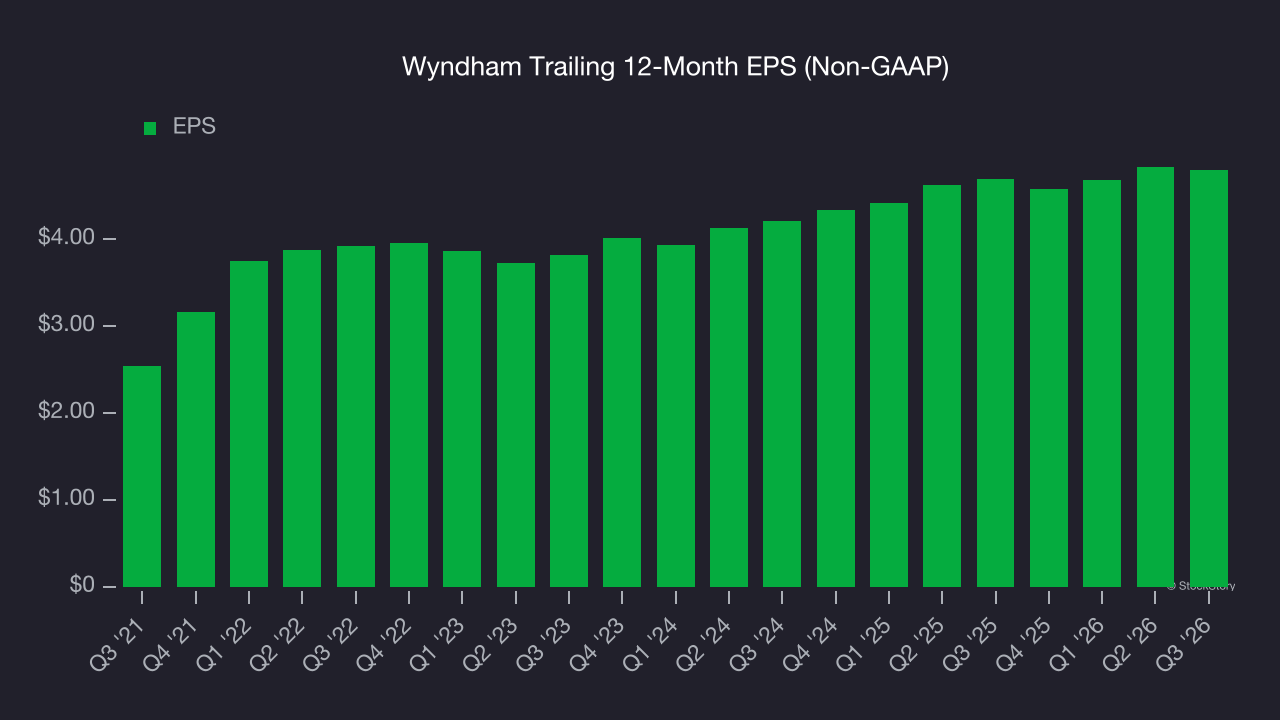
In Q3, Wyndham reported adjusted EPS of $1.43, down from $1.46 in the same quarter last year. Despite falling year on year, this print beat analysts’ estimates by 8.4%. Over the next 12 months, Wall Street expects Wyndham’s full-year EPS to grow 6.5% from $4.80 to $5.11.
Key takeaways from Wyndham’s Q3 results
It was good to see Wyndham beat analysts’ EPS expectations this quarter. We were also glad its full-year revenue guidance slightly exceeded Wall Street’s estimates. Overall, this print had some key positives. The stock traded up 3% to $80.70 immediately following the results.
So should you invest in Wyndham right now? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).