

Freight rail services provider CSX (NASDAQ: CSX) reported revenue ahead of Wall Street’s expectations in Q3 2026, with sales up 12% year on year to $4.02 billion. Its GAAP profit of $0.57 per share was 7.3% above analysts’ consensus estimates.
Is now the time to buy CSX? Find out by accessing our full research report, it’s free.
CSX (CSX) Q3 2026 highlights:
- Revenue: $4.02 billion vs analyst estimates of $3.94 billion (12% year-on-year growth, 1.8% beat)
- EPS (GAAP): $0.57 vs analyst estimates of $0.53 (7.3% beat)
- Operating Margin: 39.1%, up from 30.3% in the same quarter last year
- Free Cash Flow Margin: 25.5%, up from 17.3% in the same quarter last year
- Sales Volumes fell 99.7% year on year (1.4% in the same quarter last year)
- Market Capitalization: $89.06 billion
Company overview
Established as part of the Chessie System and Seaboard Coast Line Industries merger, CSX (NASDAQ: CSX) is a transportation company specializing in freight rail services.
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Unfortunately, CSX’s 4.6% annualized revenue growth over the last five years was tepid. This fell short of our benchmark for the industrials sector and is a rough starting point for our analysis.
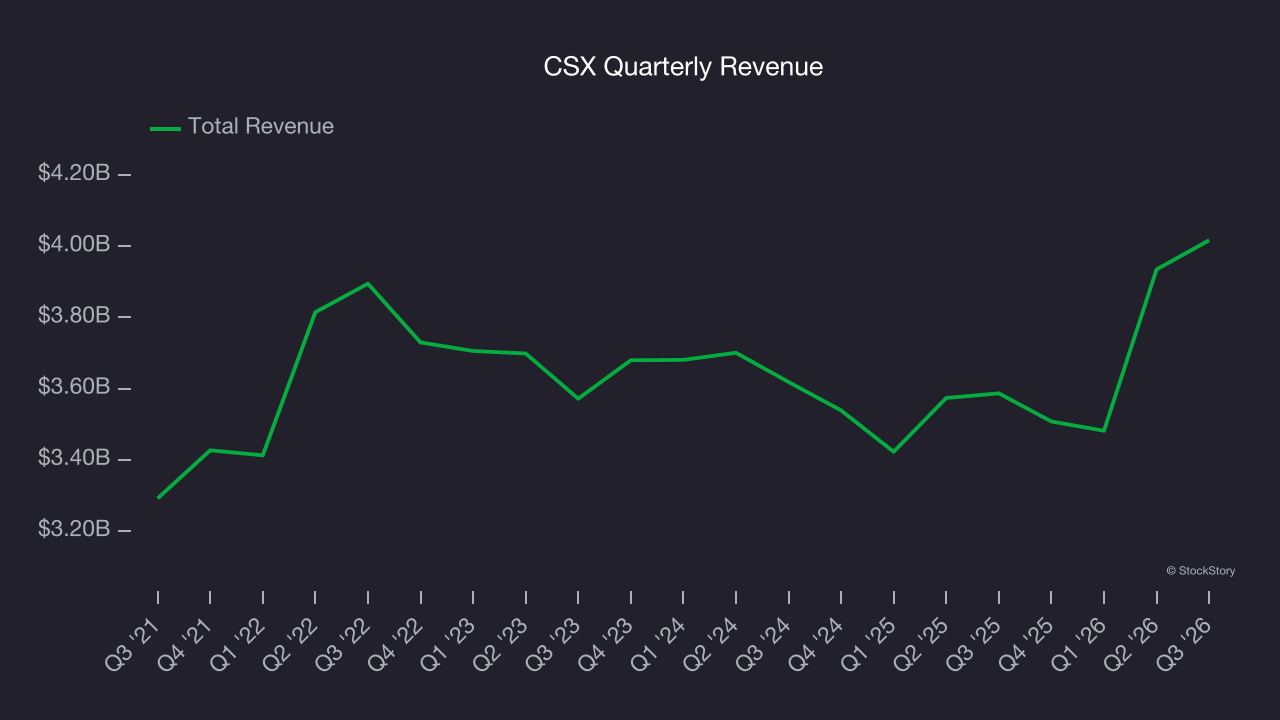
We at StockStory place the most emphasis on long-term growth, but within industrials, a half-decade historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. CSX’s recent performance shows its demand has slowed as its revenue was flat over the last two years. 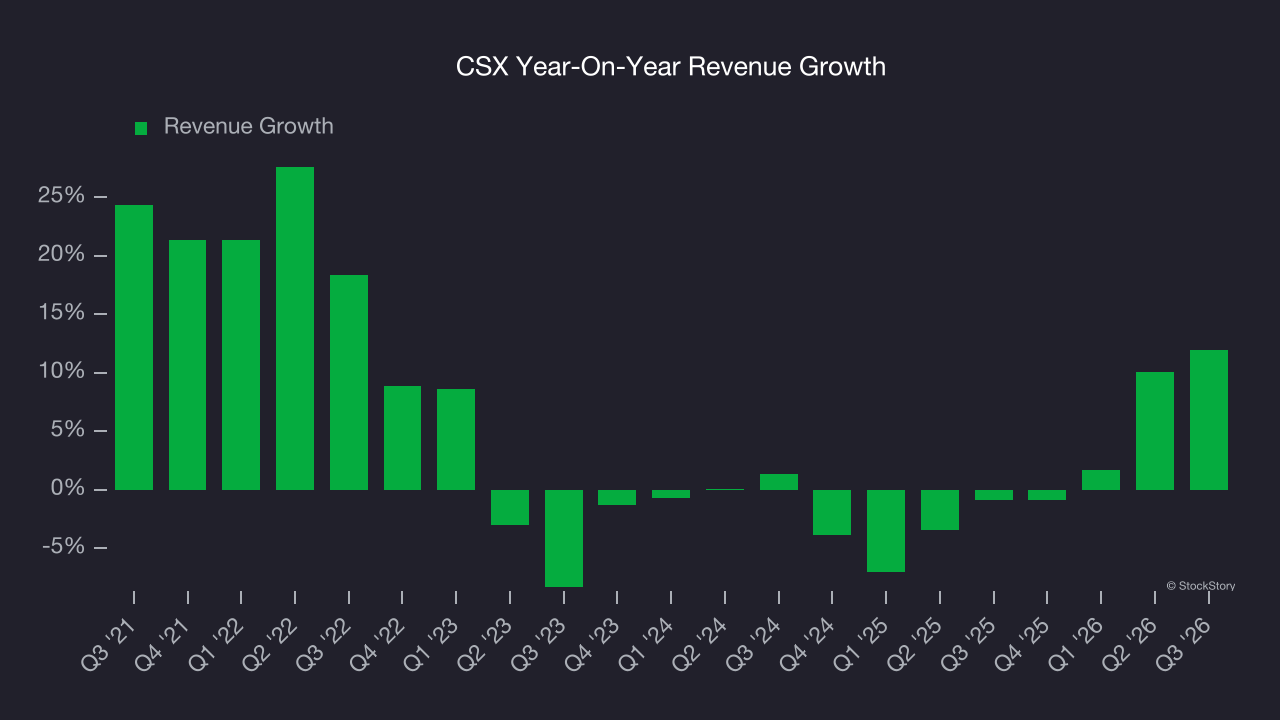
We can dig further into the company’s revenue dynamics by analyzing its number of units sold, which reached 5,000 in the latest quarter. Over the last two years, CSX’s units sold averaged 12.7% year-on-year declines. Because this number is lower than its revenue growth, we can see the company benefited from price increases. 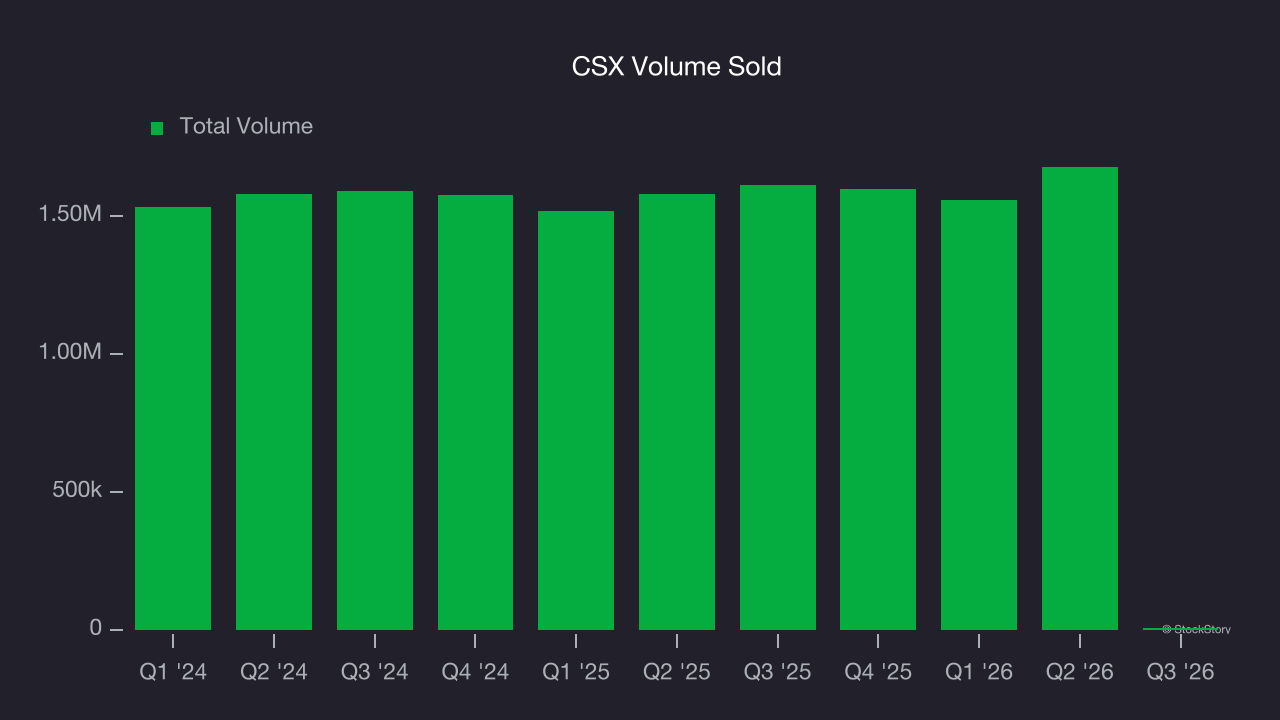
This quarter, CSX reported year-on-year revenue growth of 12%, and its $4.02 billion of revenue exceeded Wall Street’s estimates by 1.8%.
Looking ahead, sell-side analysts expect revenue to grow 7.3% over the next 12 months. While this projection indicates its newer products and services will spur better top-line performance, it is still below average for the sector.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
CSX has been a well-oiled machine over the last five years. It demonstrated elite profitability for an industrials business, boasting an average operating margin of 37%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
Analyzing the trend in its profitability, CSX’s operating margin decreased by 4.4 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
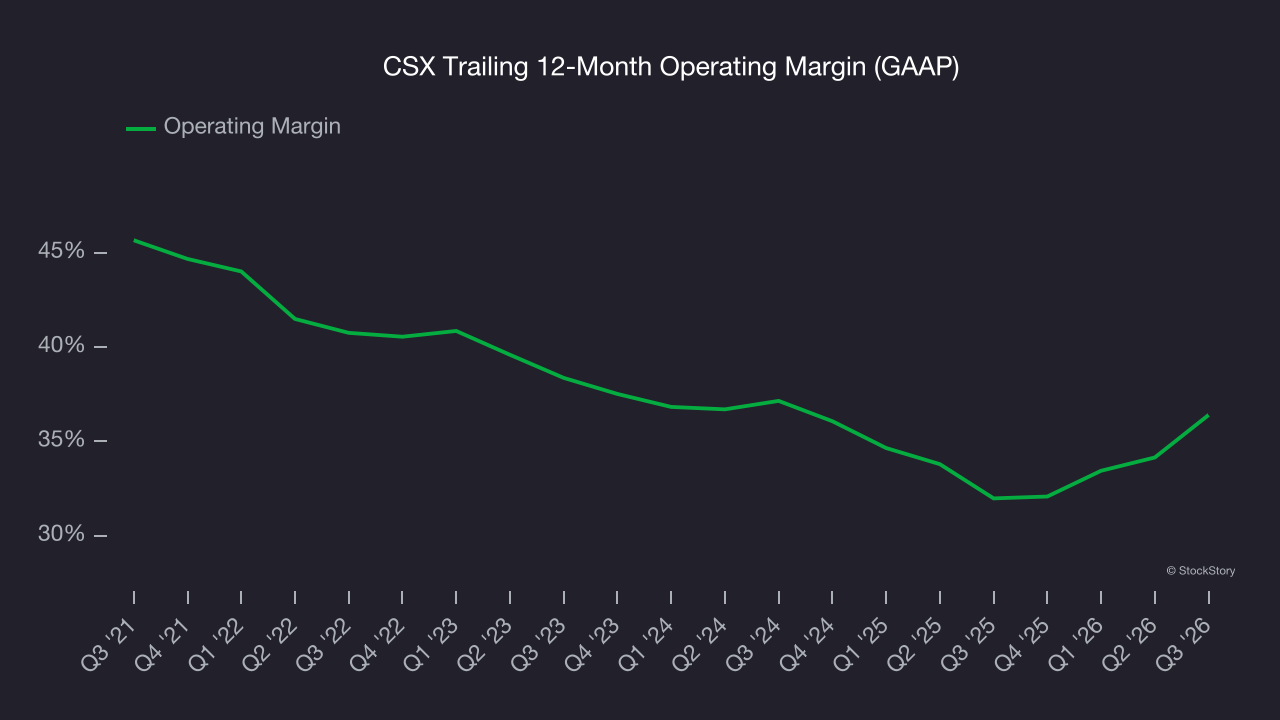
This quarter, CSX generated an operating margin profit margin of 39.1%, up 8.8 percentage points year on year. The increase was solid, and because its operating margin rose more than its gross margin, we can infer it was more efficient with expenses such as marketing, R&D, and administrative overhead.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
CSX’s weak 4% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
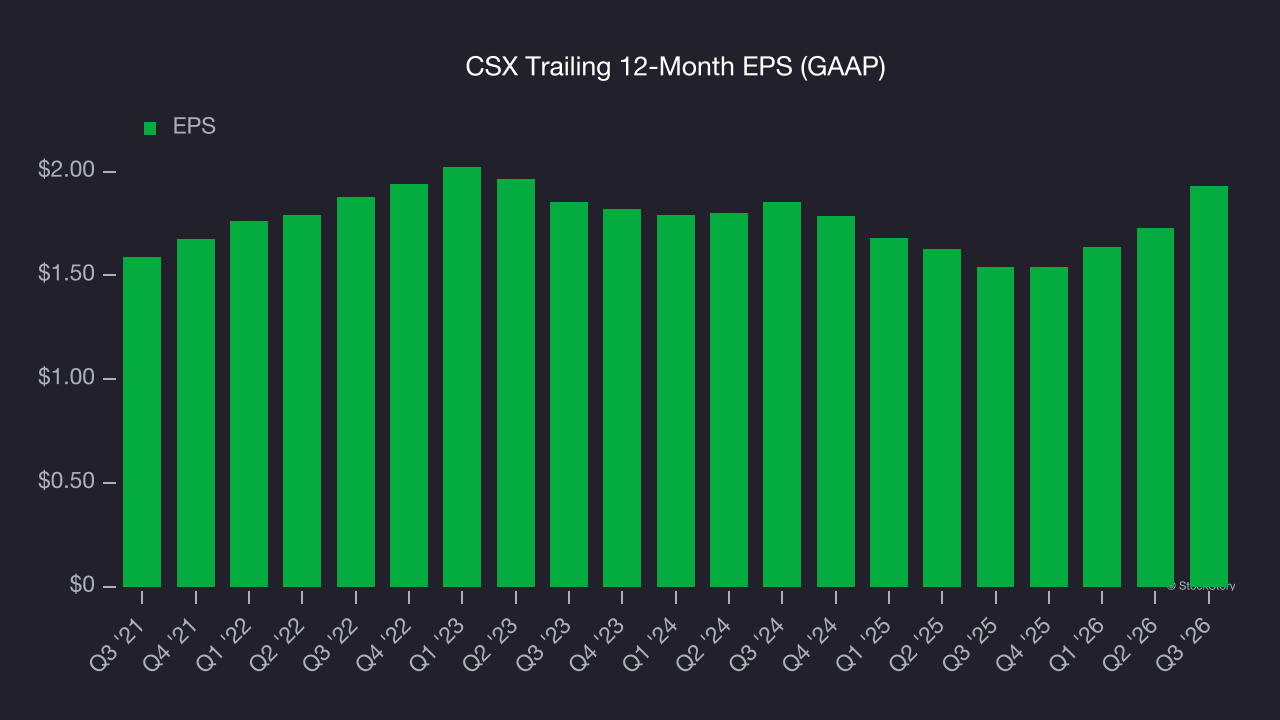
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For CSX, its two-year annual EPS growth of 2.1% was lower than its five-year trend. We hope its growth can accelerate in the future.
In Q3, CSX reported EPS of $0.57, up from $0.37 in the same quarter last year. This print beat analysts’ estimates by 7.3%. Over the next 12 months, Wall Street expects CSX’s full-year EPS to grow 16% from $1.93 to $2.24.
Key takeaways from CSX’s Q3 results
We enjoyed seeing CSX beat analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Overall, we think this was a decent quarter with some key metrics above expectations. The stock traded up 4.3% to $50.38 immediately after reporting.
CSX put up rock-solid earnings, but one quarter doesn’t necessarily make the stock a buy. Let’s see if this is a good investment. When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).