

Fortune Brands has been treading water for the past six months, recording a small loss of 1.6% while holding steady at $40.70. The stock also fell short of the S&P 500’s 7.7% gain during that period.
Is now the time to buy Fortune Brands, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Fortune Brands Will Underperform?
We’re cautious about Fortune Brands. Here are three reasons why there are better opportunities than FBIN, plus one stock we’d rather own.
1. Core Business Falling Behind as Demand Plateaus
Investors interested in Home Construction Materials companies should track organic revenue in addition to reported revenue. This metric gives visibility into Fortune Brands’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Fortune Brands failed to grow its organic revenue. This performance was underwhelming and implies it may need to improve its products, pricing, or go-to-market strategy. It also suggests Fortune Brands might have to lean into acquisitions to accelerate growth, which isn’t ideal because M&A can be expensive and risky (integrations often disrupt focus). 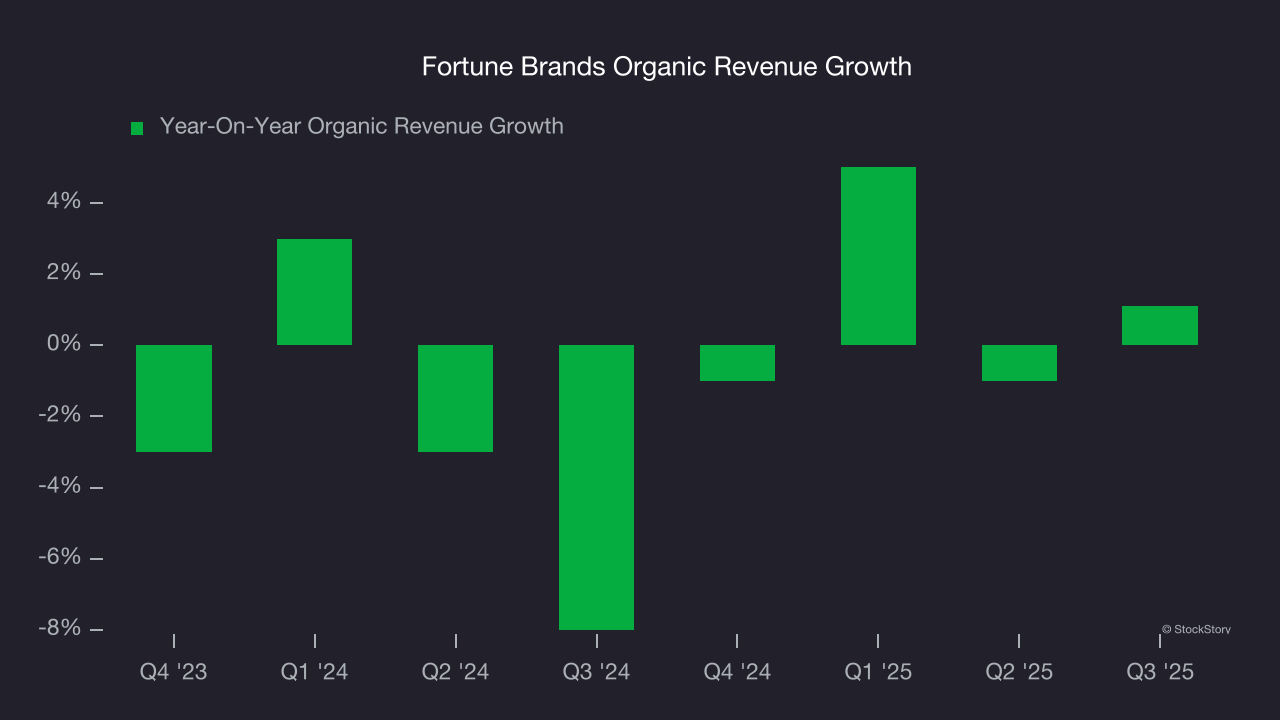
2. Shrinking Operating Margin
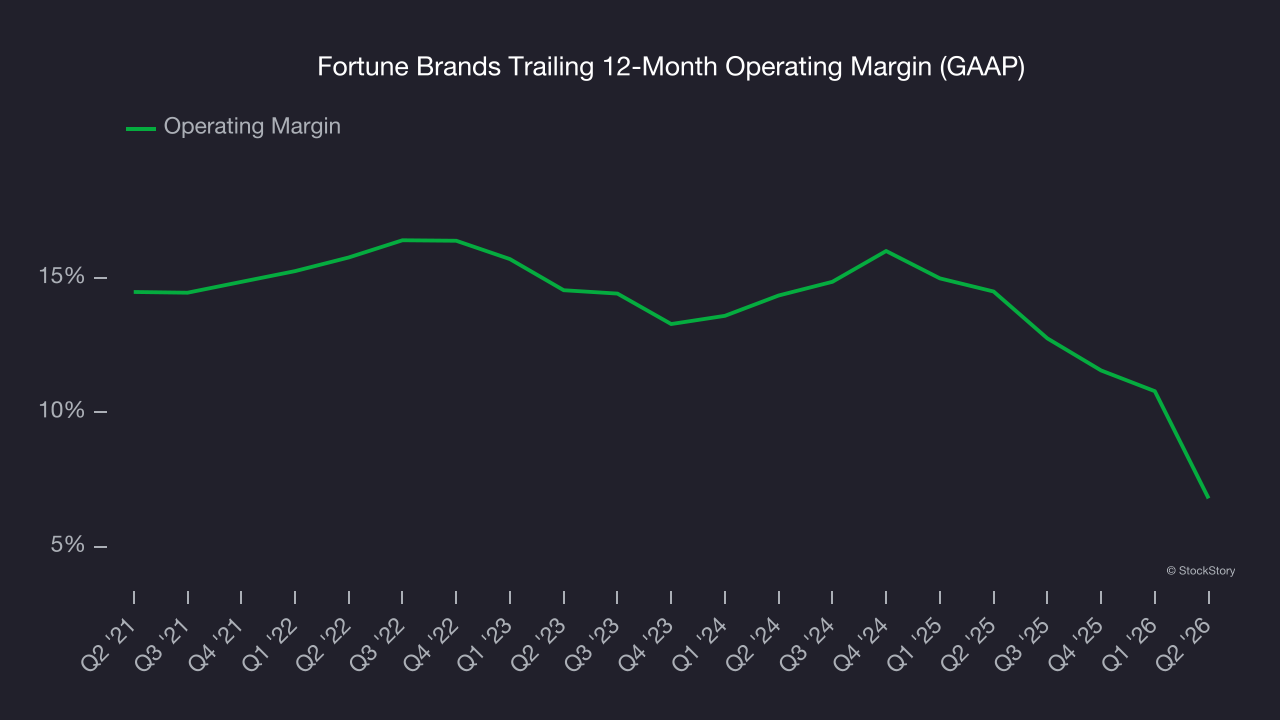
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products, and most importantly, keeping them relevant through research and development.
Looking at the trend in its profitability, Fortune Brands’s operating margin decreased by 9 percentage points over the last five years. Even though its historical margin was healthy, shareholders will want to see Fortune Brands become more profitable in the future. Its operating margin for the trailing 12 months was 6.8%.
3. EPS Trending Down
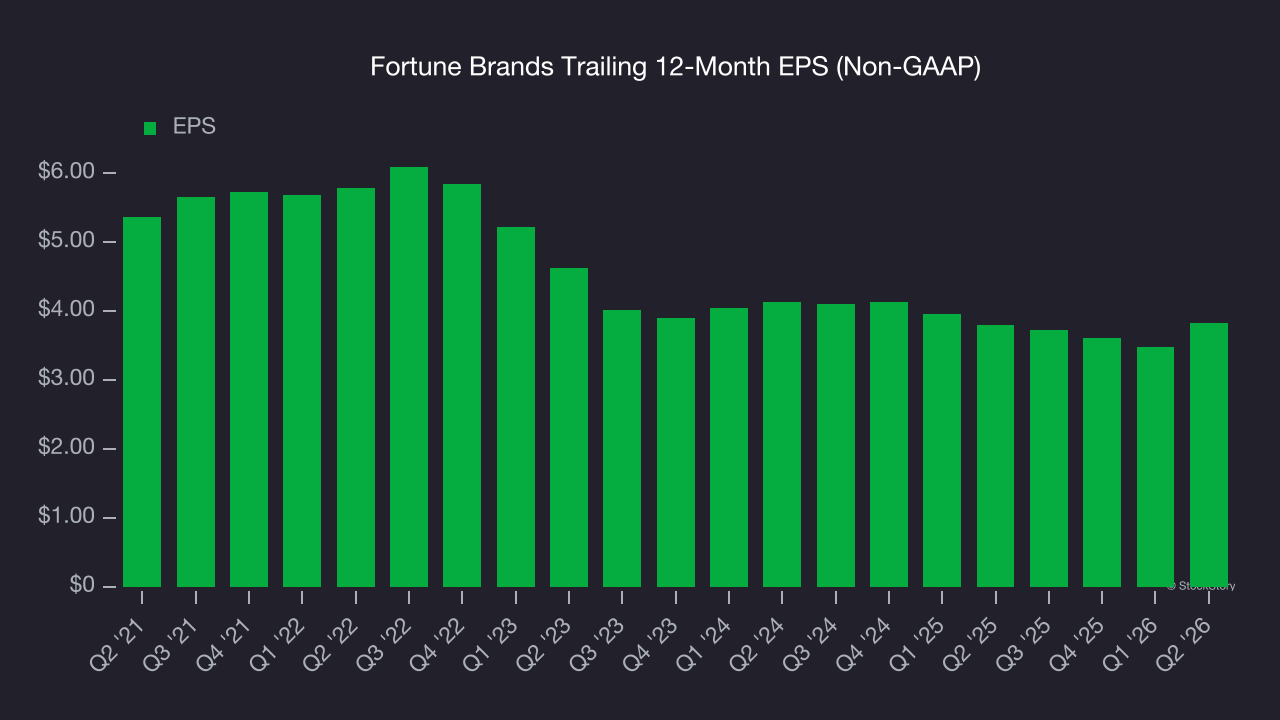
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Fortune Brands, its EPS and revenue declined by 6.5% and 9% annually over the last five years. We tend to steer our readers away from companies with falling revenue and EPS, where diminishing earnings could imply changing secular trends and preferences. If the tide turns unexpectedly, Fortune Brands’s low margin of safety could leave its stock price susceptible to large downswings.
Final Judgment
We cheer for all companies making their customers lives easier, but in the case of Fortune Brands, we’ll be cheering from the sidelines. With its shares underperforming the market lately, the stock trades at 13.5× forward P/E (or $40.70 per share). This multiple tells us a lot of good news is priced in - we think other companies feature superior fundamentals at the moment. We’d suggest looking at the most dominant software business in the world.
Stocks We Would Buy Instead of Fortune Brands
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.