

Metal coating and infrastructure solutions provider AZZ (NYSE: AZZ) reported calendar Q3 2026 (fiscal Q2 2027) results exceeding the market’s revenue expectations, with sales up 16.7% year on year to $486.9 million. The company’s full-year revenue guidance of $1.85 billion at the midpoint came in 1.8% above analysts’ estimates. Its non-GAAP profit of $2 per share was 8.4% above analysts’ consensus estimates.
Is now the time to buy AZZ? Find out by accessing our full research report, it’s free.
AZZ (AZZ) Q3 CY2026 Highlights:
- Revenue: $486.9 million vs analyst estimates of $463.4 million (16.7% year-on-year growth, 5.1% beat)
- Adjusted EPS: $2 vs analyst estimates of $1.84 (8.4% beat)
- Adjusted EBITDA: $110.9 million vs analyst estimates of $104.2 million (22.8% margin, 6.4% beat)
- The company lifted its revenue guidance for the full year to $1.85 billion at the midpoint from $1.83 billion, a 1.4% increase
- Management raised its full-year Adjusted EPS guidance to $7.15 at the midpoint, a 2.9% increase
- EBITDA guidance for the full year is $400 million at the midpoint, in line with analyst expectations
- Operating Margin: 17.2%, in line with the same quarter last year
- Market Capitalization: $4.14 billion
Tom Ferguson, President, and Chief Executive Officer of AZZ, commented, "Our record second-quarter sales of $486.9 million, up 16.7%, reflects not only strong execution but also the strength of our long-term strategy and the durability of our business model. Across our Metal Coatings and Precoat Metals segments, we continue to invest in strategic capabilities, operational excellence, and targeted growth initiatives that reinforce our competitive advantages and create sustainable value for our customers and shareholders. During the quarter, we benefited from organic sales growth, the continued ramp-up of our new Washington, Missouri facility within our Precoat Metals segment, and the completion of a strategic Metal Coatings acquisition in the Pacific Northwest. I am pleased with our record-setting performance during the first half of the year and we are on track to set new sales and profitability records for fiscal year 2027. We are increasing our annual financial guidance to reflect our quarterly performance, sustained sales momentum across both segments and increased confidence in our outlook for the remainder of fiscal year 2027."
Company Overview
Responsible for projects like nuclear facilities, AZZ (NYSE: AZZ) is a provider of metal coating and power infrastructure solutions.
Revenue Growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, AZZ grew its sales at an incredible 20.7% compounded annual growth rate. Its growth beat the average industrials company and shows its offerings resonate with customers, a helpful starting point for our analysis.
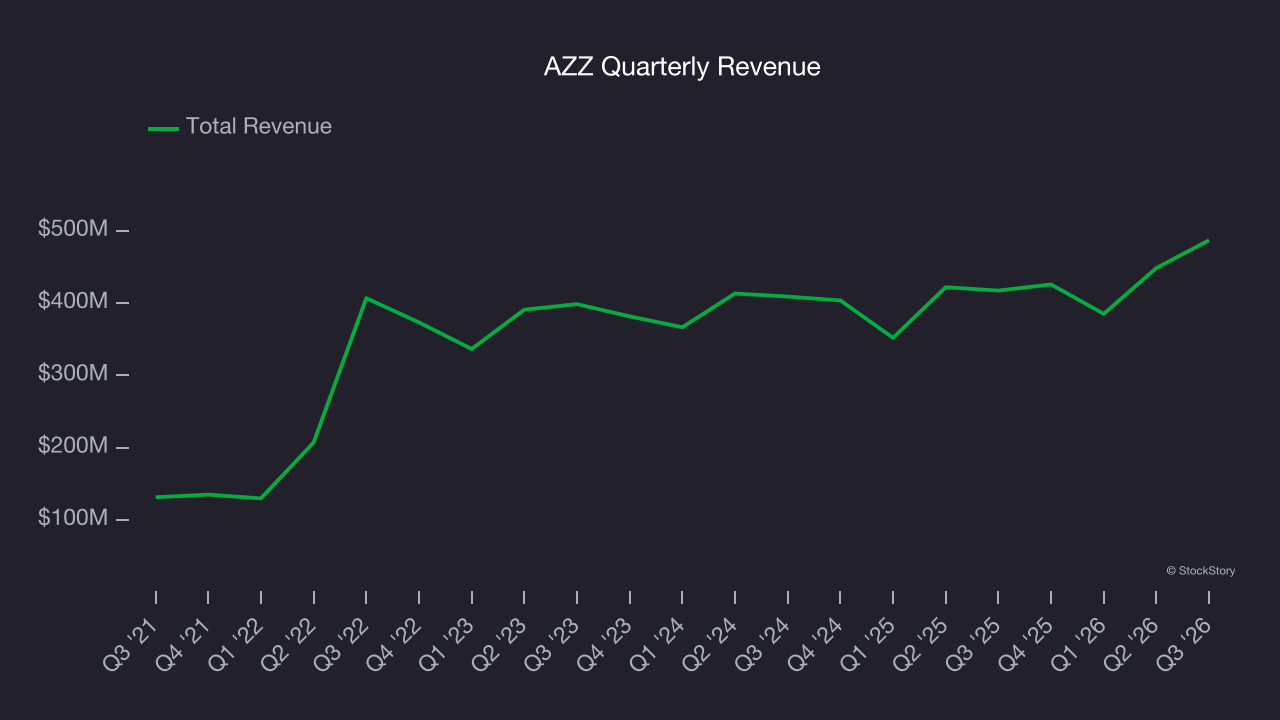
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. AZZ’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 5.5% over the last two years was well below its five-year trend. 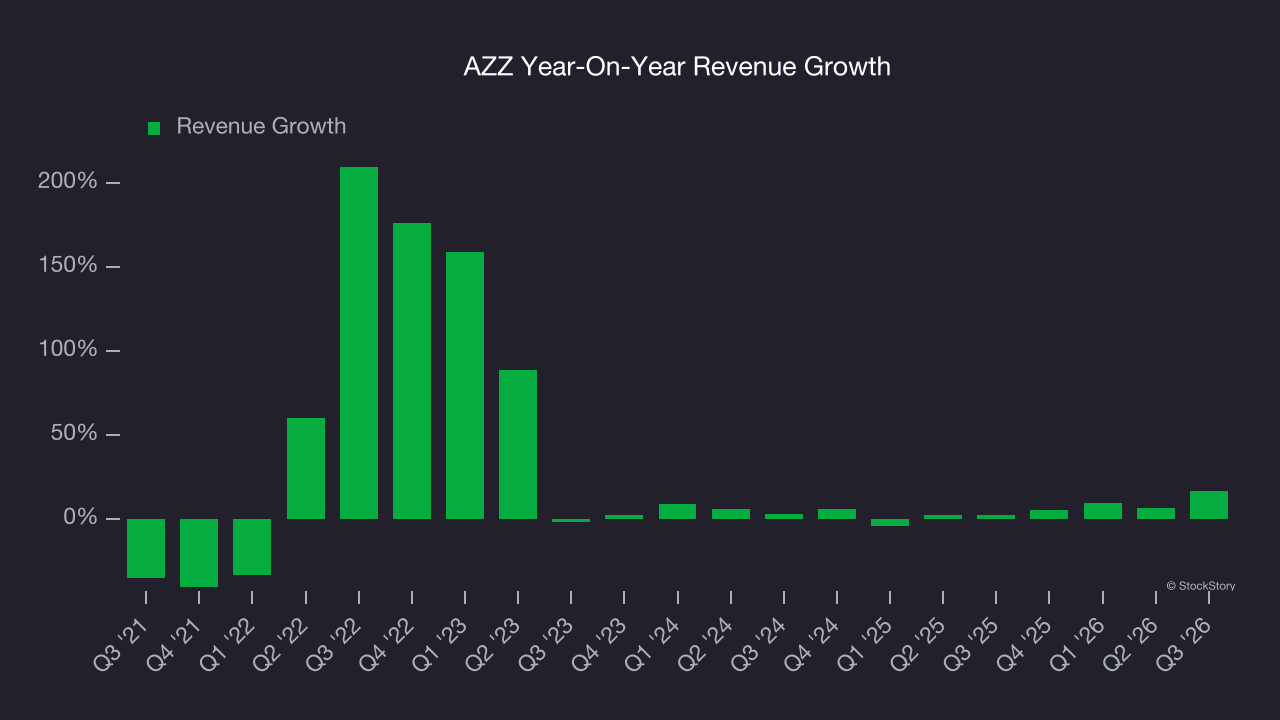
This quarter, AZZ reported year-on-year revenue growth of 16.7%, and its $486.9 million of revenue exceeded Wall Street’s estimates by 5.1%.
Looking ahead, sell-side analysts expect revenue to grow 6.6% over the next 12 months, similar to its two-year rate. While this projection indicates its newer products and services will spur better top-line performance, it is still below average for the sector. At least the company is tracking well in other measures of financial health.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Operating Margin
AZZ has been a well-oiled machine over the last five years. It demonstrated elite profitability for an industrials business, boasting an average operating margin of 15.6%. This result was particularly impressive because of its low gross margin, which is mostly a factor of what it sells and takes huge shifts to move meaningfully. Companies have more control over their operating margins, and it’s a show of well-managed operations if they’re high when gross margins are low.
Analyzing the trend in its profitability, AZZ’s operating margin rose by 1.6 percentage points over the last five years, as its sales growth gave it operating leverage.
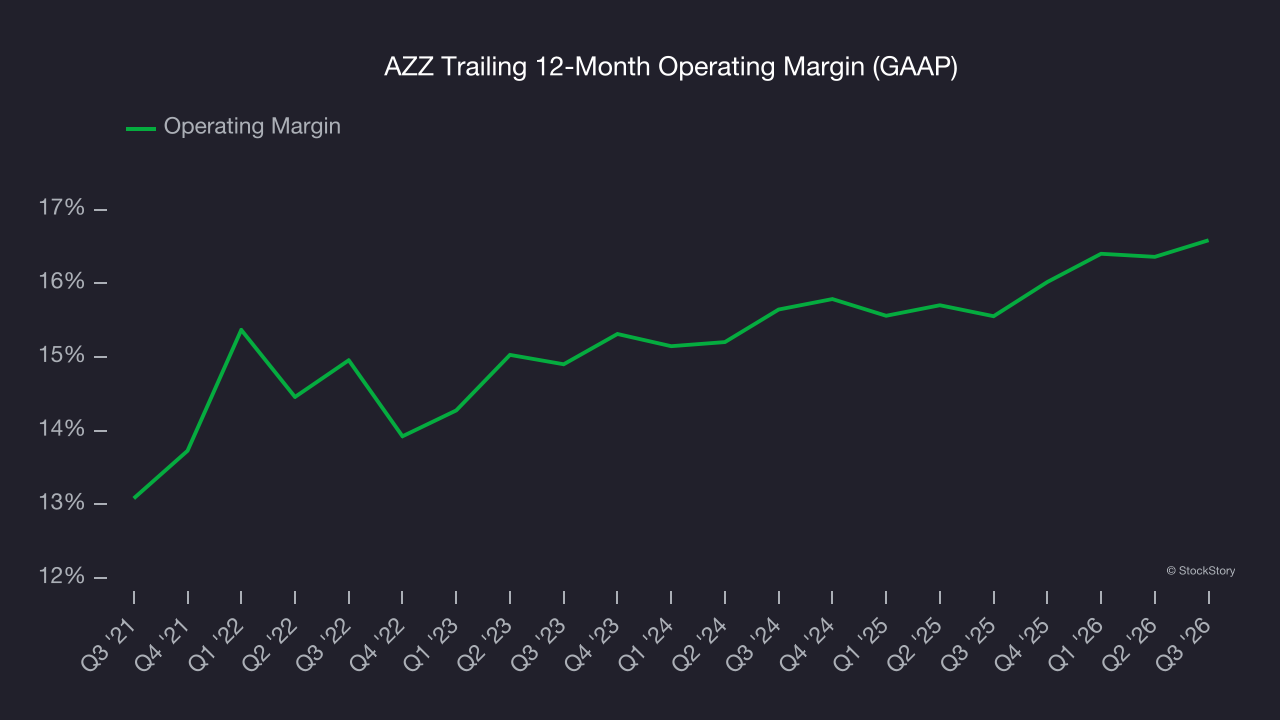
This quarter, AZZ generated an operating margin profit margin of 17.2%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
AZZ’s EPS grew at a spectacular 17% compounded annual growth rate over the last five years. Despite its operating margin improvement during that time, this performance was lower than its 20.7% annualized revenue growth, telling us that non-fundamental factors such as interest and taxes affected its ultimate earnings.
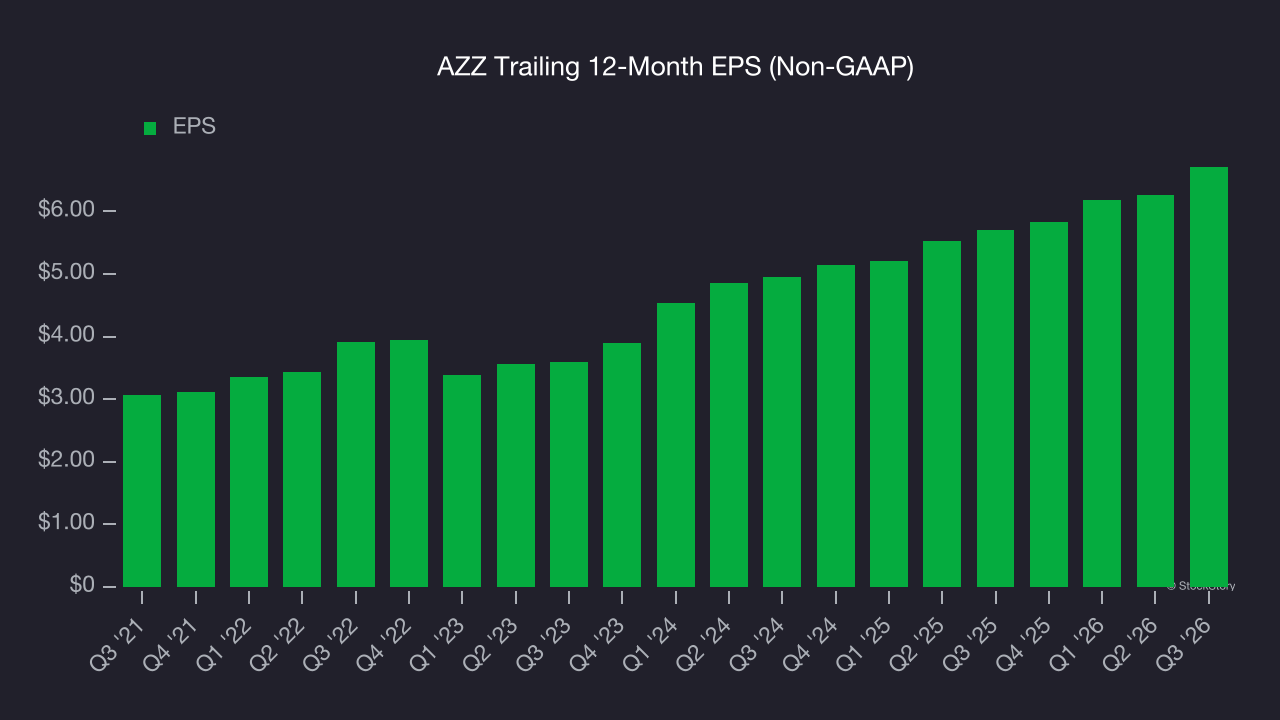
Diving into the nuances of AZZ’s earnings can give us a better understanding of its performance. A five-year view shows AZZ has diluted its shareholders, growing its share count by 19.8%. This dilution overshadowed its increased operational efficiency and has led to lower per share earnings. Taxes and interest expenses can also affect EPS but don’t tell us as much about a company’s fundamentals. 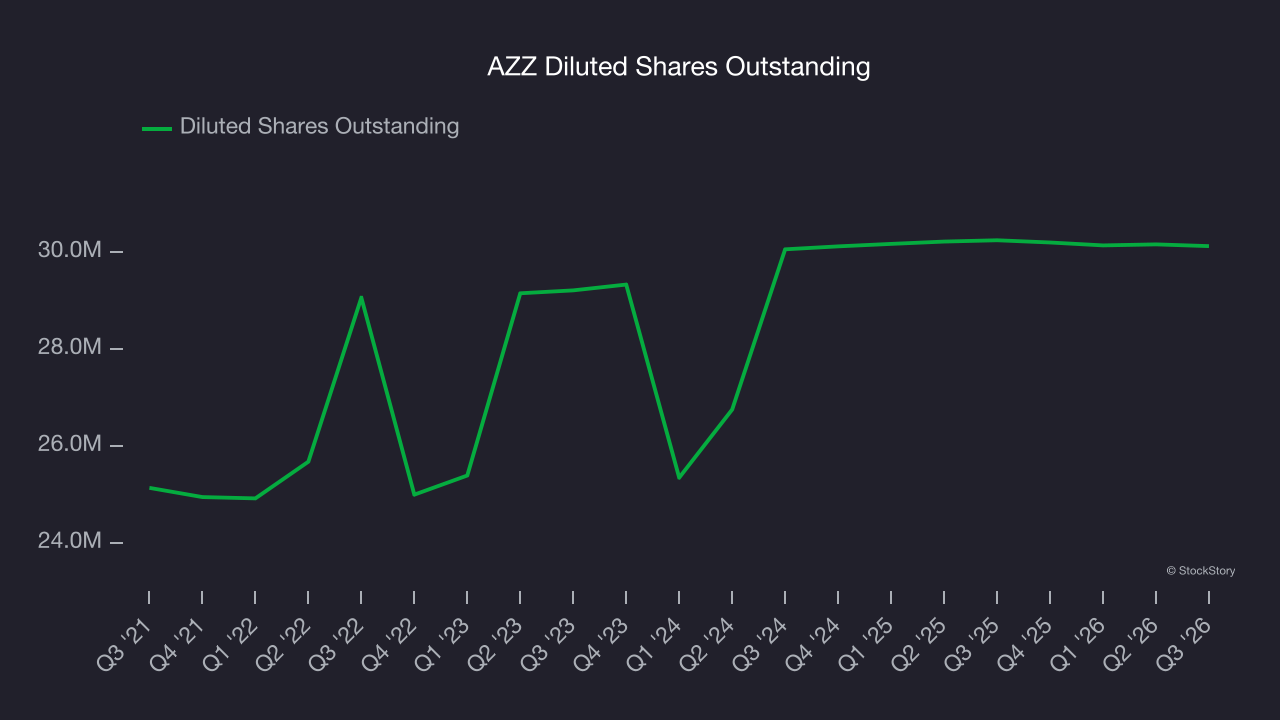
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For AZZ, its two-year annual EPS growth of 16.4% is similar to its five-year trend, implying strong and stable earnings power.
In Q3, AZZ reported adjusted EPS of $2, up from $1.55 in the same quarter last year. This print beat analysts’ estimates by 8.4%. Over the next 12 months, Wall Street expects AZZ’s full-year EPS to grow 12.6% from $6.71 to $7.55.
Key Takeaways from AZZ’s Q3 Results
We were impressed by how significantly AZZ blew past analysts’ revenue expectations this quarter. We were also glad its EBITDA outperformed Wall Street’s estimates. Zooming out, we think this was a good print with some key areas of upside. The stock traded up 2.4% to $140.55 immediately after reporting.
Sure, AZZ had a solid quarter, but if we look at the bigger picture, is this stock a buy? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).