

LKQ’s stock price has taken a beating over the past six months, shedding 22% of its value and falling to $22.85 per share. This was partly due to its softer quarterly results and may have investors wondering how to approach the situation.
Is there a buying opportunity in LKQ, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think LKQ Will Underperform?
Even with the cheaper entry price, we don’t have much confidence in LKQ. Here are three reasons why there are better opportunities than LKQ, plus one stock we’d rather own.
1. Core Business Falling Behind as Demand Declines
Investors interested in Consumer Discretionary - Specialized Consumer Services companies should track organic revenue in addition to reported revenue. This metric gives visibility into LKQ’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, LKQ’s organic revenue averaged 2.6% year-on-year declines. This performance was underwhelming and implies it may need to improve its products, pricing, or go-to-market strategy. It also suggests LKQ might have to lean into acquisitions to grow, which isn’t ideal because M&A can be expensive and risky (integrations often disrupt focus). 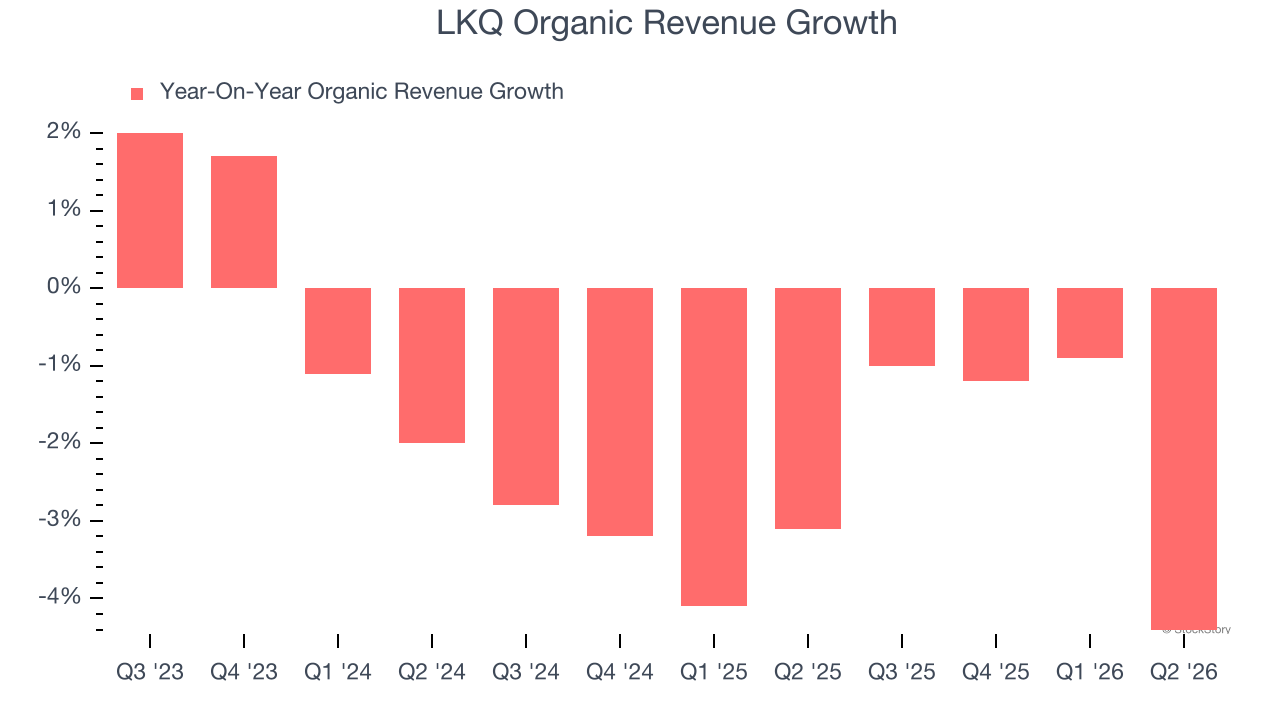
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
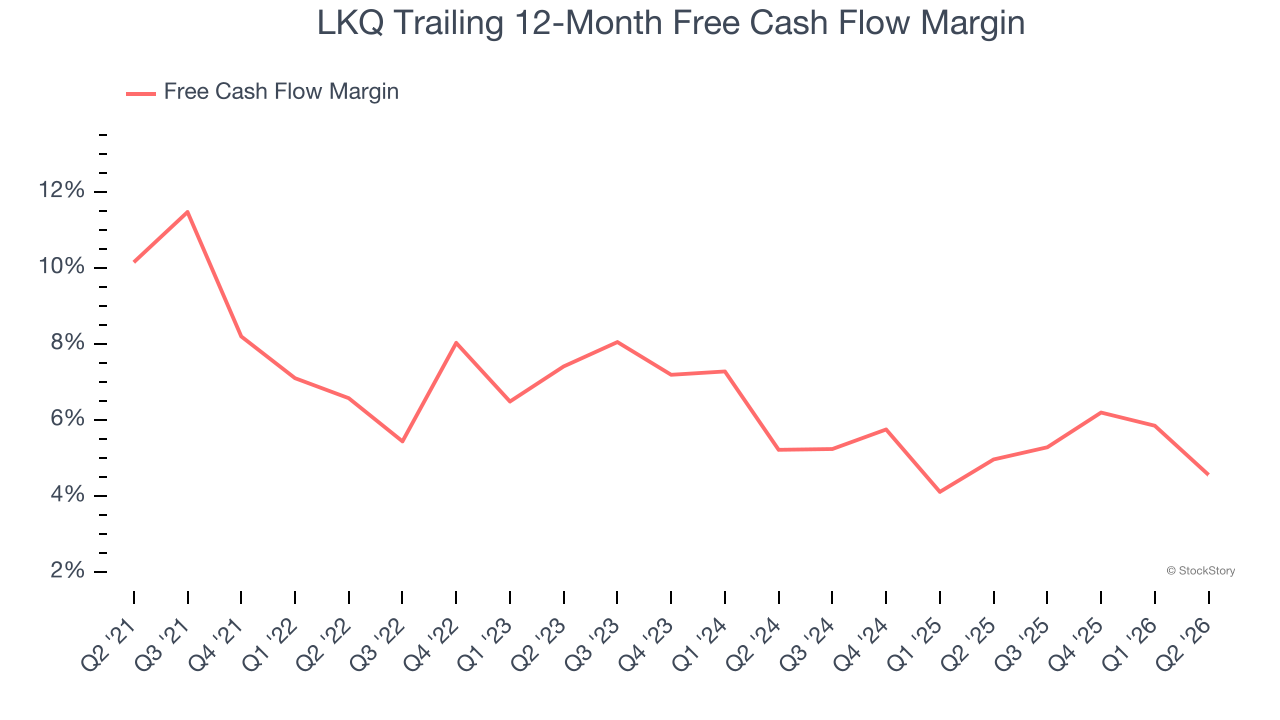
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
LKQ has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 4.8%, below what we’d expect for a consumer discretionary business.
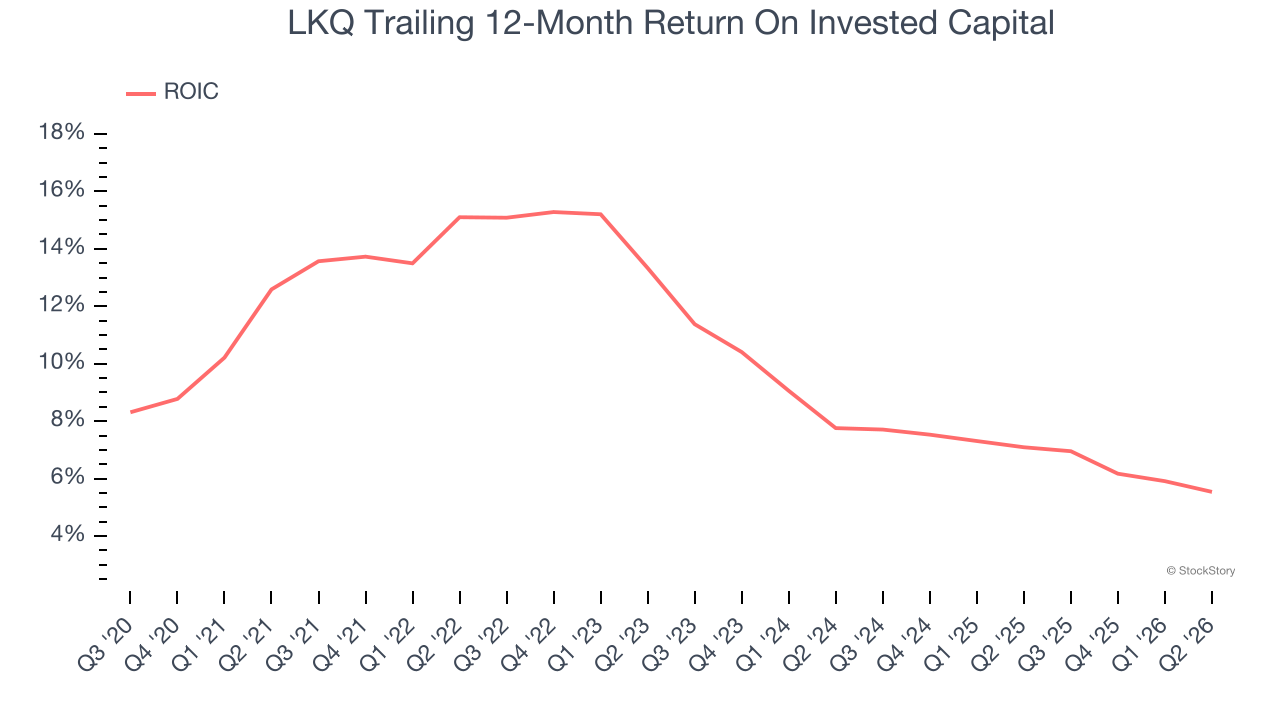
3. New Investments Fail to Bear Fruit as ROIC Declines
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Over the last few years, LKQ’s ROIC has unfortunately decreased. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
Final Judgment
LKQ falls short of our quality standards. After the recent drawdown, the stock trades at 7.9× forward P/E (or $22.85 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better investments elsewhere. We’d suggest looking at one of Charlie Munger’s all-time favorite businesses.
Stocks We Would Buy Instead of LKQ
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.